
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Automatic Data Processing (ADP) After The Run Up Is Its Valuation Still Attractive
Automatic Data Processing (ADP) is drawing attention after data showed a lower P/E ratio than peers, along with stronger profitability and revenue growth metrics, as well as a lighter debt load than top competitors.
Recent trading has tilted in Automatic Data Processing’s favor, with a 7-day share price return of 5.12% and a 90-day share price gain of 7.90%. The 1-year total shareholder return is down 2.26%, and the 5-year total shareholder return is 42.20%.
Compare Automatic Data Processing’s valuation and balance sheet strength with a curated 31 resilient stocks with low risk scores that share similar resilience profiles.
Automatic Data Processing has recently posted a solid short-term run while still screening with a lower P/E and a stronger balance sheet than many peers. After that move, does the current valuation still leave enough potential reward for new buyers?
Most Popular Narrative: 6% Undervalued
The most followed narrative currently pegs Automatic Data Processing’s fair value at $287.60, modestly above the last close of $270.88. This frames today’s price as reflecting a limited discount that depends heavily on execution in its core human capital management platforms.
Ongoing investments in AI driven automation across ADP Assist, Lyric and the Zone are supporting lower contacts per client and higher service productivity. Management now targets 70 to 90 basis points of adjusted EBIT margin expansion annually, which points to AI enabled operating leverage as a driver of future net margin and earnings.
See why 112 investors see Automatic Data Processing as 6% undervalued.
Result: Fair Value of $287.60 (UNDERVALUED)
Still, the bullish Automatic Data Processing story can crack if PEO margins stay under pressure or if AI powered HR tools attract lower cost competitors faster than expected.
Find out about the key risks to this Automatic Data Processing narrative.
Another Take On Automatic Data Processing’s Price Tag
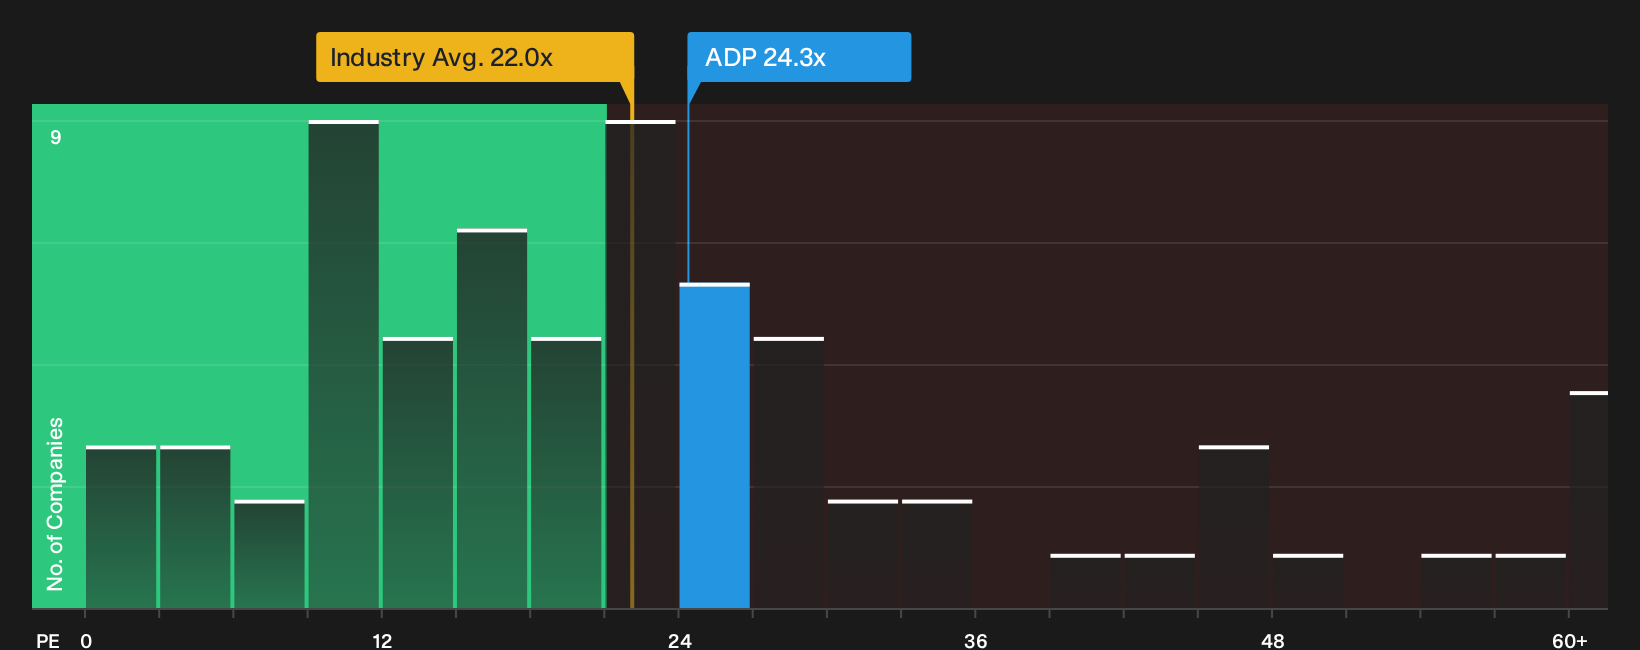
On a simple P/E basis, Automatic Data Processing does not look cheap. The stock trades at 24.3x earnings, compared with 20.5x for peers and 22x for the wider US Professional Services group. Yet the fair ratio for ADP sits higher at 25.5x, which suggests the current premium may not be extreme. Is this a small cushion or a thin margin for error?
To stress test that question against hard numbers, it helps to see what the current multiple, peer averages and the fair ratio imply for valuation risk in one place. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Automatic Data Processing so far. If you want to move quickly and form your own judgment based on the facts, start by reviewing the 3 key rewards.
Looking For More Investment Ideas Beyond Automatic Data Processing?
If you want a broader watchlist alongside Automatic Data Processing, use the Simply Wall Street Screener to uncover fresh ideas before others focus on them.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) to find companies that can handle tougher conditions without stretching their finances.
- Hunt for potential value opportunities by reviewing the 29 high quality undervalued stocks to identify companies that combine quality traits with prices that may sit below estimated fair value.
- Build an income focused shortlist by zeroing in on the 8 dividend fortresses to focus on companies that pair stronger yields with balance sheets designed to support ongoing payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com