
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Danaos (DAC) Fully Valued As Its $5 Special Dividend Draws Fresh Attention?
Danaos (DAC) just put cash returns front and center, unveiling a one-time special dividend of US$5.00 per share alongside its regular US$1.00 quarterly payout, both scheduled for October 22, 2026.
The special and regular dividends land after a strong run in Danaos shares, with a 90 day share price return of 30.72% and a year to date share price return of 77.52% as the 1 year total shareholder return reaches 107.27%. Investors who held on longer have seen the 3 year total shareholder return climb to 185.44% and the 5 year total shareholder return reach 193.21%, which indicates momentum that has been building rather than fading.
Capitalize on Danaos’ dividend momentum by scanning a curated 8 dividend fortresses that are also prioritizing shareholder cash returns.The cash windfall and strong recent run tell one story about Danaos; the price tag tells another. Is this shipping business being valued fairly for what it is today?
Most Popular Narrative: 3% Overvalued
Danaos last closed at $169.09 while the most followed narrative anchors fair value at $164.50 using a 10.37% discount rate. That gap is small, yet it frames a story where much of the perceived earnings visibility already sits in the price.
The figures related to Danaos's balance sheet strength, contracted backlog of about $4.6b and ongoing dividends suggest a share price that already incorporates much of this earnings visibility, so the stock appears fairly valued with a cautious narrative tone.
See why 31 investors see Danaos as 3% overvalued.
Result: Fair Value of $164.50 (OVERVALUED)
Still, the Danaos story could be challenged if the US$4.6b backlog or charter coverage is reassessed, or if dry bulk and LNG linked plans underwhelm expectations.
Find out about the key risks to this Danaos narrative.
Another View On Danaos: Earnings Multiple Signals Value Gap
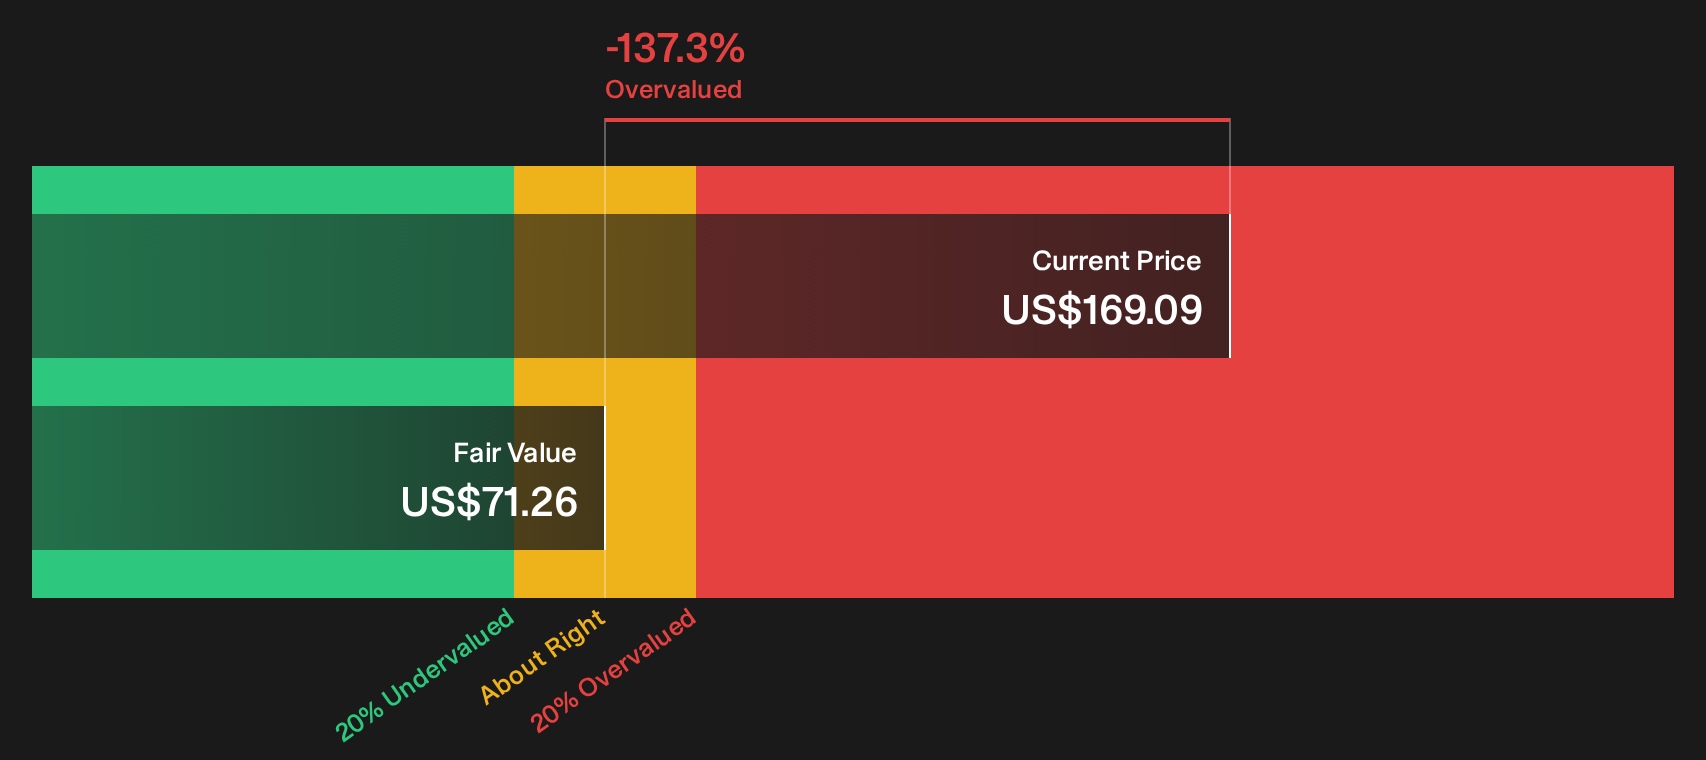
The SWS DCF model suggests Danaos is priced well above an estimated future cash flow value of about $71.26 per share, which leans toward an overvalued reading. By contrast, a 5.7x P/E against a fair ratio of 10.2x points to a wide valuation gap investors need to reconcile.
That split between cash flow modelling and earnings based pricing raises a simple question. Which signal should carry more weight for your Danaos thesis: the discounted cash flow view or the income statement today. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Danaos are already clear. If you want your own take, move quickly through the underlying numbers and check the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Danaos?
If Danaos has sharpened your focus on opportunity and risk, broaden your watchlist now so you are not relying on a single shipping story.
- Target resilient payers by scanning 8 dividend fortresses designed for investors who want income potential backed by substantial balance sheet support.
- Hunt for pricing disconnects with the 29 high quality undervalued stocks that highlights companies pairing solid fundamentals with what may be conservative market expectations.
- Protect your downside by filtering through the 31 resilient stocks with low risk scores to spot businesses that score well on stability and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com