
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Japan Prime Realty Investment (TSE:8955), Why Is It Getting Fresh Attention Today?
Japan Prime Realty Investment (TSE:8955) has arranged a new green loan that links fresh funding to its sustainability framework. The move connects the refinancing of the Yume ooka Office Tower to environmental criteria and balance sheet diversification.
At a share price of ¥88,900, Japan Prime Realty Investment has seen its short term share price return weaken, with the 30 day move down 5.93% and the year to date share price return down 15.65%. However, the 3 year total shareholder return of 13.53% points to a more resilient long run record and suggests sentiment has cooled recently despite initiatives like the new green loan and a P/E ratio of 18.9x that sits above the sector average but close to its estimated fair ratio.
Scan a curated 13 high quality undervalued stocks that, like Japan Prime Realty Investment, combines established cash flows with valuations that may not fully reflect their sustainability and balance sheet stories.
Japan Prime Realty Investment now trades on an 18.9x P/E after a weak year-to-date share price. Are investors already fully compensated for its stability and green financing push, or does further upside remain?
Price-to-Earnings of 18.9x: Is it justified?
Valuation currently leans rich for Japan Prime Realty Investment, with an 18.9x P/E sitting above both peer and industry averages despite the weaker recent share price record.
The P/E ratio compares the ¥88,900 unit price to the trust's earnings, and for a REIT investor it is a quick shorthand for how much is being paid for each yen of profit. For a vehicle focused on Japanese office and retail properties, this multiple frames what the market is willing to pay for relatively steady rental income and the current 4.86% distribution yield.
What matters is how that 18.9x level stacks up. On one side, the P/E is higher than the Asian Office REITs industry average of 14.6x and also above the peer group at 17.8x, which points to a premium being paid for Japan Prime Realty Investment's earnings. On the other side, the ratio sits slightly below the estimated fair P/E of 19.8x, which suggests that, if the market fully aligned with that fair level, the current multiple could have room to move up toward it.
Explore the SWS fair ratio for Japan Prime Realty Investment.
Result: Price-to-Earnings of 18.9x (OVERVALUED)
Still, the recent 1 year share price decline and a P/E above industry peers leave Japan Prime Realty Investment exposed if rental demand or green financing appetite softens.
Find out about the key risks to this Japan Prime Realty Investment narrative.
Another View: Our DCF model points in the opposite direction
The P/E story paints Japan Prime Realty Investment as only slightly stretched. The SWS DCF model tells a tougher tale, with an estimated future cash flow value of ¥26,476.11 per unit against a current price of ¥88,900. On that math, the units screen as heavily overvalued. Which signal should carry more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
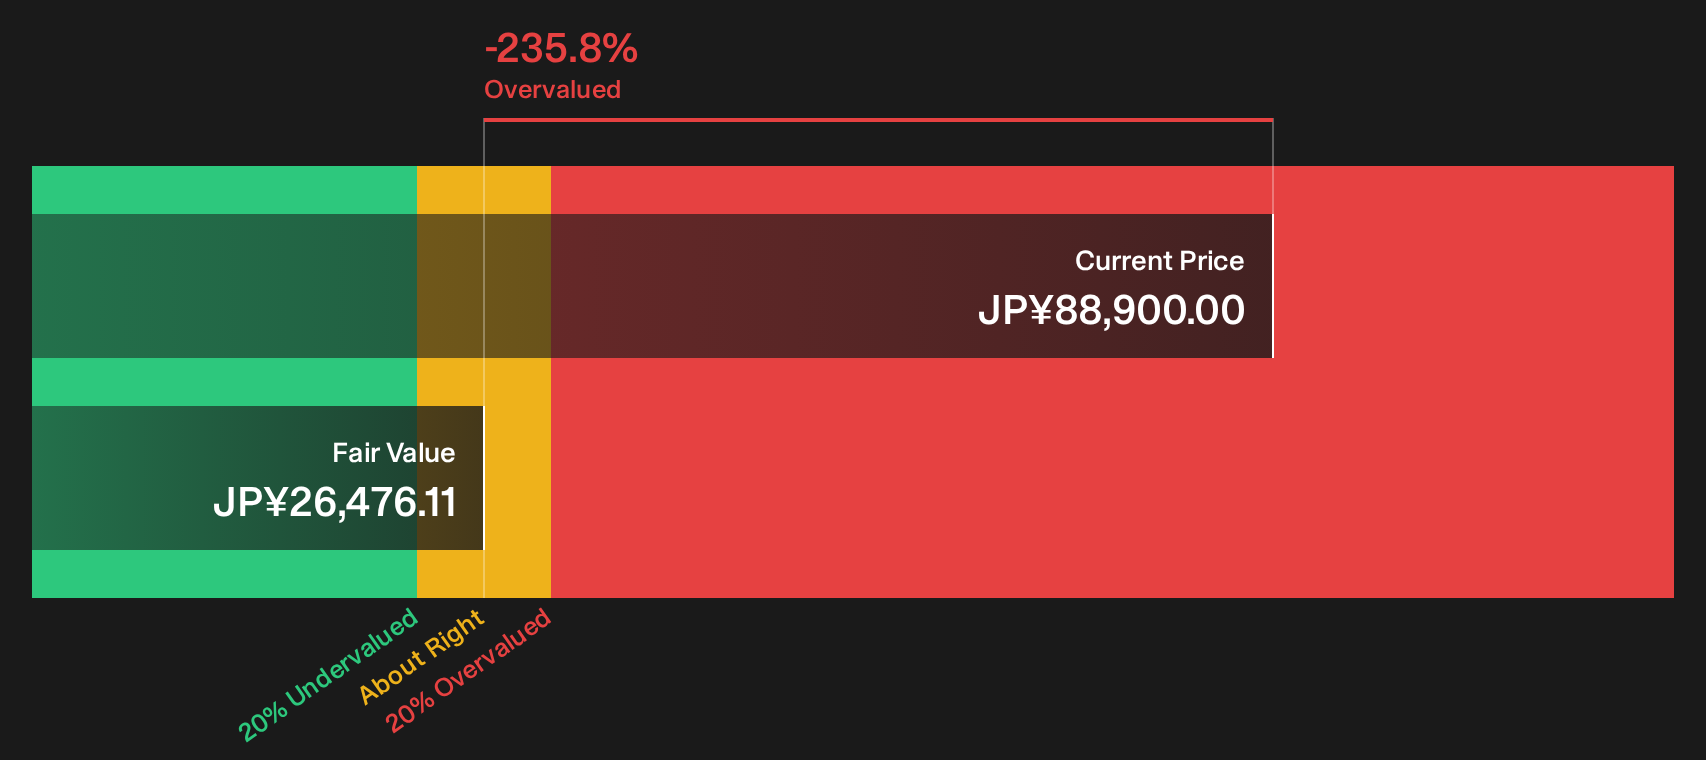
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Prime Realty Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Japan Prime Realty Investment so far. If you want a clear stance, act quickly, review the same numbers and then test your own thesis against our 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Japan Prime Realty Investment?
Do not stop your research with one REIT. Broaden your watchlist with a few focused stock ideas that match how you like to balance risk, income and value.
- Target potential mispricing by scanning a curated group of higher quality companies that still look overlooked through the 13 high quality undervalued stocks.
- Strengthen the income side of your portfolio by reviewing a handpicked set of higher yield opportunities in the 28 dividend fortresses.
- Prioritise resilience and capital protection by filtering for sturdier businesses using the 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com