
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Honeywell International (HON) Lands Kenya Refinery Deal As Valuation Debate Heats Up
Honeywell International (HON) just landed a fresh contract with Dangote Petroleum Refinery and Petrochemicals FZE, supplying technologies and services for a 700,000 barrel-per-day refinery project planned in Kenya.
For context, Honeywell International’s share price is around US$207.73, with a 1 day share price return of 0.55% and a 30 day share price return of 2.65%, while the year to date share price return has fallen 46.98%. Over longer stretches, total shareholder return of 6.74% over one year and 21.92% over three years suggests that despite recent weakness, investors who stayed in the stock have still seen positive compounding. The Dangote refinery win arrives as momentum has been fading rather than accelerating.
Scan how Honeywell International’s refinery win compares with other industrial heavyweights by reviewing the hand picked 43 power grid technology and infrastructure stocks now shaping critical energy infrastructure projects.
Honeywell International just picked up a sizeable refinery project while the share price has been sliding this year. Does that setup reward buying now, or does it argue for waiting until valuation does more of the work?
Most Popular Narrative: 35.1% Undervalued
On the most followed narrative, Honeywell International’s fair value of $320.19 sits well above the last close at $207.73. This frames the Dangote refinery contract as one piece of a wider automation and energy story rather than a one-off win.
Honeywell Automation (RemainCo) is a pure-play industrial automation and energy technology compounder with a confirmed June 29 catalyst, $19B+ in contracted backlog, a sold-out LNG order book, a global SAF technology licensing position, a recurring revenue platform transition underway via Forge, and an embedded position on both sides of the energy transition. All of this is trading at a conglomerate discount that disappears in 53 days. The floor is a durable, dividend-growing, installed-base compounder with products in virtually every commercial building and industrial facility on earth. The ceiling is the moment the market realizes RemainCo connects building automation, energy technology licensing, and AI infrastructure demand into a single story.
See why 67 investors see Honeywell International as 35% undervalued.
Result: Fair Value of $320.19 (UNDERVALUED)
Still, Honeywell International faces pressure if its revenue and net income, which both declined on an annual basis, continue to lag while the 2026 separation fails to re-rate the P/E multiple.
Find out about the key risks to this Honeywell International narrative.
Another View: Honeywell International Through A Cash Flow Lens
The fair value narrative presents Honeywell International as materially undervalued at $320.19 compared with a $207.73 share price. The SWS DCF model takes a different angle. On that framework, HON at $207.73 trades above an estimated future cash flow value of $137.98, which flags the stock as overvalued on this measure and raises the question of which lens investors should consider more closely.
For readers who want to see how this cash flow based estimate is built step by step, Look into how the SWS DCF model arrives at its fair value..
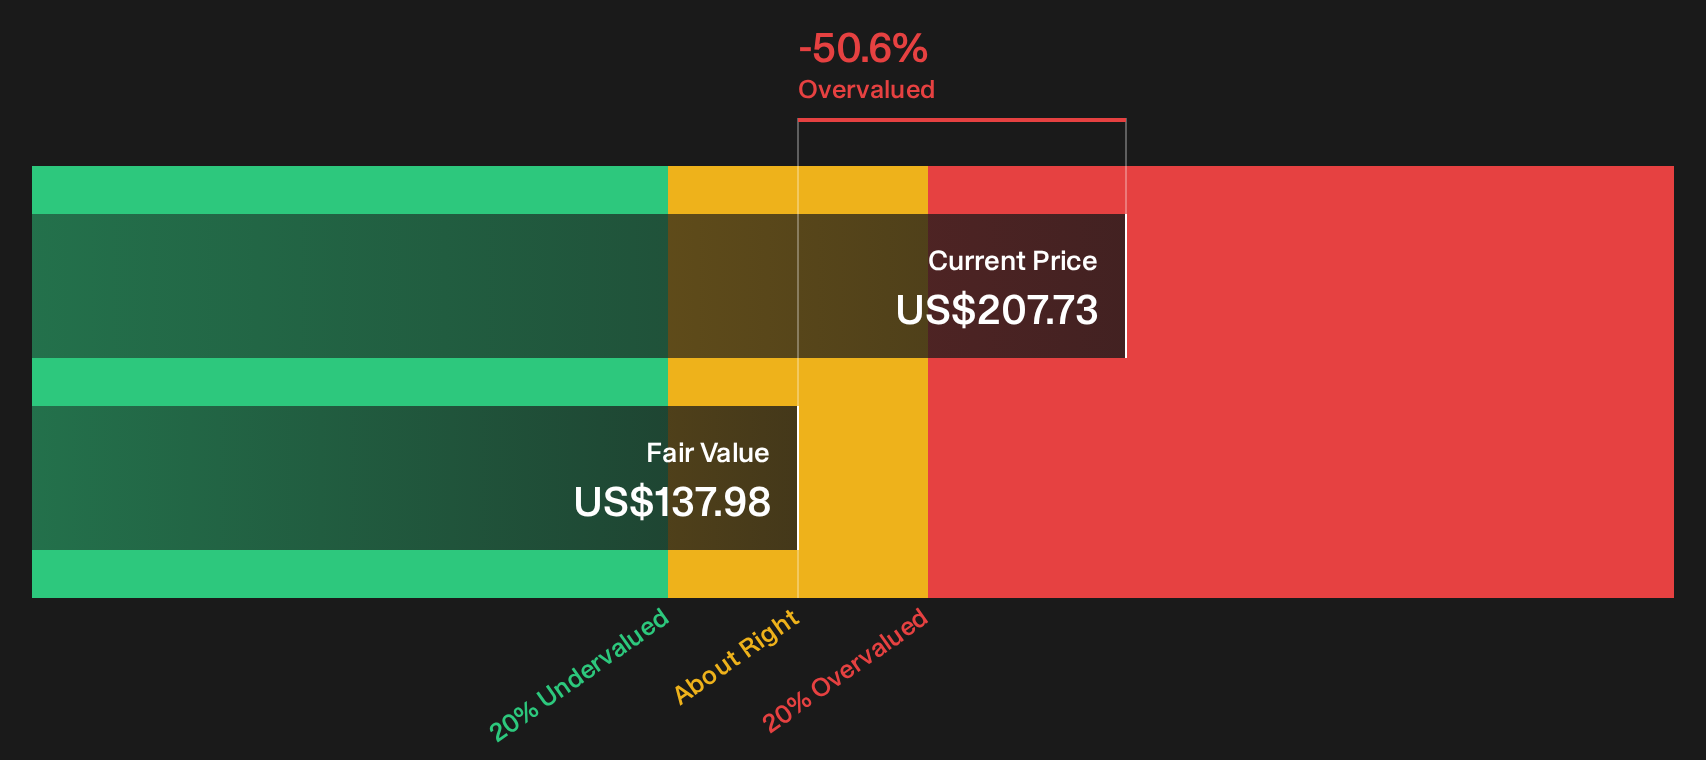
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Honeywell International can leave even experienced investors uncertain, so move quickly to test the data yourself and weigh both sides of the story. To see the full spread of potential upside and downside signals in one place, start with the 4 key rewards and 3 important warning signs.
Looking for more Honeywell International sized ideas?
If Honeywell International has you rethinking what belongs in your portfolio, do not stop here. Broader idea hunting now can change your next few years.
- Target stronger upside potential by scanning the 29 high quality undervalued stocks that combine quality fundamentals with pricing that the market has not fully recognized yet.
- Shape a steadier income stream by reviewing the 8 dividend fortresses built around higher yields with an emphasis on durability over headline payout.
- Protect your downside by focusing on the 31 resilient stocks with low risk scores that pair resilient balance sheets with more measured volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com