
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How New Steel Plant Contract Will Impact Danieli Stock Investors
- Danieli & C. Officine Meccaniche secured a contract from Stomana Industry S.A., part of the SIDENOR Group, to supply advanced rolling mill and automation equipment that integrates a relocated Danieli K-Spool line and supports higher quality rebar and SBQ production at the Pernik plant in Bulgaria.
- The project expands Danieli & C. Officine Meccaniche's role in process automation and metallurgical control, as the supply includes an eight pass finishing block, updated cooling systems, and technologies such as thermomechanical rolling combined with Soft Quenching to support tighter product consistency for a key regional steel producer.
- This analysis considers how Danieli & C. Officine Meccaniche's investment narrative is influenced by the Stomana rolling mill contract win and the associated automation scope.
Scan how Danieli & C. Officine Meccaniche compares with other metal and industrial suppliers by running the curated list of solid balance sheet and fundamentals (204 results) for ideas with similar operational footing.
What Is Danieli & C. Officine Meccaniche's Investment Narrative?
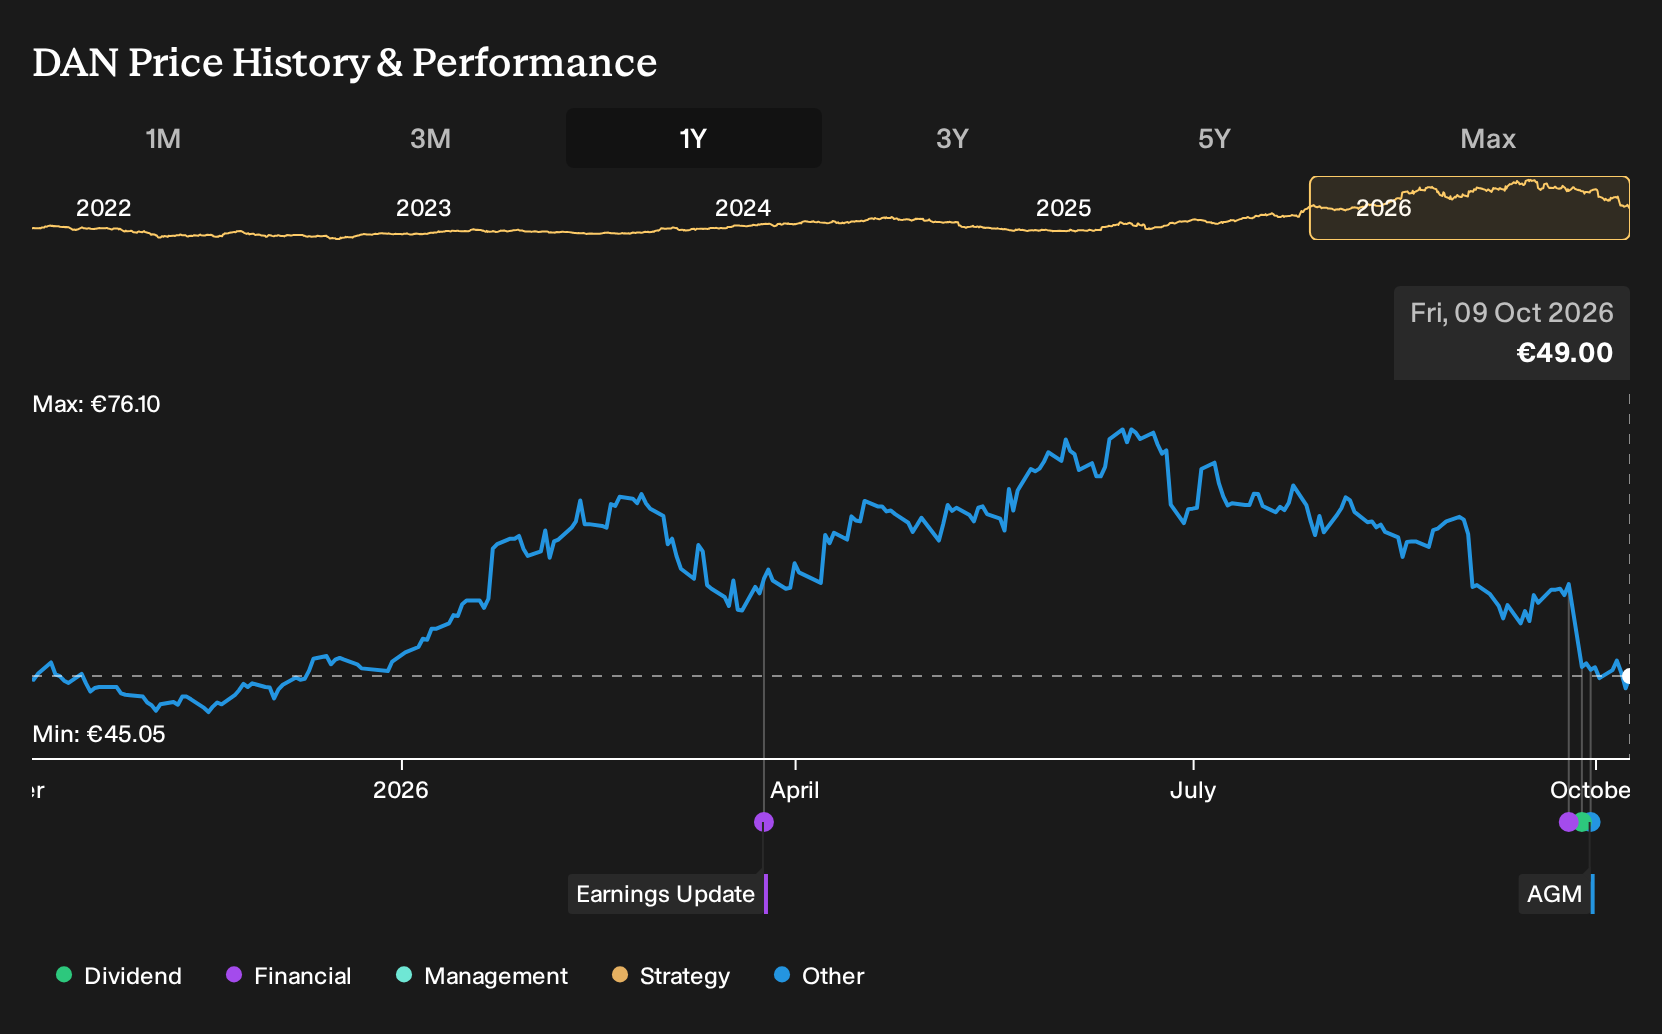
To own Danieli & C. Officine Meccaniche, you need to believe in a heavy engineering business that can keep turning a lumpy project cycle into fairly steady earnings and cash. Plant Making is capital intensive and execution heavy, so the real story sits in order quality, delivery discipline, and pricing power with large steel producers. The Stomana contract and the dividend affirmation at €0.3100 per share both point to ongoing commercial traction and balance sheet comfort, yet the share price has still fallen 27.7% over 90 days and 13.7% over 30 days, which shows how quickly sentiment can move in this sector.
Conference slots at Aluminium Düsseldorf and the IAS Steel Conference keep Danieli & C. Officine Meccaniche in front of key customers, and that can matter for the next wave of orders, but these events are more about medium term positioning than near term earnings. The bigger swing factors right now are project execution, working capital needs on a €3.8b revenue base, and whether forecast earnings growth of 13.7% per year actually shows up in reported numbers while the stock trades on a 15.2x P/E with a history of share price volatility.
That said, the picture looks different once you consider how dependent this setup is on ...
There's only one way to know the right time to buy, sell or hold Danieli & C. Officine Meccaniche. Head to Simply Wall St's company report for the latest analysis of Danieli & C. Officine Meccaniche's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between €63.50 and about €71.86 per share, so private investors are not aligned on where Danieli & C. Officine Meccaniche should trade. You now have fresh conference exposure and a new Stomana contract to weigh, which could shift how you view those earlier assumptions.
Explore 2 other Danieli & C. Officine Meccaniche fair value estimates, including one that suggests as much as 47% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Danieli & C. Officine Meccaniche research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Danieli & C. Officine Meccaniche. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Danieli & C. Officine Meccaniche's overall financial health at a glance.
Looking For More Investment Ideas Beyond Danieli & C. Officine Meccaniche?
If the Danieli & C. Officine Meccaniche story has sharpened your thinking about balance sheets, cash generation, and execution risk, it can help to test that same framework on a wider watchlist built from clear filters rather than headlines.
- If capital preservation is a priority, start with companies that pair robust finances with measured risk profiles using the 223 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, line up candidates with solid fundamentals that still trade below many fair value estimates through the 178 high quality undervalued stocks.
- If you want to broaden your research into less crowded opportunities, look at financially sound smaller stocks that attract less attention using the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com