
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Evotec Investors Missed Before A 59% Fall
If you bought Evotec for its pharma alliances and AI promise, the past year has been bruising. Investors who held Evotec over the past year are down 58.7%, including dividends. That outcome sits awkwardly beside earlier expectations of mid single digit revenue growth, a swing from heavy losses to positive margins, and a much higher future P/E. If those were the pillars of the original case, which of them did reality challenge rather than completely invalidate?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Evotec has already moved. Pinpoint other ways to investigate the theme among 127 healthcare AI stocks.
The Two Evotec Stories Investors Were Balancing
The shares cost €6.76 at the start of the period, and anyone looking at Evotec then had to choose between two very different but plausible stories.
The bullish narrative put Fair Value at €9.47, about 40% above the start price. This view hinged on revenue expanding 8.3% a year and profit margins improving to 5.5% as pharma partnerships and AI platforms scaled.
The more cautious view set Fair Value at €6, 11% below the start price. It focused on a 4.2% revenue growth assumption and the risk that inflation and regulation would pressure margins, despite a 6.6% profit margin estimate and a 21.7x future P/E.
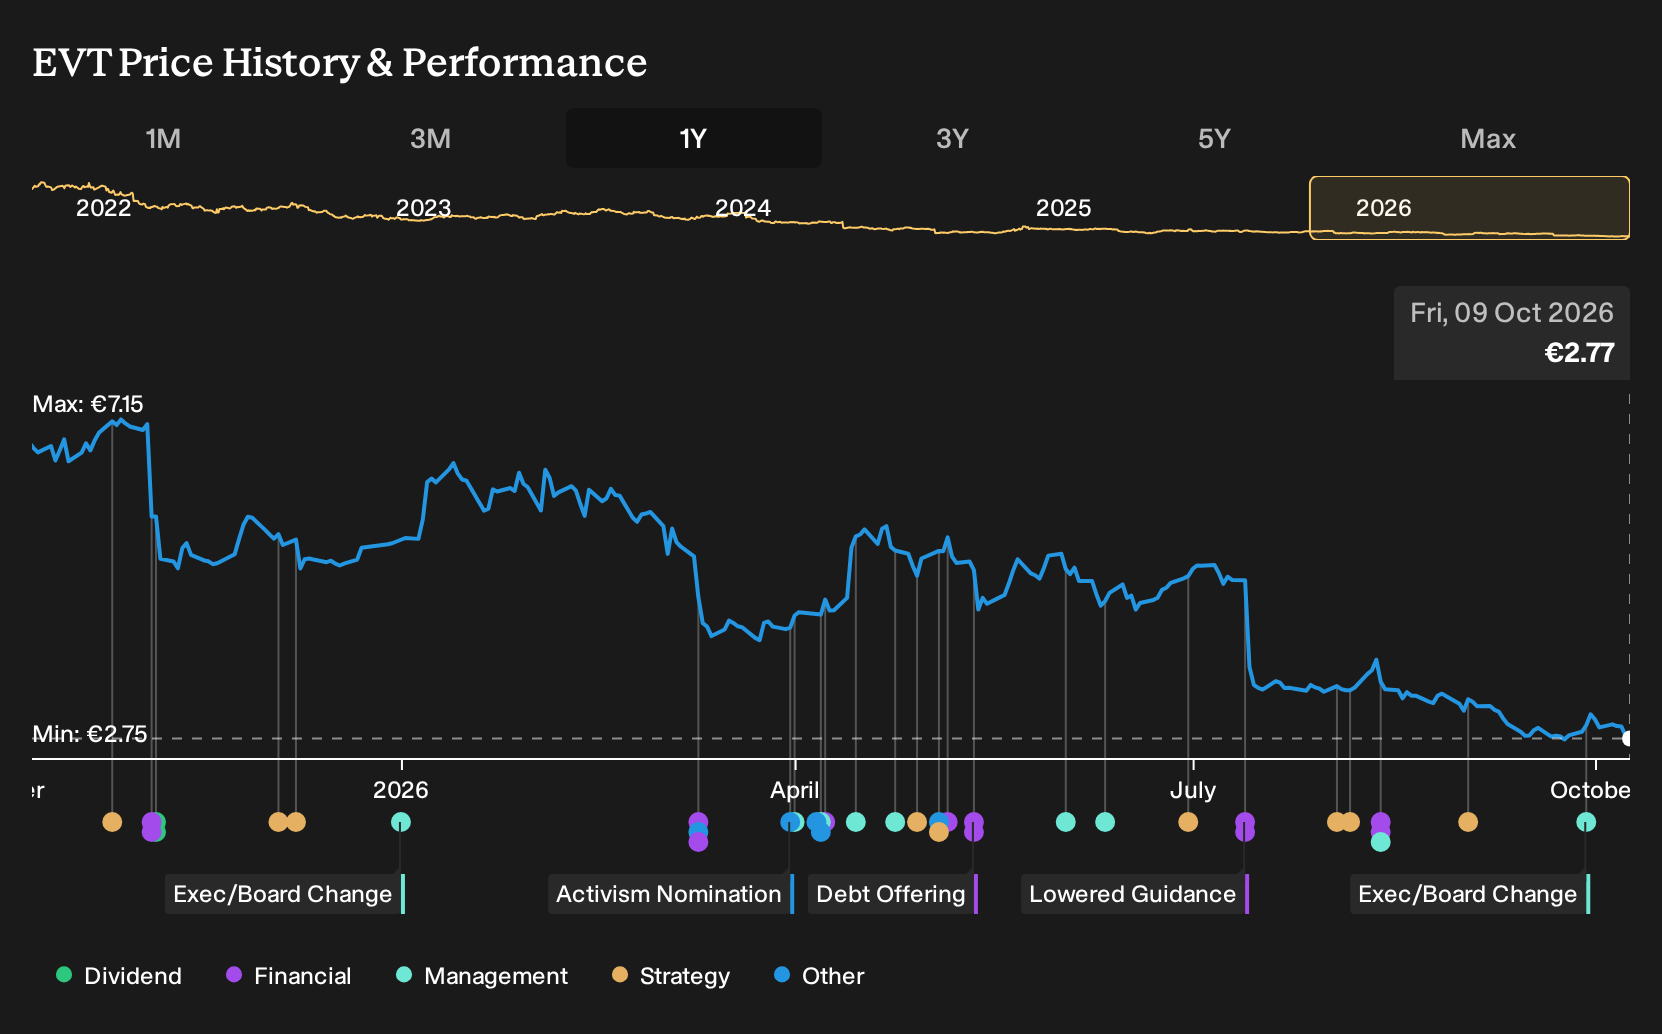
What The Evidence Did To The Evotec Argument
The clearest jolt to the bullish Evotec story was management cutting 2026 revenue guidance to €570–610m and moving adjusted EBITDA from an expected profit to a projected loss of €70–105m. Reported figures echoed that pressure. Revenue in Q2 2026 was €143.5m against €171.2m a year earlier, and the net loss widened with margin moving from -25.4% to -32.5%. The cautious case about profit risk and margin strain gained support.
The episode turned on how quickly a margin recovery thesis can get tested. When you see a profitability story, track both the direction of formal guidance and the sign of net margin in the next set of results, then decide what P/E or future margin you are really willing to assume.
What Evotec’s Lower Price Now Really Asks You
Today Evotec trades at €2.77, after the share price fell 58.7% over the past year. The selected Narrative still places its Fair Value above that level and argues that the market is not fully crediting the AI drug discovery and biologics platform.
For that higher Fair Value to be reached, a buyer today would need to believe Evotec’s AI driven partnerships and biologics royalties can support meaningfully higher long run earnings.
"Leadership in AI-driven, multi-omics drug discovery and continuous manufacturing uniquely positions Evotec for accelerated growth, premium pricing power, and high-margin partnerships. Strong international demand and an asset-light, recurring revenue model support revenue diversification and long-term operational leverage beyond current market expectations."
The price and this Narrative do not agree. → Uncover what this Narrative says Evotec is actually worth
Find Your Own Contrarian Opportunity
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 49% below our estimate - tests whether early adoption of intervention devices leads to sustained procedure volumes.
- Company 2 - 39% below our estimate - adds automated composite capacity so new airframe programs support operating leverage.
- Company 3 - 31% below our estimate - absorbs a new distribution network to deepen model offerings and export capabilities.
That is three of the list. See all 178 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com