
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
E Commerce Rebound Might Change The Case For Investing In P&G (PG)
- In recent days Procter & Gamble has drawn attention as Evercore ISI upgraded the stock, citing improved U.S. e-commerce performance, especially on Amazon, and a stronger outlook for volume driven growth from higher margin brands.
- The focus on volume led gains in profitable categories links directly to Procter & Gamble’s push to use product strength and execution, not just pricing, to support its long term earnings profile.
- The current plan is to evaluate how Procter & Gamble’s refreshed e-commerce momentum, particularly on Amazon, could reshape the existing investment narrative.
Procter & Gamble Investment Narrative Recap
To own Procter & Gamble, you need to be comfortable with a slow and steady profile, where brand strength, efficiency programs like Supply Chain 3.0, and consistent cash returns do most of the work. The key short term swing factor is how effectively those productivity gains offset the roughly US$1.4b cost and macro headwind management has flagged for fiscal 2027.
The biggest risk right now is pressure on margins if input costs and tariffs stay elevated while retailers in markets like North America keep adjusting inventory. The recent Evercore ISI upgrade and e commerce share improvement highlight opportunity, but they do not fundamentally change that cost and trade dynamic yet.
The Pampers Wipes redesign might look small on the surface, yet for Procter & Gamble it sits right in the wheelhouse of what tends to matter most: product performance in everyday categories. One wipe per pull is about execution at the shelf, where a smoother experience can help support brand preference when parents are under financial pressure.
This type of incremental upgrade also lines up with the broader catalyst story around R&D spend and product superiority funding volume driven growth. The operational test is whether a stream of similar improvements across Pampers, Pantene and other lines helps the business retain share while it absorbs higher costs and works through retailer volatility.
What The Procter & Gamble Forecasts Assume
Analysts sketch a fairly methodical path for Procter & Gamble, with forecasts that lean on modest revenue growth, a small uplift in margins and steady earnings progress rather than any big step change. The numbers are explicit, which gives you a clear checklist to compare with your own expectations for the business.
On the top line, the consensus view points to revenue expanding by 2.8% a year over the next few years. That pace lines up with a mature branded goods group leaning on product upgrades, selective price and mix, and some help from channels like Amazon rather than outsized category growth. It is a tempo that assumes the shopper keeps spending on everyday staples, even if trading patterns in markets like North America stay choppy.
Earnings forecasts are where the Evercore ISI upgrade meets the broader consensus. Analysts are modelling profit of US$15.8b today, stepping up to US$18.2b by about 2029 as margin assumptions move from 18.1% to 19.3%. The gap between current and projected profit level implies the productivity pipeline, including Supply Chain 3.0, needs to keep delivering savings that can fund brand support while still widening the bottom line.
Those same projections rely on a gentle shrink in the share count. Forecasts call for outstanding shares to fall by about 0.53% per year over the next three years. For you as an investor, that pattern can support earnings per share even if headline profit growth is relatively measured. It also fits with Procter & Gamble's history of returning a sizeable pool of cash through dividends and buybacks.
Valuation assumptions are just as important as the earnings path. On the Simply Wall St numbers, analysts frame a scenario in which the stock trades on a P/E of 24.8x by 2029, up from about 21.6x today and above the 22.9x level quoted for the wider US household products group. That means the story is not only about whether Procter & Gamble can hit its profit targets, but also whether the market stays willing to pay a richer multiple for what remains a steady consumer staples profile.
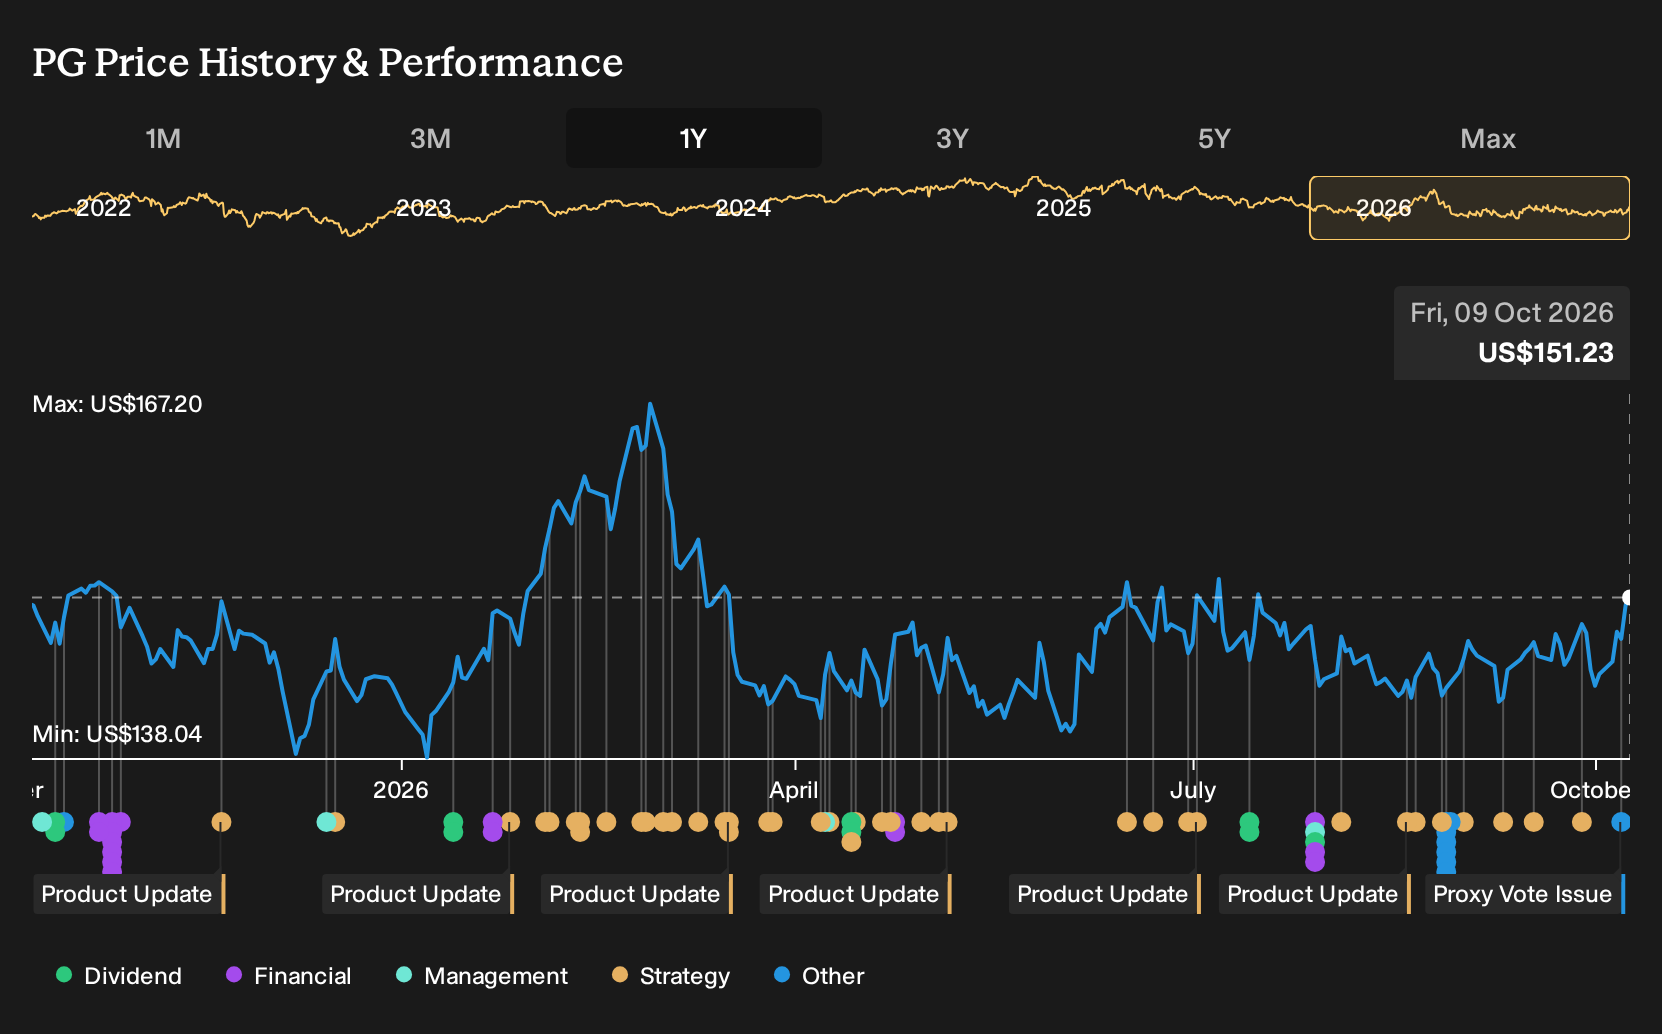
Even within that shared framework, views differ. The consensus price target of US$160.61 sits only 8.9% above the current US$146.39 share price. The spread between US$143.0 at the low end and US$186.0 at the high end underlines that not every analyst is comfortable with the same combination of growth, margin and P/E. Your task is to decide where in that range your own conviction sits, given what you think about input costs, trade inventories and Procter & Gamble's ability to keep refreshing its brands.
Procter & Gamble's narrative projects US$94.5b revenue and US$18.2b earnings by 2029. On these forecasts, revenue would grow by 2.8% per year and earnings would rise by about US$2.4b from the current US$15.8b level.
Uncover why Procter & Gamble's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community has 17 fair value views on Procter & Gamble, stretching from US$107.52 to almost US$197, so you are looking at a very wide spread of expectations. Set that against ongoing cost headwinds and retailer volatility, and it becomes clear you should compare several viewpoints before fixing your own stance.
Explore 16 other Procter & Gamble fair value estimates, including one that suggests as much as 29% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Procter & Gamble research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Procter & Gamble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Procter & Gamble's overall financial health at a glance.
Looking For More Procter & Gamble Style Ideas?
If the Procter & Gamble story appeals to you but you want a broader watchlist, the Simply Wall St Screener can help you line up other candidates that match your risk tolerance and return goals.
- For investors who care most about resilient balance sheets and solid fundamentals, a list of solid balance sheet and fundamentals (25 results) can help you focus on businesses that may better handle tough conditions.
- If you are hunting for mispriced quality, use the screener featuring 29 high quality undervalued stocks to find companies where fundamentals and current pricing appear out of sync.
- Income focused investors can target sturdier payout profiles by scanning a curated set of 8 dividend fortresses that might complement a Procter & Gamble style holding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com