
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Novanta (NOVT) Stock Looks Priced For Perfection After A 41% Run
Novanta shares have climbed strongly over the past year, which puts a spotlight on whether that move is backed up by the earnings power of the business. With the stock now trading around recent levels after a softer few weeks, the key issue is how much of its profit profile is already reflected in the current price.
- The stock has returned 41.3% over the past year, which raises the question of how much future earnings strength investors are already paying for.
- The company relies on turning niche photonics and precision motion technologies into consistent profits, so the durability of those earnings streams can influence how investors judge today's valuation.
- The analysts covering Novanta have run their own numbers. See what analysts think Novanta's shares could be worth.
For investors, the debate is whether Novanta's current share price is reasonably aligned with what its earnings suggest the business is worth.
If you want to test the same earnings question you are asking of Novanta across a broader field, scan through the 29 high quality undervalued stocks.
Has Novanta Run Too Far on Earnings?
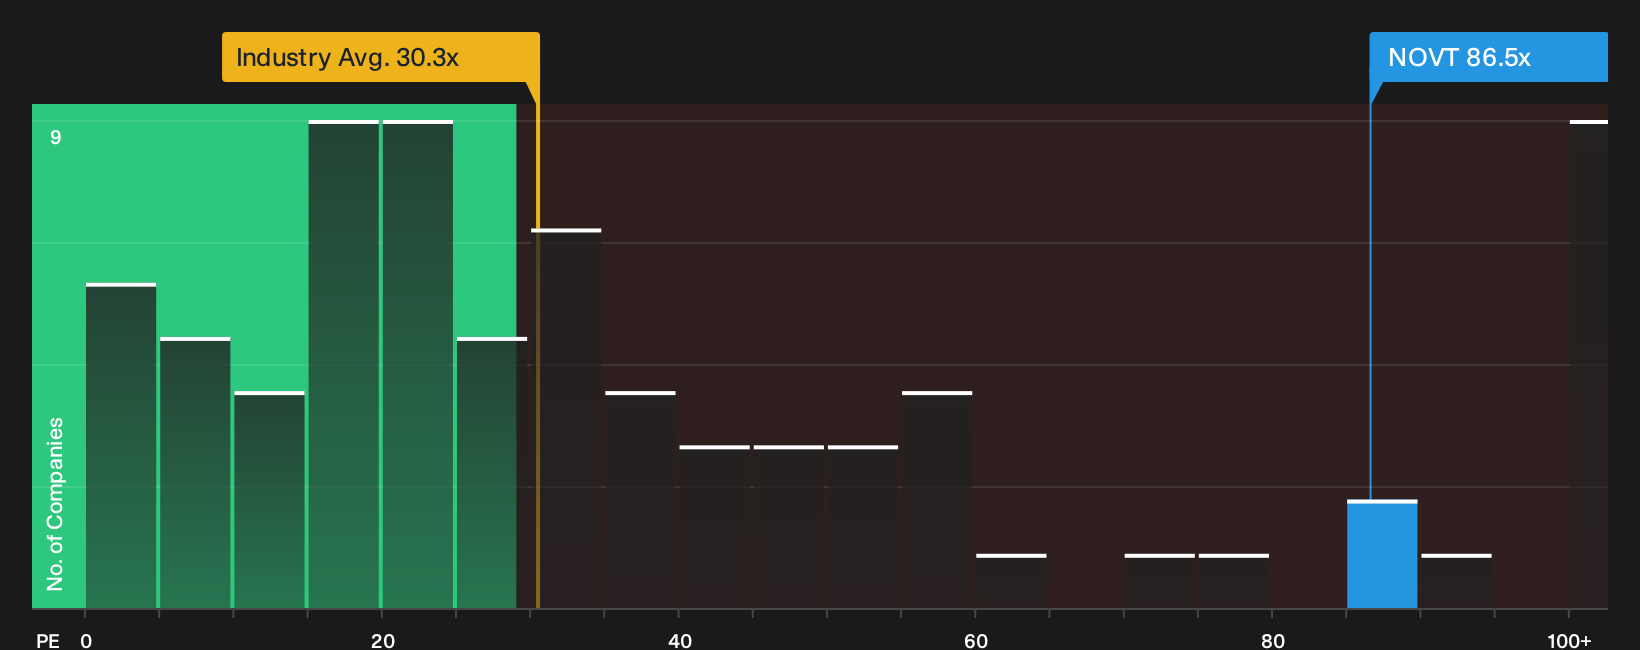
The P/E ratio fits Novanta because earnings sit at the center of how investors judge a specialist industrial technology business. Right now the stock trades on roughly 86.5x earnings, which is far above the Electronic industry average of about 30.3x and also meaningfully higher than peers around 55.4x. That is a rich headline number for any investor to accept.
The fair multiple implied by the model, which blends factors like Novanta's margins, expected cash generation and sector risks, comes in materially lower than where the shares trade today. This gap points to a market price that reflects a high level of confidence in the durability of the current profit engine as well as the potential runway for future earnings. Anyone considering the stock needs to judge whether those business qualities justify paying such a premium P/E tag compared with both the sector and that tailored benchmark. Explore the numbers behind Novanta's P/E valuation.
The Novanta Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E debate leaves off and explain what would need to happen to Novanta's growth, margins and earnings for the share price to look materially higher or lower than it does today. They sit on Simply Wall St's Community page. Rather than relying on a single multiple or one model output, each narrative presents its own set of fair value assumptions so you can compare those inputs with Novanta's reported results over time.
One of the top community narratives on Novanta: 27% undervalued
"The main requirement for this scenario is successful execution on the Riverpoint Medical integration and the broader manufacturing consolidation program…"
Discover why this Narrative puts Novanta at 27% undervalued.
Before you focus on Novanta’s valuation, check what else the numbers are hinting at
Price tags only tell part of the story, and Novanta’s recent track record has triggered a separate set of risk checks that deserve your attention before you lean too heavily on any valuation output. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com