
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why MedinCell (ENXTPA:MEDCL) Is Up 16.9% And What's Next After FDA Approval
- MedinCell announced that WELTRUZA, a once monthly long acting injectable olanzapine using its BEPO technology and partnered with Teva, received U.S. FDA approval for the treatment of schizophrenia, supported by late stage SOLARIS trial data and coming ahead of a planned U.S. launch and ongoing European review.
- The approval deepens MedinCell's royalty based relationship with Teva and highlights commercial and regulatory execution on long acting injectables. This could influence how investors assess dependence on a small product set, patent duration and the scalability of the BEPO platform across future programs.
- This development raises the question of how MedinCell's investment narrative could shift given FDA approval of WELTRUZA using its BEPO platform.
Scan how the WELTRUZA approval fits into a broader opportunity set by reviewing hand picked 618 high quality undiscovered gems with strong fundamentals that the market may not be fully pricing yet.
MedinCell Investment Narrative Recap
To own MedinCell, you need to believe the BEPO platform can support a portfolio of long acting injectables, not just UZEDY and WELTRUZA. The recent FDA green light for WELTRUZA directly addresses a key near term catalyst around regulatory execution for olanzapine LAI and validates Teva as a commercial partner, but it does not remove execution risk.
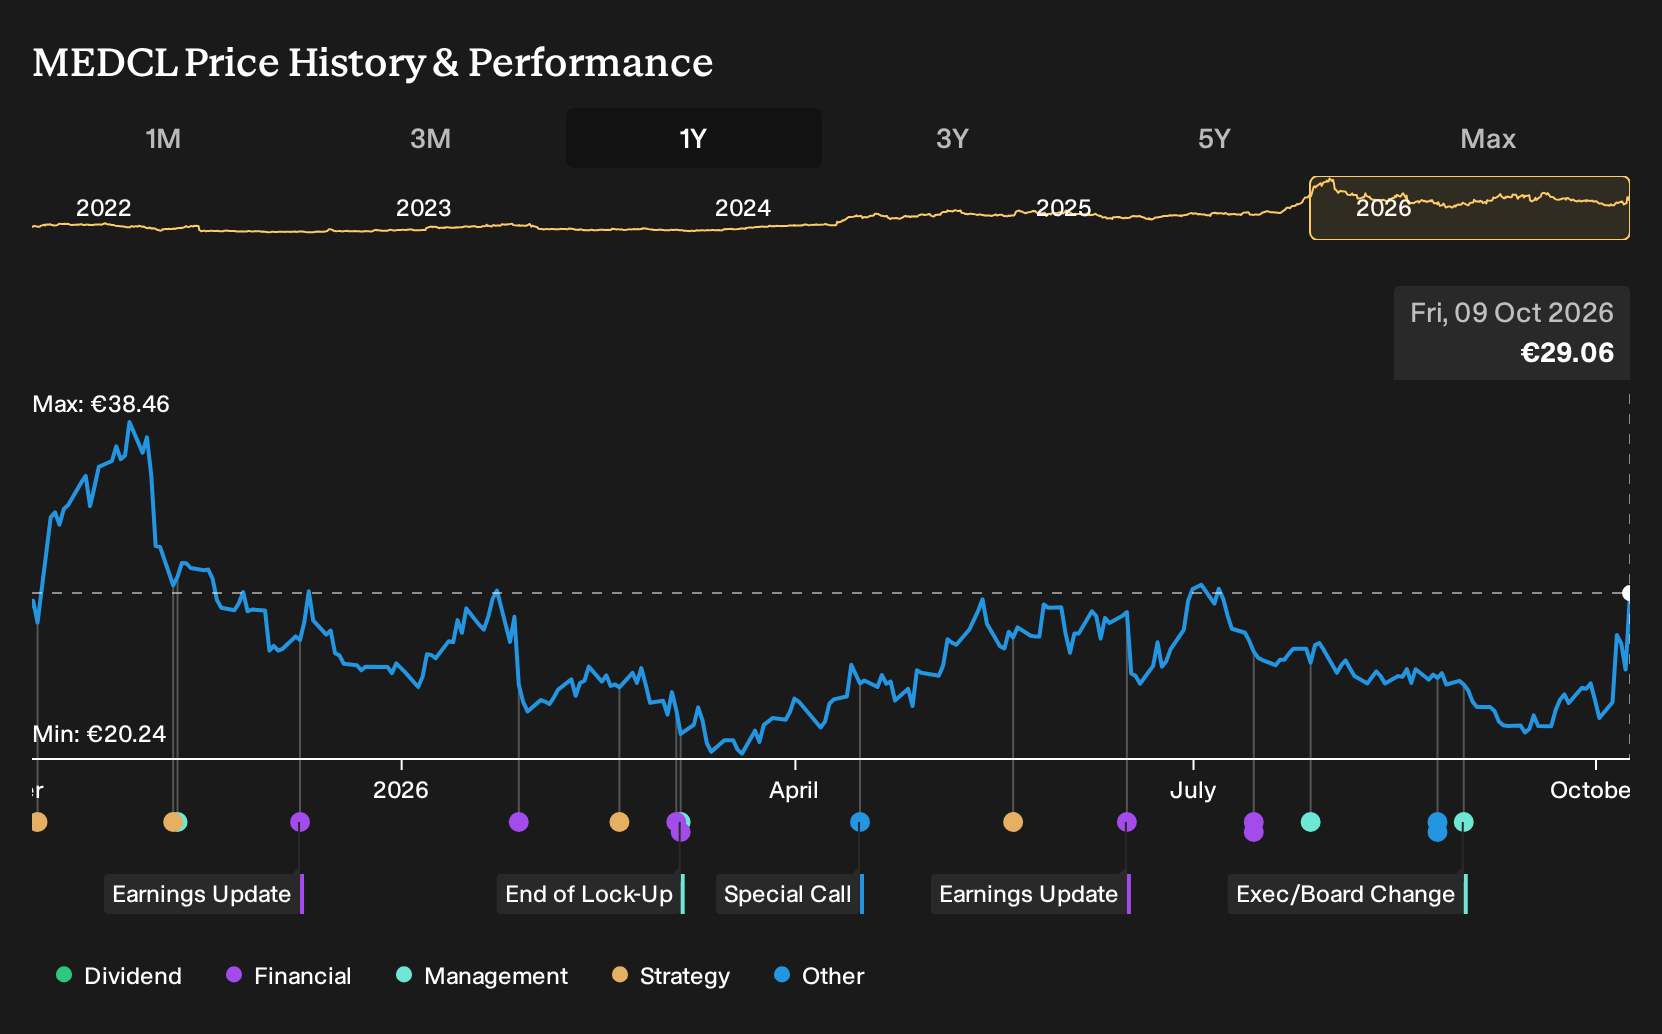
The sharp share price reaction and trading suspension on 9 October 2026 underline how tightly sentiment is tied to single product events. The biggest near term risk stays the same for investors: continued reliance on a very small product base and on future regulatory and partner milestones to fund an expanding pipeline.
The most relevant fresh development around this news is MedinCell scheduling a special call on 9 October 2026 to discuss the implications of the FDA approval of WELTRUZA. That call is likely to focus on how management sees the royalty ramp, launch timing with Teva, and any change in priorities for capital allocation across the pipeline.
For you as a shareholder or potential shareholder, that update matters because it can clarify practical questions around catalysts, such as the expected pace of the Q4 2026 U.S. launch and any read across to ongoing European review. It also gives a chance to hear how leadership weighs new WELTRUZA cash flows against risks like dependence on milestone income and a still loss making profile.
MedinCell's narrative projects €85.7 million revenue and €39.7 million earnings by 2029. This implies 38.2% yearly revenue growth and an earnings swing of roughly €59.6 million, from a loss of €19.9 million today to the forecast consensus earnings level.
Uncover why MedinCell's fair value indicates a 21% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate take on MedinCell leans heavily on the risk that higher R&D spending, already up 22% with a €6.6 million operating loss, keeps profitability distant. Those more cautious analysts were only modeling about €84.5 million of revenue and €19.6 million of earnings by 2029. The fresh WELTRUZA approval could push that story to evolve, so treat this as a moment to compare several viewpoints rather than anchor to a single forecast.
Explore another MedinCell fair value estimate, including one that suggests it could be worth just €35.07.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MedinCell research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MedinCell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MedinCell's overall financial health at a glance.
Looking For More Investment Ideas Beyond MedinCell?
If the MedinCell story has sharpened your thinking about risk, balance sheets, and long term earnings potential, it can help to compare that against a wider set of businesses using the Simply Wall St Screener.
- Prioritise financial resilience and focus on companies with sturdier funding profiles by reviewing our list of solid balance sheet and fundamentals (204 results) that already clear a fundamentals screen.
- If capital preservation matters most to you, scan a 223 resilient stocks with low risk scores that aims to keep volatility and risk scores in check.
- Prefer mispriced quality and want ideas beyond MedinCell? Then run through a 178 high quality undervalued stocks where strong fundamentals and discounted prices intersect.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com