
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bitmine Immersion Technologies (BMNR) Stock May Stay Reasonable As AI Crypto Interest Grows
Bitmine Immersion Technologies has delivered a striking 3 year share price swing, yet the real debate is whether that performance lines up with what its balance sheet is actually worth on paper. With fresh attention on the business after renewed crypto and AI commentary, the key issue for you is how today’s stock price stacks up against its book value.
- Over the past 3 years, Bitmine Immersion Technologies has gained about 99.6%, which makes the current valuation question far more sensitive to what its underlying equity base can realistically support.
- Recent commentary around the company’s role in AI driven crypto infrastructure highlights potential shifts in capital intensity and earnings power, which can directly affect how much weight investors put on its net assets per share.
- There is a second opinion on Bitmine Immersion Technologies worth weighing. See what analysts think Bitmine Immersion Technologies's shares could be worth.
The issue now is whether Bitmine Immersion Technologies' current share price is adequately supported by its book value when compared with the broader industry average.
If you want more context around Bitmine Immersion Technologies and the AI driven crypto theme, it helps to compare it with other 20 cryptocurrency and blockchain stocks.
Is Bitmine Immersion Technologies Still Cheap on Book Value?
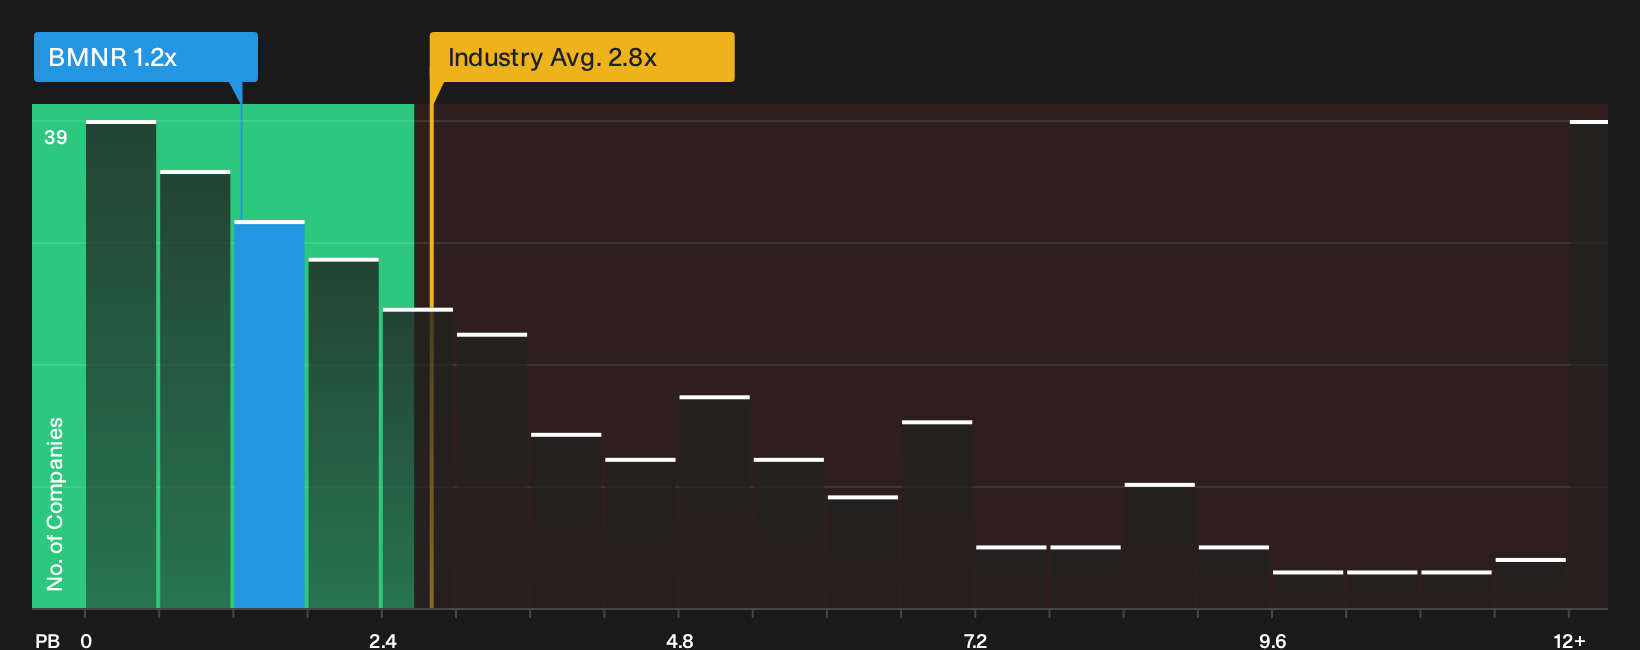
P/B fits Bitmine Immersion Technologies because the story hinges on the assets backing its mining and infrastructure footprint rather than current earnings. The stock trades on a P/B of about 1.2x, which is well below the Software industry average of roughly 2.8x and also under the broader peer group around 7.0x. That gap means the market is currently paying a smaller premium over Bitmine Immersion Technologies' net assets than it is for many software oriented businesses.
Because Tom Lee’s AI driven crypto view has pulled Bitmine Immersion Technologies into the spotlight, the valuation discount on P/B suggests sentiment has not fully translated into a rich price relative to the balance sheet. For you as a shareholder or potential investor, the key question is whether the assets and capital base can earn enough over time to justify even an industry level P/B, or whether the lower multiple simply reflects the risks built into this crypto infrastructure model. Explore the numbers behind Bitmine Immersion Technologies's P/B valuation.
The Bitmine Immersion Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/B discussion leaves off and explain which combinations of Bitmine Immersion Technologies' growth, margins and earnings would need to occur for today's valuation to appear stretched or conservative. Each scenario links a grounded fair value estimate to a particular mix of potential catalysts and risks, allowing you to track over time which version of the story Bitmine Immersion Technologies' actual results seem to reflect.
A clear, number driven narrative on Bitmine Immersion Technologies gives you a way to pin Tom Lee’s AI crypto thesis to specific assumptions on assets, returns and dilution that can later be checked against actual filings. It turns a broad story about AI powered crypto infrastructure into a set of trackable expectations for how Bitmine Immersion Technologies' balance sheet and business model might respond if that outlook gains traction or fades.
Share your own Narrative for Bitmine Immersion Technologies and set out the assumptions behind your valuation.
One last angle for Bitmine Immersion Technologies before you log off
Before you stop at the balance sheet and valuation ratios, it pays to look at who is steering Bitmine Immersion Technologies and how the incentive plan nudges their decisions over the next few years. See who runs Bitmine Immersion Technologies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com