
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Moderna (MRNA) Priced Above Fair Value After Its 7x Run?
Moderna has delivered a very strong run over the past year, which now puts the focus squarely on whether the current share price is properly supported by its sales base. With the stock rebounding into the spotlight again, the question for you is how much revenue power the market is effectively pricing in today.
- The share price is up about 7x over the past year, so recent buyers are taking a clear view on what Moderna's future sales profile could look like.
- Management is expanding manufacturing capacity for mRNA therapeutics and vaccines and advancing oncology programs, which can influence how investors think about long term revenue potential and the scale of sales needed to support the current valuation.
- There is a second opinion on Moderna worth weighing. See what analysts think Moderna's shares could be worth.
For investors, the debate is whether Moderna's current market value is reasonable once you line it up against the sales the business is generating today and is realistically positioned to deliver.
If you are considering whether Moderna's sharp rerating on its sales base appears stretched, it may be helpful to compare that question across 30 high quality undervalued stocks.
Is Moderna Getting Expensive on Sales?
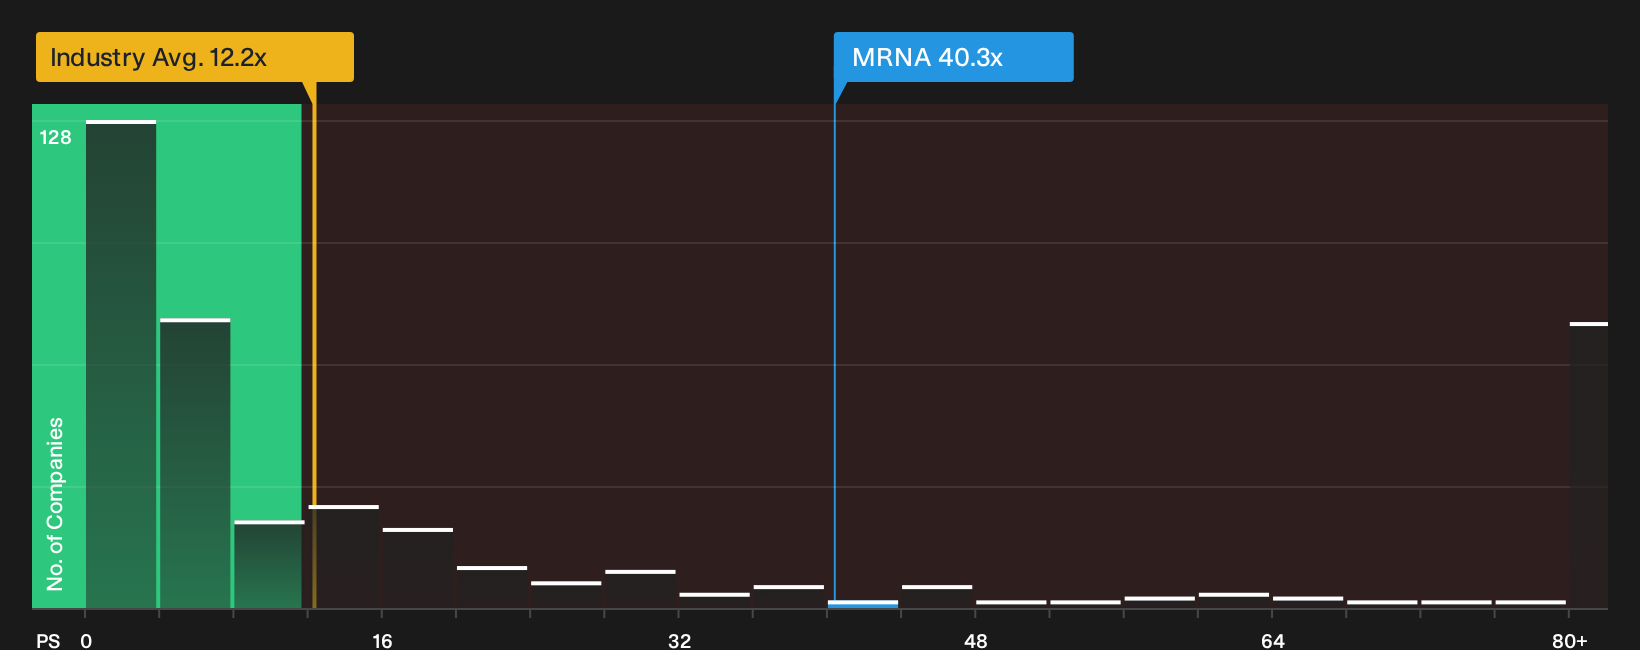
P/S is a useful lens for Moderna because the business is still loss making and investors are effectively paying for revenue plus the pipeline story behind it. On this measure, the stock trades on a P/S of about 40.3x, which is far above the biotech industry average of 12.2x and also well ahead of the peer group around 7.4x.
The fair multiple implied by Simply Wall St's model takes into account Moderna's growth profile, margins, size and risk, and places the current P/S well above where that framework would usually expect it to trade. That gap is very wide, so the output reads more as a signal that the shares screen as expensive on sales than as a precise fair value target. Despite the recent downgrade that questioned whether oncology sales assumptions are too rich, the market is still assigning a premium P/S that already bakes in a lot of revenue ambition. Explore the numbers behind Moderna's P/S valuation.
The Moderna Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Moderna pick up where the valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully underpriced or overpriced relative to today’s market value. Rather than providing a single output from a ratio or model, they map the range of business outcomes that number relies on, so you can watch over time whether Moderna's actual progress lines up with the story implied by the current price.
One of the top community narratives on Moderna: 83% overvalued
"Slowing vaccine sales, higher competition, cost cuts, regulatory pressures, and limited capital flexibility threaten Moderna's revenue stability and long-term earnings growth..."
Discover why this Narrative puts Moderna at 83% overvalued.
One more Moderna check that belongs beside the price tag
Before you stop at the P/S and narrative debate, it is worth seeing what the broader risk checks are quietly flagging about Moderna and weighing those signals alongside the valuation story. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com