
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Walmart (WMT) Stock Still Seems Expensive Despite Fulfillment Center Expansion
Walmart shares have climbed to about US$111 after years of strong gains, which raises a simple question for anyone looking at the stock today: Is the current valuation still grounded in the retailer's earnings power, or has the price run ahead of what the business is generating?
- Over the past 5 years the stock has returned 153.0%, putting a lot of weight on the idea that the retail giant's earnings can support a much larger equity value than before.
- Recent moves to automate warehouses, expand fulfillment centers and grow higher margin services like advertising can reshape Walmart's cost base and profit mix. This matters for how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Walmart worth weighing. See what analysts think Walmart's shares could be worth.
The issue now is whether Walmart's recent share price, after that multi year run and ongoing investment program, is justified by the earnings the company produces today and is expected to produce over time.
If you are weighing Walmart on its earnings today, it can help to compare that view with a wider set of retailers and platforms screened on solid balance sheet and fundamentals stocks screener (25 results).
Is Walmart Getting Expensive on Earnings?
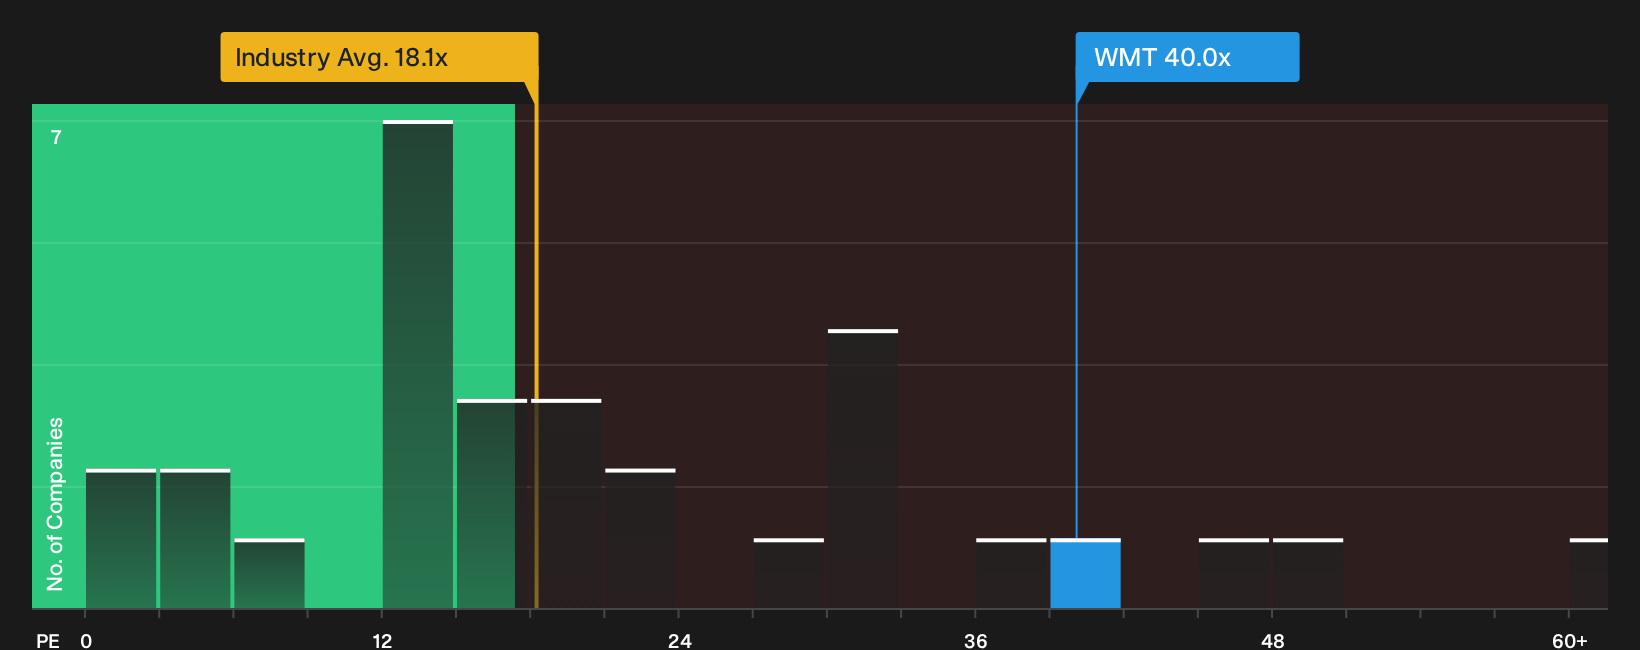
The P/E ratio is a useful yardstick for Walmart because earnings remain the main anchor for how investors frame its value. At roughly 40.0x, Walmart trades well above the broader consumer retailing industry on about 18.1x and ahead of its direct peer set near 22.9x. That points to investors assigning a sizeable premium to each dollar of profit at the retailer compared with many other listed chains.
On this framework, the fair P/E that would typically line up with Walmart's size, sector, profitability profile and risk sits below the current 40.0x. This flags the stock as overvalued on this metric alone. Recent enthusiasm around initiatives like Walmart Connect and warehouse automation helps explain why the market is comfortable paying far more than the sector average for earnings. However, the present multiple already reflects a lot of optimism about what those efforts can contribute to future profit streams. Explore the numbers behind Walmart's P/E valuation.
The Walmart Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Walmart aim to close the gap between that rich P/E and the actual business by explaining what would need to happen to future growth, margins, and earnings for the stock to be worth materially more or less than it is today. Each narrative treats fair value as a thesis you can track over time rather than a single snapshot, and all are hosted on Walmart's Community page.
One of the top community narratives on Walmart: 12% undervalued
"The main factor that has to go right is the continued growth and profitability of higher margin alternative profit pools such as advertising…"
Discover why this Narrative puts Walmart at 12% undervalued.
One more Walmart check that sits beside the P/E comparison
Price tells you what the market thinks today, but the projections that analysts publish for Walmart over the next few years offer a different lens on whether that view lines up with expected earnings power. Explore where analysts expect Walmart to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com