
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will West County Loan Refinance Change CBL Properties Stock Narrative
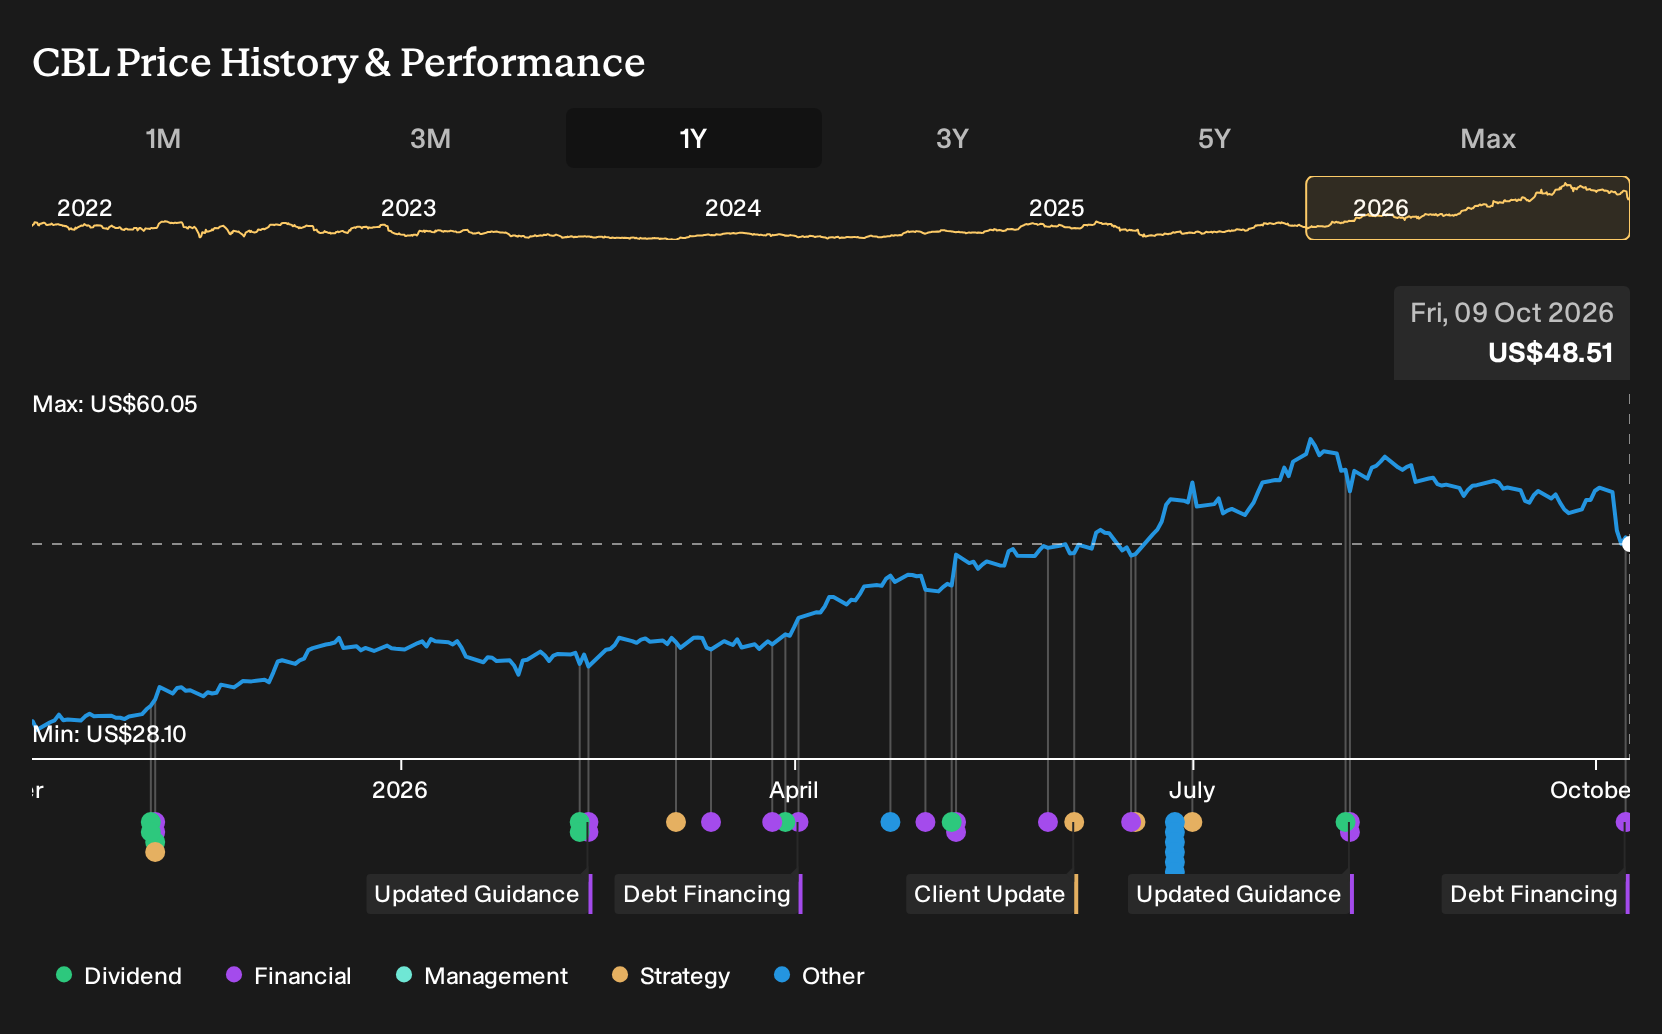
- CBL & Associates Properties recently refinanced the US$135 million mortgage on West County Center in St. Louis with a new five-year, 7.4% fixed-rate, non-recourse loan. This replaced a prior facility that was due in December 2026 and generated about US$2 million in net proceeds.
- The mall owner also closed a related US$22.5 million Community Improvement District bond refinancing that provided cash for both debt repayment and targeted upgrades, including security cameras, escalators, lighting and parking improvements at West County Center.
- Attention now turns to how CBL & Associates Properties' extended debt runway from this refinancing could influence its broader investment narrative.
Scan how CBL & Associates Properties' refinancing story compares with peers by checking a curated set of real estate plays screened as 30 high quality undervalued stocks.
What Is CBL & Associates Properties' Investment Narrative?
For CBL & Associates Properties, the big picture is simple. You need to believe this is a mall landlord that can keep its 85 property portfolio relevant enough to support rent levels, cover interest and still fund heavy upkeep on large enclosed centers. The West County refinancing fits that thesis because it pushes out the last near term maturity and removes a cash sweep, which management expects to convert into an estimated US$7 million of extra yearly free cash flow. That helps near term execution, but it does not change how capital hungry large malls are or how dependent the business remains on steady tenant demand and pricing.
The short term story now leans on a few levers. CBL & Associates Properties has been posting strong recent earnings growth and trades on a P/E of 7x, yet forecasts call for earnings to decline on a multi year view and interest costs are described as not well covered by profits. The West County package and related US$22.5 million bond refinancing add some breathing room and earmark US$2.6 million for on site projects, which may support that asset, but they do not resolve questions around one off gains, higher risk funding and how sustainable the recent jump in profitability really is.
Even so, there is a specific pressure point in this story that could matter far more than the West County win...
There's only one way to know the right time to buy, sell or hold CBL & Associates Properties. Head to Simply Wall St's company report for the latest analysis of CBL & Associates Properties's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$42.95 to US$63 per share for CBL & Associates Properties, which shows how far apart private investors can be. Those estimates pre date the October refinancing, so you are comparing older models with a fresh debt profile. Use that gap to explore several contrasting viewpoints.
Explore another CBL & Associates Properties fair value estimate, including one that suggests potential upside of as much as 30% from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CBL & Associates Properties research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for CBL & Associates Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CBL & Associates Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond CBL & Associates Properties?
If you want to stress test your view on CBL & Associates Properties, compare it with other potential opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you focus on financial strength first.
- If preserving capital is your priority and you want businesses with lower risk scores, narrow your search using a 31 resilient stocks with low risk scores and see which stocks fit a more defensive playbook.
- To broaden your watchlist with underfollowed ideas that still show strong fundamentals, scan a 20 high quality undiscovered gems that highlights lesser known opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com