
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Australian Undervalued Stocks Trading Up To 36% Below Fair Value
Australian investors are watching global bond markets closely as US 10 year Treasury yields sit near a 24 year high, pushing up borrowing costs and pressuring richly priced shares. When money becomes more expensive, dependable cash flows often matter more than distant promises. This article looks at three Australian stocks that screen as attractively priced on their cash generation, helping you focus on value where the numbers still work.
The three stocks below are a sample pulled from a wider filter of cash generative businesses. The full screen surfaced 6 more companies with similarly grounded stories that are not covered here. If you want to go straight to the source and identify your own high conviction ideas, head into the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper miner. Its Havieron project drives its inclusion in this cash flow focused screen, because that ore body is expected to underpin the long term production profile and future discounted cash flows investors are weighing today.
Greatland Resources generates A$2.26b from its Telfer Havieron segment and has a market value of about A$6.80b, so the flagship Western Australian gold copper operation and its projected cash flows dominate both current earnings and the valuation case.
For this list, Greatland Resources matters because the Havieron project links current production to a clear source of potential future cash flows. This is exactly what this discounted cash flow screen is trying to spotlight for investors hunting for value grounded in hard numbers.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What really moves the needle for Greatland Resources is how one still developing piece of the Havieron puzzle ultimately feeds through to future margins.
That hinge point on margins is exactly what the full narrative for Greatland Resources unpacks, showing how Havieron’s cash flow profile could accelerate or stall the Greatland Resources story.
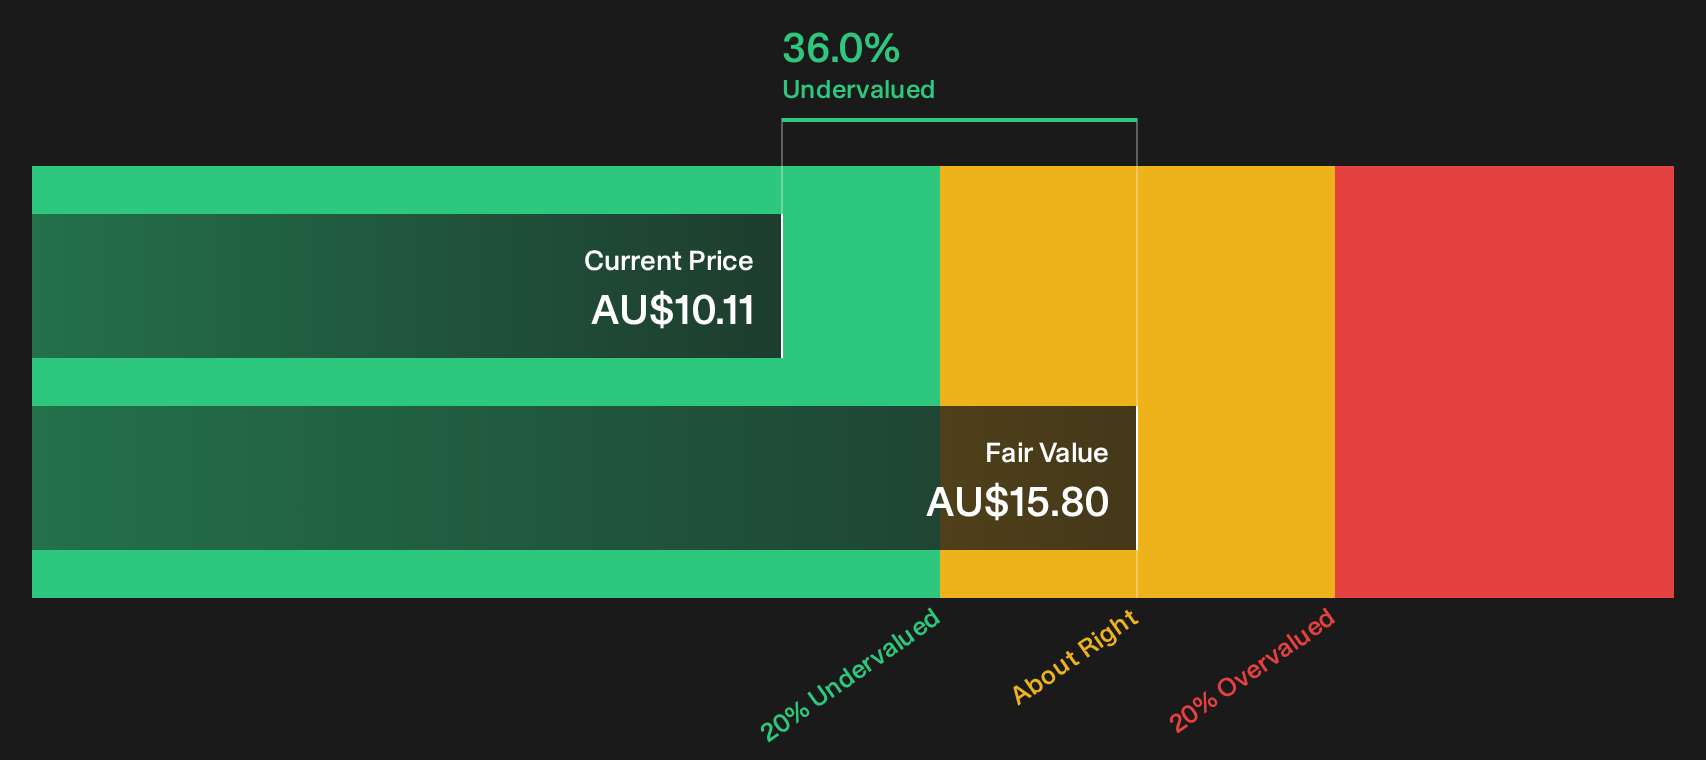
Ansell (ASX:ANN)
Ansell brings the screener theme to life through its Healthcare division, where high margin surgical and examination gloves generate recurring cash flows that feed directly into discounted cash flow value. The rest of the portfolio adds breadth, but those consumables do the heavy lifting.
Ansell designs and sells protective gloves and clothing worldwide, with Healthcare generating about US$1.2b and Industrial around US$947 million in revenue, and the group valued at roughly A$6.3b by the market.
"Ansell is positioned to capture increased structural demand in PPE, supported by tightening workplace-safety regulation, rising healthcare and hygiene standards, and ongoing industrialisation in emerging markets."
What matters now is how one quiet shift in its glove economics filters through to future cash flows that investors are valuing today.
Those shifting glove economics are exactly what the full narrative for Ansell lays out, separating short term noise from the long term cash engine that investors care about.

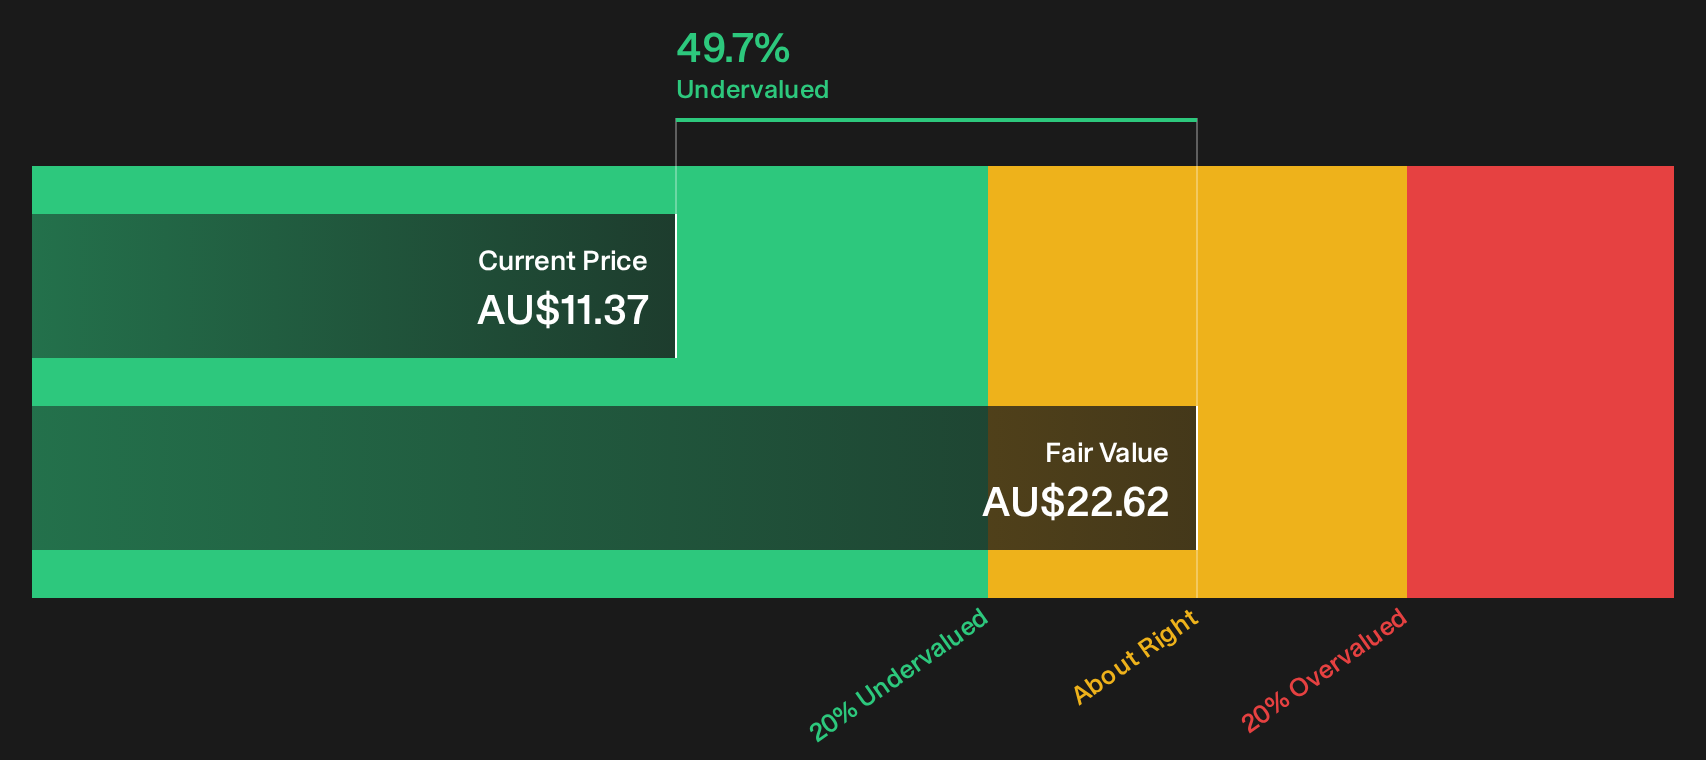
Origin Energy (ASX:ORG)
Origin Energy plays directly into this cash flow focused screen through its mix of gas production, electricity generation and energy retailing, where large utility style operations can turn long term customer demand into steady money coming through the door.
Origin Energy runs an integrated energy platform across gas fields, power generation and retail supply, with A$15.26b from Energy Markets and A$307 million from Integrated Gas, giving it a broad earnings base, and the group is valued at about A$19.5b.
"Capital-heavy investments in renewables, storage, and international software platforms (Kraken/Octopus) are being valued as sources of near-term EBITDA growth. However, these ventures may face execution risks and cost overruns, which could compress return on capital and drag on future earnings."
For investors weighing Origin Energy’s cash flow story, a shift in how future retail margins evolve could matter far more than headline growth targets.
Those future retail margins are exactly what the full narrative for Origin Energy unpacks, showing where Origin Energy’s cash generation could accelerate, stall, or quietly decouple from headline sentiment.
Seeking Fresh Alternatives Beyond These Three
Fresh ideas often move first. By the time a breakout is obvious, early momentum has already passed. Review these under the radar lists before the crowd catches up and consider your options promptly.
- Target steadier compounding potential through companies built on strong cash cushions and clean balance sheets with the curated list of solid balance sheet and fundamentals (12 results) while they are still ignored.
- Focus on income that may influence your total return using a tight pool of hand picked 6 dividend fortresses before yields change and the most attractive entries are no longer available.
- Explore potential future growth stories at the leading edge of computing with curated 25 quantum computing stocks before shifts in quantum-related sentiment alter early valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com