
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Eton Pharmaceuticals (ETON) Launches IMPAVIDO, Is The Stock Still Undervalued?
Eton Pharmaceuticals (ETON) has introduced IMPAVIDO, an oral miltefosine treatment for several forms of leishmaniasis, expanding its rare disease portfolio and giving investors a fresh data point to assess its revenue potential.
Recent trading shows how quickly sentiment around Eton Pharmaceuticals has shifted. The share price is at US$55.21, with a 90-day share price return of 50.81% and a year-to-date share price gain of 239.54%. The 1-year total shareholder return of 180.82%, along with very large 3-year and 5-year total shareholder returns, suggests long-running momentum. The IMPAVIDO launch now feeds into this as another potential driver of expectations around future revenue and risk.
Spot opportunities around Eton Pharmaceuticals by scanning our hand-picked 20 high quality undiscovered gems that focus on rare diseases and underfollowed healthcare stories.Eton Pharmaceuticals has already sprinted higher on the IMPAVIDO story, which puts you at a simple crossroads: pay up at today’s price, or wait and risk watching the valuation run further without you.
Most Popular Narrative: 22% Undervalued
Eton Pharmaceuticals is framed as undervalued by the most followed narrative, which pegs fair value at $71 against the last close of $55.21, placing the IMPAVIDO launch within a broader rare disease expansion story.
The company's focus on acquiring and developing therapies aligned with long-term demographic trends such as an aging population and rising prevalence of chronic and rare diseases is presented as providing a robust runway for multi-year revenue and earnings growth, supporting the case that current valuation does not fully reflect Eton's future financial potential.
See why 16 investors see Eton Pharmaceuticals as 22% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the bullish Eton Pharmaceuticals story can crack if key ultra rare products face pricing pressure or if regulatory delays push out pipeline launches.
Find out about the key risks to this Eton Pharmaceuticals narrative.
Another Angle On Eton Pharmaceuticals’ Valuation
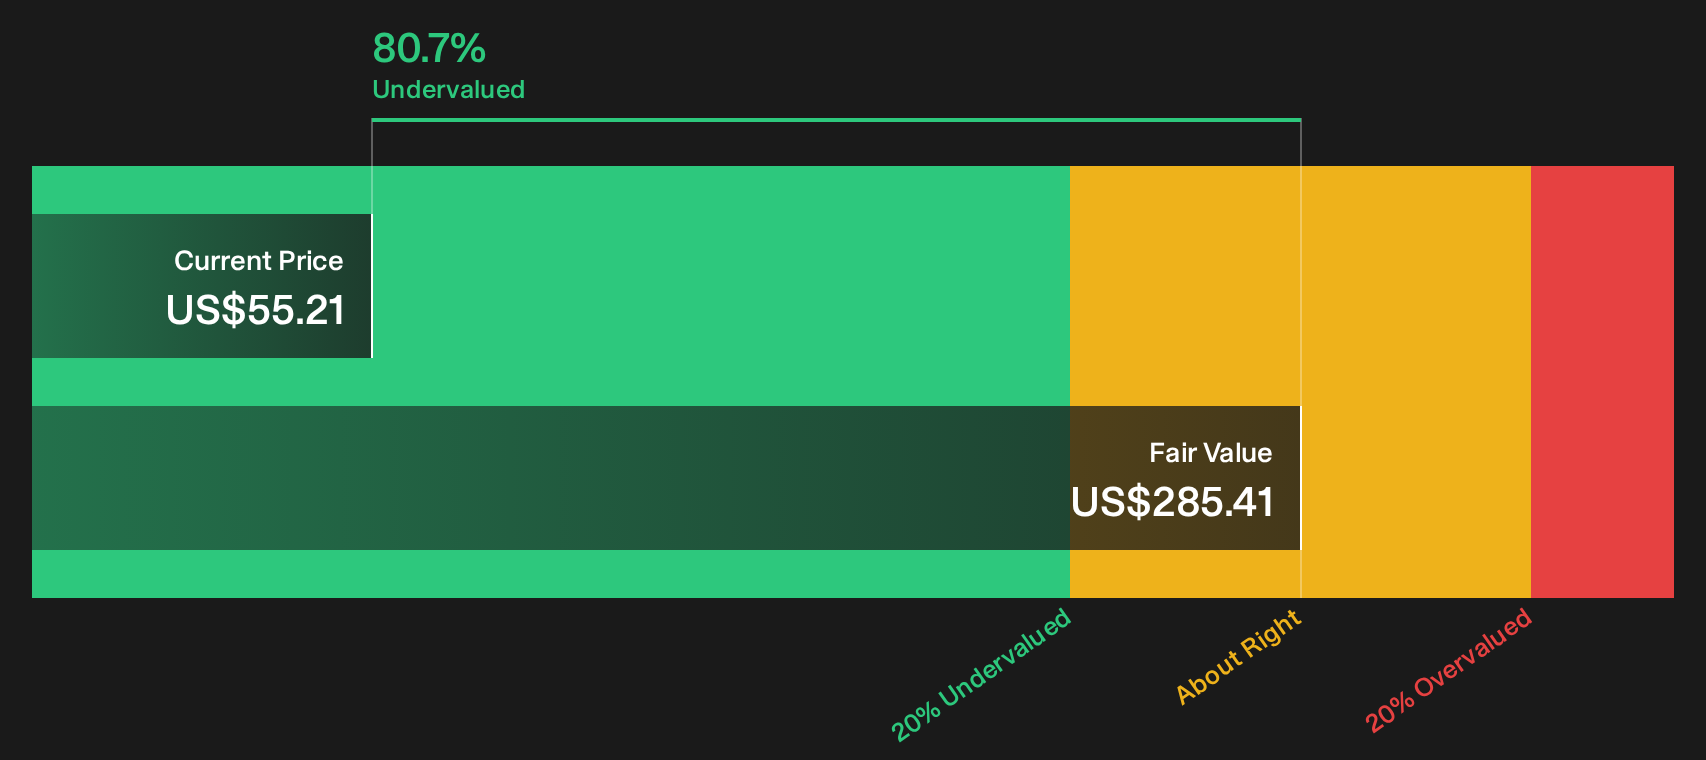
The SWS DCF model presents a very different picture compared with the $71 fair value narrative. On this view, Eton Pharmaceuticals at $55.21 is trading far below an estimated future cash flow value of $285.41, which frames the current quote as cautious rather than stretched. Which perspective do you think is closer to reality?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Big upside case, big questions. If you want to move before sentiment shifts again, weigh both sides of the data yourself by starting with the 4 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Eton Pharmaceuticals?
If Eton Pharmaceuticals has your attention, do not stop here. Fresh ideas often show up where fewer investors are looking and where fundamentals still matter.
- Expand your opportunity set by scanning a curated group of underpriced quality businesses through the 28 high quality undervalued stocks.
- Prioritize resilience and sleep-at-night holdings by filtering for companies with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Tilt your watchlist toward consistency and lower volatility by focusing on companies highlighted in the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com