
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Citigroup's Rally? Here's What Holders Saw
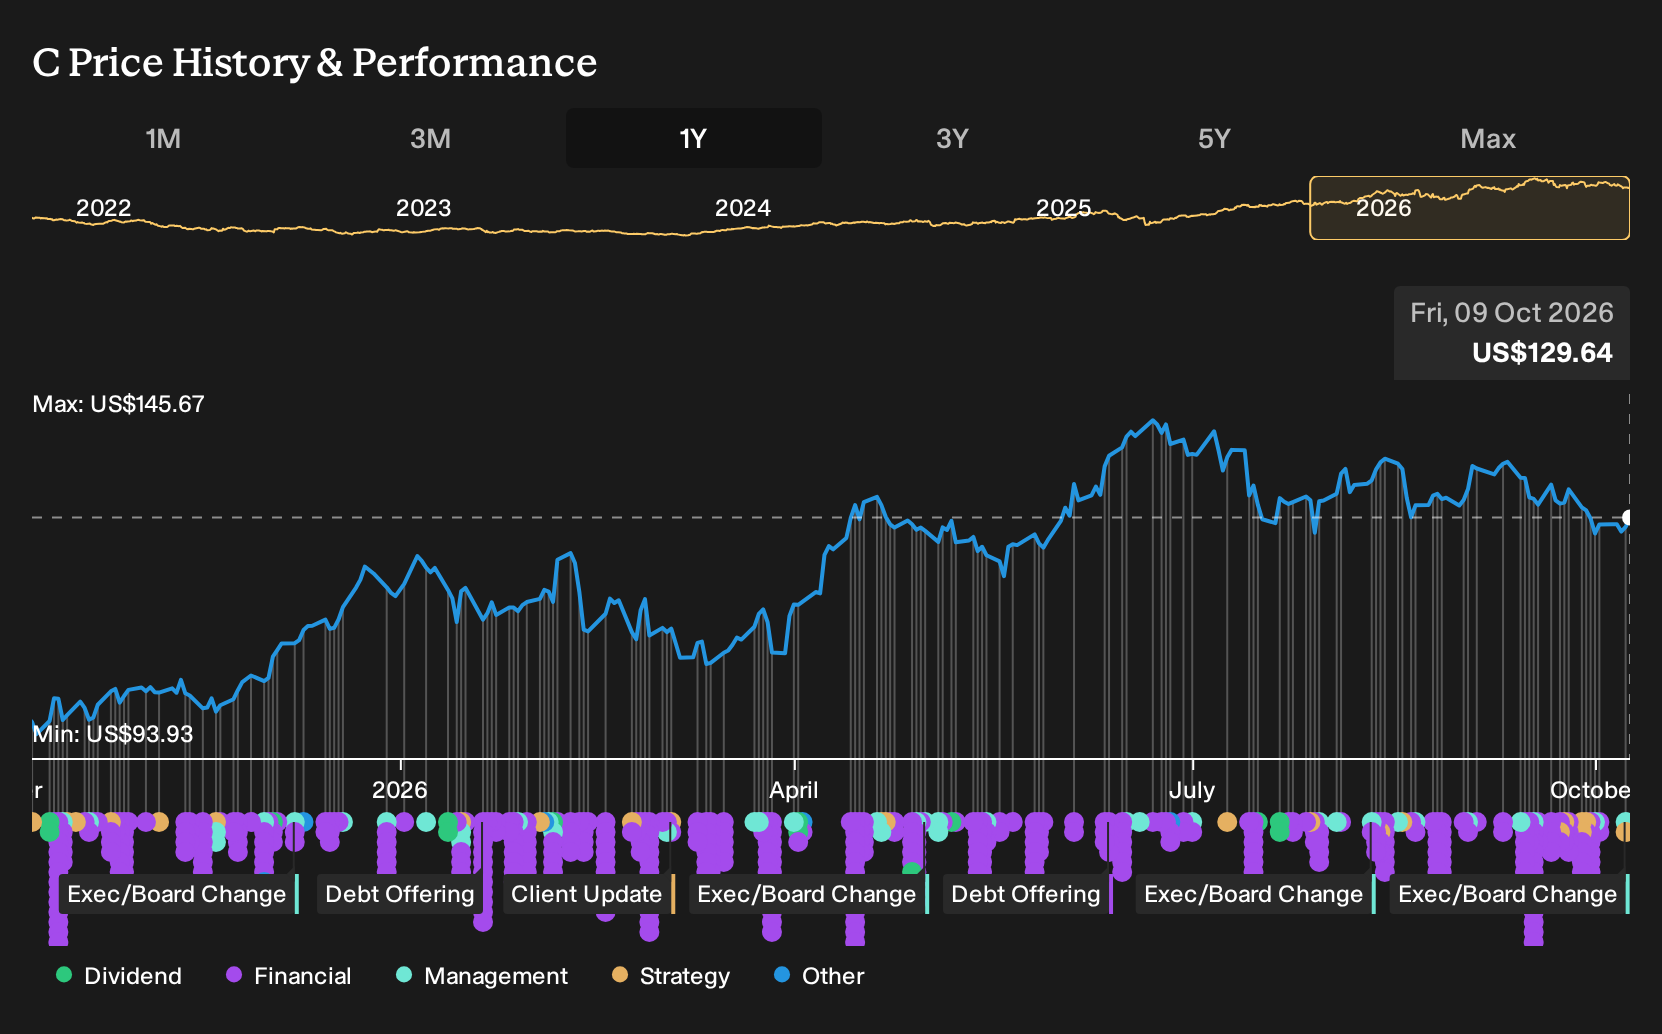
Investors who held Citigroup over the past year are up 40.9%, including dividends. If you had bought on 9 October 2025, you would now be looking back at a year in which bulls pointed to digital transformation, cross border transaction services and wealth growth, while bears focused on heavy restructuring costs and macro risk. Which of those competing stories would have carried more weight for you at the time?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Citigroup is not the only name tied to this theme. Zero in on 20 cryptocurrency and blockchain stocks and compare how each one is priced.
The Two Citigroup Stories Investors Had To Weigh
The shares cost US$95.92 at the start of the period, so anyone looking at Citigroup then had to decide which future felt more realistic.
The bullish narrative put Fair Value at US$103, or 8% above the start price. It relied on assumptions that Citigroup could grow revenue 6.9% a year while sustaining a 19.3% profit margin.
The bearish view pointed to a Fair Value of US$77, or 20% below the start price. It highlighted the risk that heavy transformation and regulatory expenses could keep margins and net earnings under pressure.
What The Results Changed For The Citigroup Case
The clearest development was Citigroup’s Q2 2026 report, which showed revenue at US$22.16b and net income at US$5.45b. Both figures, along with the net margin rising from 19.2% to 24.6% year on year, supported the view that profitability was stronger. Heavier transformation and severance costs still existed, so the evidence pointed in both directions.
The key assumption here was margin resilience. When you review another bank, compare its old and new net margins, then consider whether the business changes that were outlined are actually reflected in that figure.
What Citigroup’s Current Price Is Asking You To Believe
Citigroup now trades at US$130, with this Narrative’s Fair Value figure sitting above that level based on its own framework rather than any proven fact. The argument leans heavily on the global services engine, digital payments work and broad AI use to support productivity and capital returns.
If you pay today’s price, you are effectively judging whether Citigroup can keep turning services growth, AI driven efficiency and a simpler structure into durable double digit returns on tangible common equity without control issues eroding that progress.
"The current valuation implies that the market is not fully crediting Citigroup for its recent 13.1% RoTCE, services and wealth performance, and capital return program, which this narrative views as inconsistent with the underlying franchise position and therefore supportive for the share price."
The price and this Narrative do not agree. → Uncover what this Narrative says Citigroup is actually worth
Looking One Step Beyond Citigroup
You have weighed Citigroup’s services engine and digital push. Now consider what happens when those same clients want more than basic banking.
Large deposit bases and workplace links can create a different opening for another institution. It is working to turn everyday accounts into deeper investment and retirement relationships.
This player is pouring resources into AI tools and digital platforms. The goal is to reduce support friction while steering customers toward higher value advice and products.
If that approach gains traction, your comparison set widens. Citigroup may be only one way to access demand for more connected banking, wealth and cash management.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 24% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com