
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sony Group (TSE:6758) Climbed, What Is Driving Attention Now?
Creator-Focused Audio Launch Puts Sony Group in the Spotlight
Sony Group (TSE:6758) has drawn fresh attention after Sony Electronics unveiled the ECM-AX10, an Eclipsa Audio-certified smartphone microphone positioned for vloggers and mobile filmmakers who are seeking more immersive sound capture.
The device combines four omnidirectional capsules with spatial audio processing and multiple recording modes. This ties into Sony’s broader push across consumer electronics, content creation tools, and software that supports end-to-end production workflows.
Recent trading suggests interest is rebuilding around Sony Group, with a 1-day share price return of 2.91% and a 90-day share price gain of 13.55% following the ECM-AX10 launch and a sizeable buyback that retired 1.26% of shares. This comes even as the year-to-date share price return is down 6.5% and the 1-year total shareholder return has declined 13.76%, while the 3-year and 5-year total shareholder returns of 58.98% and 60.57% point to a stronger longer-run record.
Scan creator-focused hardware beyond Sony Group by checking a curated set of 91 robotics and automation stocks aligned with automation, imaging and next-gen production workflows.
The rebound in Sony Group now sits between two stories: a business still investing across games, music and creator hardware, and sentiment swinging back after a weaker year. Which one explains more of this move, and what does the price assume next?
Most Popular Narrative: 21% Undervalued
Sony Group's most followed valuation narrative points to a fair value of ¥4,845 per share, which sits well above the last close around ¥3,814. This frames the recent share price rebound as only a partial catch up to underlying earnings power and asset mix.
The current valuation implies the share price does not fully reflect Sony Group’s higher earnings guidance, strong performance in Music and image sensors, and the long term potential of its digital PlayStation ecosystem and cross segment IP strategy.
See why 44 investors see Sony Group as 21% undervalued.
Result: Fair Value of ¥4,845 (UNDERVALUED)
Still, if legal disputes around digital ownership or higher hardware and component costs flare up again, the bullish Sony Group narrative could come under pressure.
Find out about the key risks to this Sony Group narrative.
Another View: Sony Group Through The P/E Lens
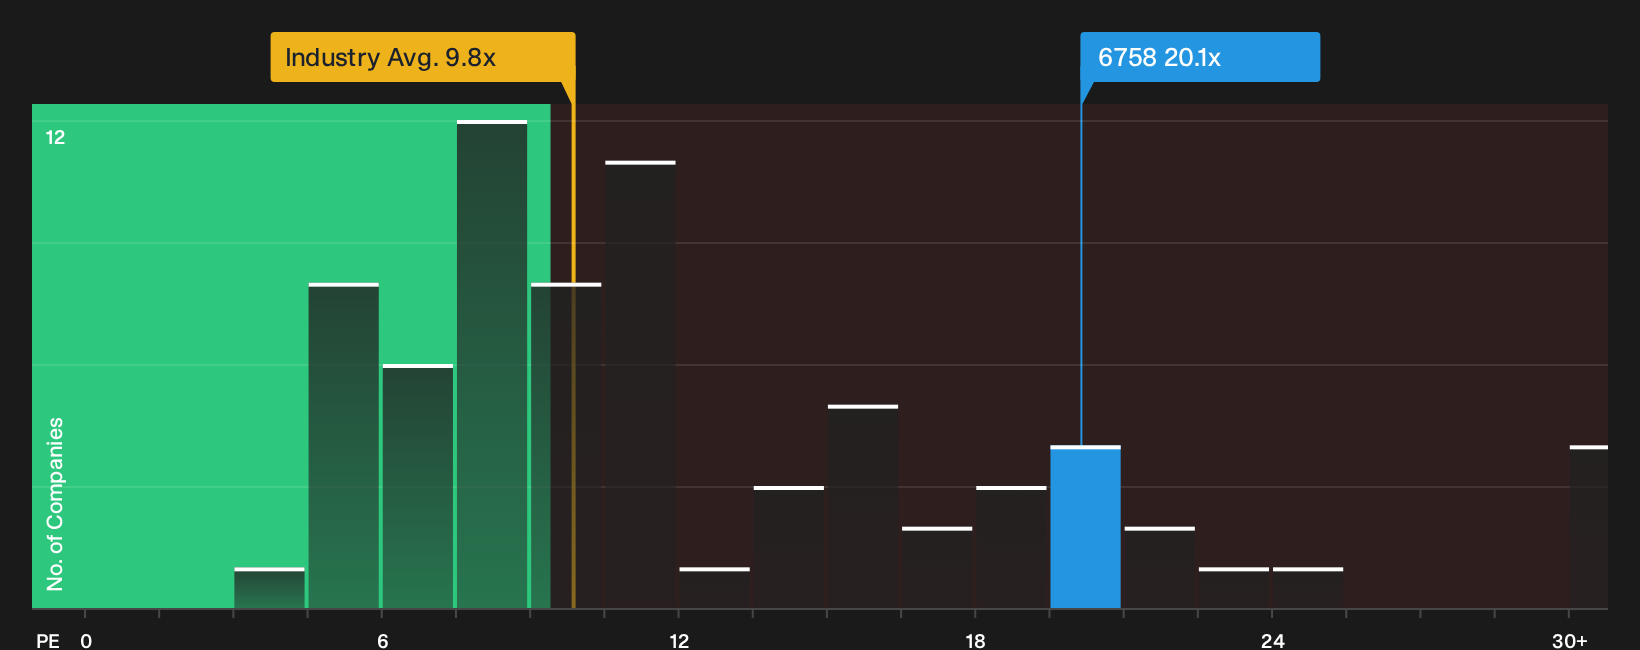
On the surface, Sony Group looks cheap against an estimated fair value, trading around 13.4% below that figure and at a P/E of 20.1x versus a fair ratio of 24.3x. Yet the same multiple is more than double the JP Consumer Durables industry at 9.8x and below a 25.3x peer average, which raises a simple question for investors: Is this a reasonable premium for quality earnings or a narrow margin for error if growth underwhelms?
For a closer look at how this P/E premium and the fair ratio could shift if earnings expectations change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Sony Group can feel confusing. Move quickly, review the full dataset, and weigh both sides of the story using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sony Group?
If you stop with Sony Group, you risk missing other opportunities that fit your style, so put a few minutes into widening your opportunity set today.
- Target resilient income by scanning for companies that pay sizeable yields and aim to protect payouts through different cycles using the 28 dividend fortresses.
- Hunt for quality at a discount by sorting for companies that combine strong fundamentals with valuations that sit below intrinsic estimates through the 12 high quality undervalued stocks.
- Focus on sleep-at-night holdings by filtering for businesses with healthy balance sheets and robust financial profiles using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com