
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Oil Stocks With Direct Exposure To Tight Crude Supplies
Oil reserves are being drained, refilling them could take years, and more than 1b barrels have already been pulled from storage, so the pressure on crude markets is building. That kind of squeeze can punish some sectors while creating sharp openings elsewhere. This article walks through three integrated oil and gas stocks exposed to this supply story and shows how the same backdrop can signal either opportunity or risk for your portfolio.
The stocks covered below are just a small sample, and the full screen on integrated producers surfaced 56 more large cap operators with equally compelling stories that are not broken out in this article.
To see the complete field and identify which businesses best fit your own risk, income and balance sheet preferences, head straight into the Global Integrated Oil & Gas Producers screener.
InPlay Oil (TSX:IPO)
InPlay Oil is a Calgary based producer focused on light crude and natural gas in West Central Alberta, giving it direct exposure to the tight oil supply theme. It generated about CA$317.9 million from exploration and production and has a market value of roughly CA$490 million.
For an investor looking at integrated oil and gas producers tied to tight crude supplies, InPlay Oil offers pure upstream exposure. Operations are concentrated in light oil and liquids rich gas, production guidance for 2026 has been revised higher, and dividend payments plus buybacks show management returning capital while one unseen pressure still hangs over future cash generation.
That lingering question on future cash generation is exactly what you should stress test with the 4 key rewards and 3 important warning signs (2 are major!) and see what the market might be missing.

Japan Petroleum Exploration (TSE:1662)
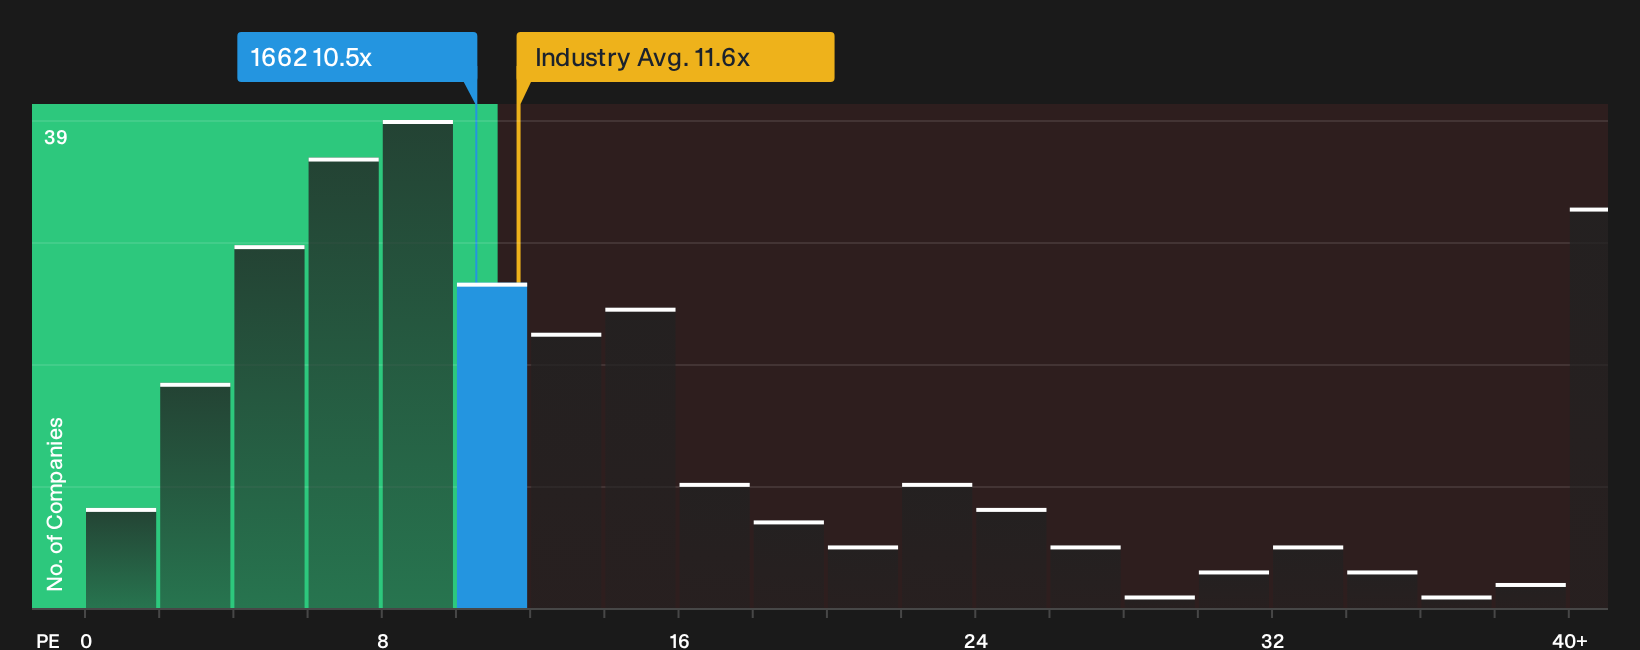
Japan Petroleum Exploration is a large upstream oil and gas producer in Japan, Europe, North America, and the Middle East, a direct fit for this integrated crude supply theme. It booked about ¥235.4b from Japan, ¥51.7b from North America, ¥30.9b from the Middle East, and ¥4.6b from Europe, with a market value near ¥429.8b.
Japan Petroleum Exploration provides focused exposure to exploration and production at a time when global reserves are tight, inventories are thin, and new Asian stockpiles are adding demand pressure. The business is profitable, trades on a moderate P/E, and carries manageable leverage, so future margins depend on how one unseen pressure in its funding mix and payout policy is resolved.
That funding and payout tension is exactly what you can unpack in the 2 key rewards and 2 important warning signs to assess how Japan Petroleum Exploration may be valued in relation to its future cash returns.
SM Energy (SM)
SM Energy gives this integrated producers screen direct exposure to U.S. oil, gas and NGL production, with every dollar tied to upstream barrels rather than fees or refining margins, and that is exactly where tight global supply and low inventories bite hardest.
SM Energy focuses on acquiring, drilling, and producing oil, gas, and natural gas liquids across U.S. shale basins, generating about US$4.96b from exploration and production in 2025, all in the United States, and carries a market value near US$8.82b.
In a market leaning on emergency stockpiles and facing years of inventory rebuilding, SM Energy offers direct exposure to that crude tightness while management talks up the work going on behind the scenes.
"Continued technological and operational optimization, such as completion and well cost efficiencies aggressively applied in Uinta and Midland Basin assets, are driving lower per‑unit costs, enhancing production performance, and positioning SM Energy to better withstand commodity price volatility, supporting resilient net margins and free cash flow."
The real swing factor for SM Energy is how one unseen pressure on future capital allocation shapes the balance between growth, buybacks, and resilience.
That capital mix is exactly what you can unpack in the full narrative for SM Energy to see where SM Energy’s capital allocation could be quietly accelerating long term value.

Seeking Alternatives Before The Window Closes
Fresh ideas often move first. Breakout stories can gain momentum while prices are still under the radar. Consider exploring opportunities early rather than reacting later.
- Target reliable income streams by scanning dividend payers built around resilience through the 3 dividend fortresses while yields remain attractive.
- Search for financially disciplined compounding stories with the curated 9 high quality undervalued stocks while quality may still be mispriced and momentum is developing.
- Identify financially solid outliers through the hand picked 9 high quality undiscovered gems before more investors recognize them and competition for entry increases.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com