
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 European Bank Stocks That Could Benefit From Higher Bond Yields
Bond markets in France, Italy and the UK are putting governments on a stricter leash, and that shift is quietly reshaping the risk and reward profile across European assets. Higher yields and fiscal restraint can be uncomfortable for some sectors, yet create fresh openings where stronger balance sheets and interest income matter more. This article walks through three European bank stocks exposed to that story and explains what the changing backdrop could mean for each one.
The three stocks below are just a starting sample from this theme, and the full screen surfaced 9 more large European banks with equally compelling stories that are not covered here. To identify and analyze the highest conviction ideas in this space, head straight to the European Bank Stocks screener.
Banca Monte dei Paschi di Siena (BIT:BMPS)
Overview: Banca Monte dei Paschi di Siena is a long-established Italian bank focused on retail, wealth management and corporate lending services.
Operations: Most reported revenue comes from the Corporate Center at €455.6 million, with a €4.4 billion Segment Adjustment and €764.2 million from Corporate & Investment Banking.
Market Cap: €33.4b
For the European Bank Stocks theme, Banca Monte dei Paschi di Siena is one of the more direct ways to track how Italian fiscal credibility and higher local bond yields may affect a domestically focused lender’s profits and perceived resilience.
"Improved asset quality, capital strength, and expansion initiatives are key factors for the bank’s profitability, strategic growth, and shareholder returns in the context of ongoing sector consolidation."
A key test for Banca Monte dei Paschi di Siena is how one unresolved pressure on its Italian exposure ultimately influences earnings quality.
That pressure point is exactly where the full story gets interesting. Read the full narrative for Banca Monte dei Paschi di Siena to see how that risk could be masking upside.

Banco BPM (BIT:BAMI)
Overview: Banco BPM is a large Italian retail and corporate lender whose earnings are closely tied to domestic interest rates and Italian government bond conditions.
Operations: Banco BPM generates most income from Commercial Management at €3.6b and Corporate and Investment Banking at €1.1b, with additional contributions from Asset Management at €609 million and Finance at €501 million.
Market Cap: €22.2b
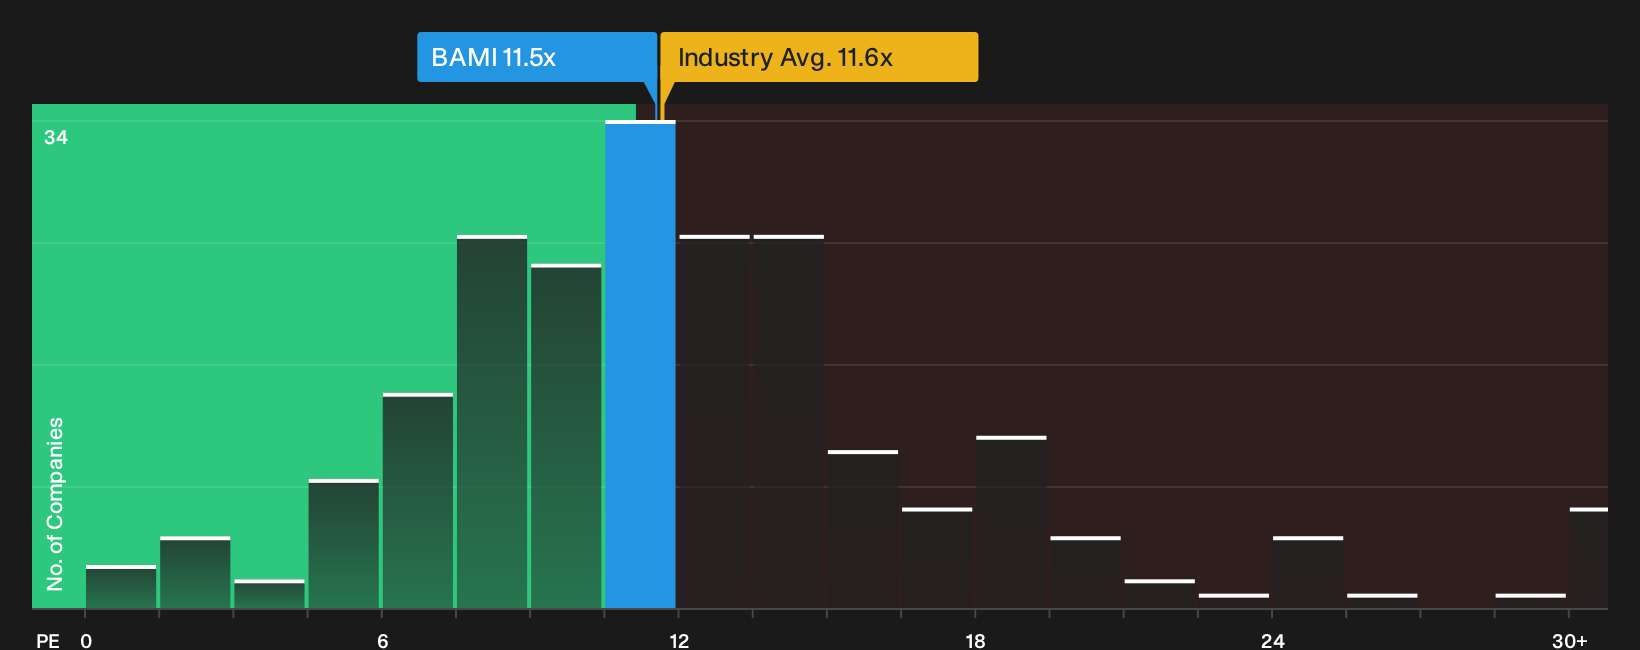
Within the European Bank Stocks theme, Banco BPM offers direct exposure to how Italy’s higher bond yields, tighter fiscal policy and domestic rates filter into bank profitability. The stock screens as a large, profitable lender with a P/E around 11.5x and with expectations for earnings and revenue growth; however, the real story for margins and valuation depends on how one unresolved pressure around Italian risk premia develops.
If you want to see how that pressure on Italian risk premia shows up in the numbers, review the analysis report for Banco BPM to identify what could be getting mispriced.
Lion Finance Group (LSE:BGEO)
Overview: Lion Finance Group is a London headquartered banking group listed in the UK that runs high growth universal banking platforms across Georgia and Armenia.
Operations: Reported income is concentrated in a GEL 3.1b segment adjustment, alongside GEL 1.2b from Armenian Financial Services and GEL 182 million from Other Businesses.
Market Cap: £5.3b
For the European Bank Stocks theme, Lion Finance Group gives you a listed UK banking group whose fortunes track both frontier economies and broader risk appetite across European financials.
"Accelerating digital adoption and continued success in digital transformation are expanding Lion Finance Group's active customer base (for example, 15.5% year-on-year growth in digital users, 1.7 million digital banking customers, 86% of loans issued digitally). This supports structural growth in revenue and efficiency gains that, if sustained, could improve net margins over time."
The real swing factor is how one emerging source of pressure ultimately feeds through to credit costs and the durability of those margins.
That emerging pressure is exactly why reading the full narrative for Lion Finance Group can be so useful, as it unpacks how Lion Finance Group’s digital engine could still surprise.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is obvious, the cleanest entry points are already dropping away. Scan under the radar for now and consider getting in early.
- Look for cash generative small caps before they start flying by running the 39 profitable AI stocks that aren't just burning cash while it still surfaces businesses most investors have not focused on yet.
- Identify resilient payers with strong balance sheets by scanning the 223 dividend fortresses before rising yields bring more attention to these higher income opportunities.
- Monitor early leadership in digital currencies and blockchain infrastructure by reviewing the curated 20 cryptocurrency and blockchain stocks while these stories are still building momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com