
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CTP (ENXTAM:CTPNV) Lands Romstal Lease As Fair Value Questions Return
CTP (ENXTAM:CTPNV) drew fresh attention after leasing 24,400 sqm to Romstal at CTPark Bucharest South in Romania, further linking the stock story to logistics demand in the CEE region.
CTP’s leasing win with Romstal comes after a tough stretch for the shares, with the 90-day share price return down 24.7% and the year-to-date move down 29.8%, while the 3-year total shareholder return of 2.04% indicates relatively muted longer-run gains and fading momentum.
Scan other logistics focused real estate plays with resilient demand profiles across Europe using the hand picked list of solid balance sheet and fundamentals (204 results).
CTP’s share price slide has reset expectations after a strong run, yet the Romstal deal underlines a business still signing meaningful leases. Does the current valuation already reflect that, or is there more upside left?
Price-to-Earnings of 10.9x: Is it justified?
Valuation on CTP now hinges on a P/E of 10.9x that looks richer than its immediate peers yet only slightly below the broader European real estate average.
The P/E ratio compares the current share price with earnings per share and, for a landlord developer like CTP, it captures what investors are willing to pay for each euro of profit today.
At 10.9x versus a peer average of 8.4x, the market is assigning a higher earnings tag than for similar real estate stocks. At the same time, the 10.9x multiple sits a touch below the European real estate industry average of 11.3x, which keeps the valuation profile from looking extreme on a sector-wide view.
Result: Price-to-Earnings of 10.9x (OVERVALUED).
See what the numbers say about this price — find out in our valuation breakdown.
Still, CTP faces pressure if logistics demand in Central and Eastern Europe cools, or if higher funding costs chip away at returns on new developments.
Find out about the key risks to this CTP narrative.
Another View: What The DCF Says About CTP
The P/E points to CTP looking expensive versus peers, yet the SWS DCF model paints a different picture. On that score, the shares trade at €12.38 compared with an estimated future cash flow value of €13.51, roughly 8% below fair value. Which signal do you trust more for the long haul?
Look into how the SWS DCF model arrives at its fair value.
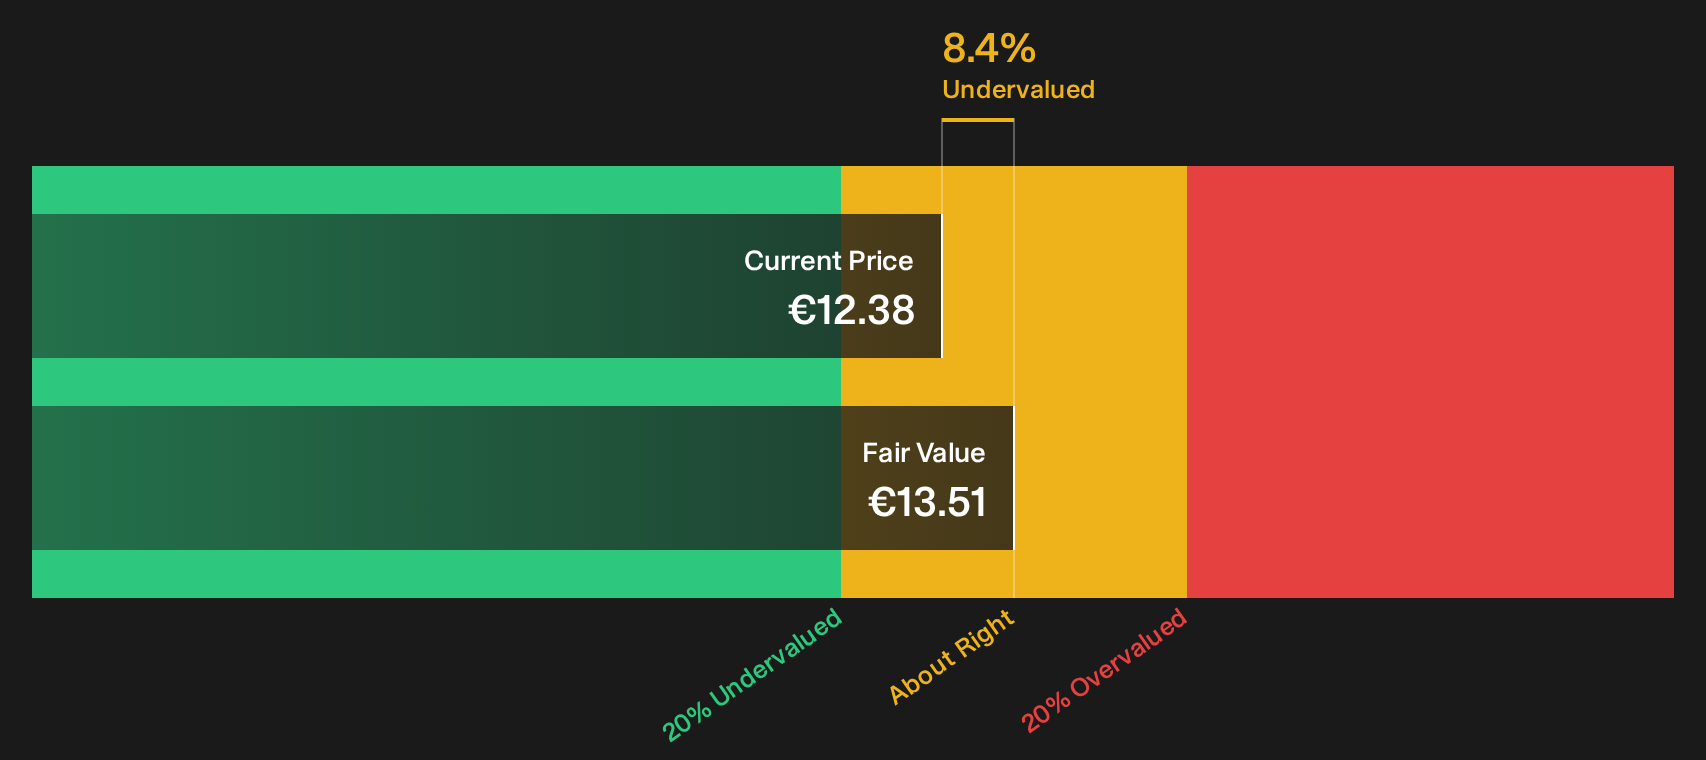
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CTP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on CTP so far. If you want to move quickly and rely on your own judgment, start by weighing the 3 key rewards and 4 important warning signs.
Looking for more CTP investment ideas?
If CTP has sharpened your focus on valuation and risk, do not stop there. Use targeted screeners to uncover other opportunities that fit your approach.
- Target potential mispricings by reviewing companies that screen as attractively valued on quality metrics through the 173 high quality undervalued stocks.
- Build a steadier income base by scanning for high yielders with robust payout support using the 223 dividend fortresses.
- Prioritise resilience by filtering for businesses with strong finances and durable fundamentals via the 223 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com