
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Air Products and Chemicals (APD) Expands In Malaysia As Valuation Debate Stays In Focus
Air Products and Chemicals (APD) has signed a definitive agreement to design, build and operate an LNG based air separation unit at Malaysia’s Pengerang LNG regasification terminal, expanding its industrial gas footprint in Asia.
Against that backdrop, Air Products and Chemicals has seen its share price slip 4.7% over the past month and 6.1% over the past quarter, even though the year to date share price return is 12.3% and the 1 year total shareholder return is 12.3%, pointing to longer term momentum that contrasts with more recent weakness as investors reassess growth opportunities and risks around new LNG linked projects.
Scan for other industrial gas and LNG infrastructure plays showing similar momentum shifts using the hand picked 43 power grid technology and infrastructure stocks that could complement a watchlist focused on Air Products and Chemicals.
Air Products and Chemicals now trades around US$281 while analyst targets and intrinsic value estimates cluster meaningfully higher, so the real question is how that valuation gap compares with the recent wobble in the share price.
Most Popular Narrative: 18.5% Undervalued
The most followed narrative pitches a fair value for Air Products and Chemicals around $345, comfortably above the last close near $281, and ties that gap to a mix of capital discipline, electronics demand and cleaner energy contracts.
Capital discipline and portfolio optimization, including the decision not to proceed with the Louisiana Clean Energy Complex and several other clean energy projects and the related plan to lower annual capex toward about US$2.0b to US$2.5b with roughly US$1.5b focused on traditional industrial gas projects, may free cash for higher return uses and support future return on capital and free cash flow.
See why 75 investors see Air Products and Chemicals as 19% undervalued.
Result: Fair Value of $345.11 (UNDERVALUED)
Still, this narrative can unravel if large hydrogen and ammonia projects overrun on cost, or if helium pricing pressure keeps earnings from tracking those optimistic margin targets.
Find out about the key risks to this Air Products and Chemicals narrative.
Another View: Air Products and Chemicals Through the Sales Lens
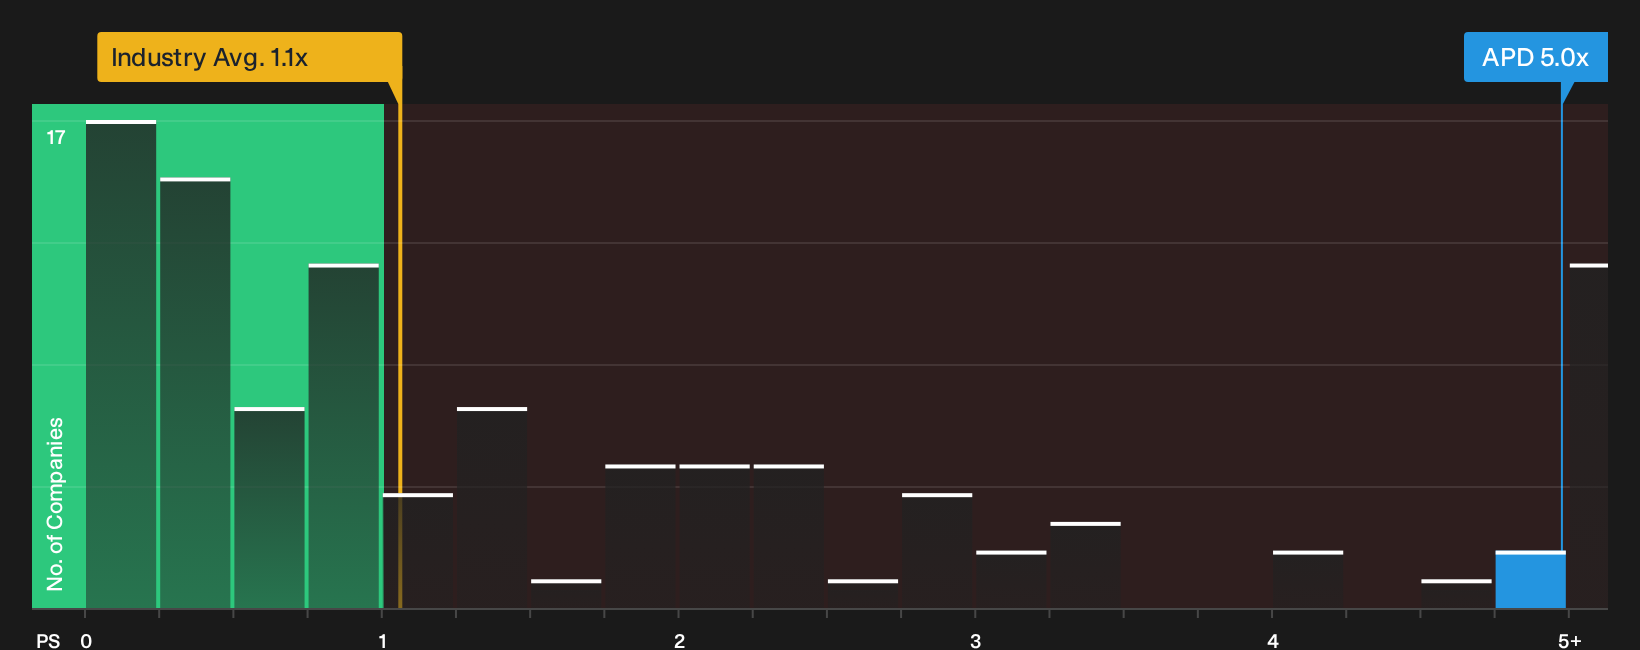
On the flip side of that fair value story, Air Products and Chemicals screens as expensive on simple sales based metrics. The stock trades on a P/S of 5x, while the US Chemicals industry sits around 1.1x and close peers average 4.2x, against a fair ratio of 2.3x that the market could eventually gravitate toward. Is this a quality premium or a valuation risk that narrows the 18.5% undervaluation gap implied by the narrative model?
See what the numbers say in more detail, and how much faith you want to place in the current earnings reset versus that rich revenue multiple, in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Air Products and Chemicals so far, right? Move fast to test the thesis against the data and round out your view with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Air Products and Chemicals?
If you only focus on Air Products and Chemicals, you risk missing other setups where valuation, quality and income potential might align even more cleanly.
- Target potential mispricing and compare a broader opportunity set by scanning the 28 high quality undervalued stocks that match your quality and balance sheet standards.
- Lock in income ideas by lining up companies in the 8 dividend fortresses that might fit a watchlist built around regular cash payouts.
- Calm portfolio volatility by filtering for companies in the 31 resilient stocks with low risk scores that could help steady returns when individual holdings move around.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com