
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FirstCash Holdings (FCFS) Could Be 60% Overvalued On Fresh Debate Over Its Risks
Interest around FirstCash Holdings (FCFS) increased after high profile commentary highlighted its pawn focused model, strong recent share performance, and the risk profile of its consumer lending segment.
The recent attention has landed on a stock that already had momentum. FirstCash Holdings has a year to date share price return of 36.31%, while the 1 year total shareholder return of 43.05% and 5 year total shareholder return of 163.19% point to gains that have compounded over time. However, the 30 day share price return is down 6.01%, suggesting near term enthusiasm has cooled after a strong multi year run.
Scan how FirstCash Holdings compares to other pawn and consumer finance plays by reviewing our hand picked 31 resilient stocks with low risk scores that aim to balance returns with more resilient profiles.
FirstCash Holdings has surged over several years, yet the recent pullback and premium P/E leave a real fork in the road. Do you lean into the momentum now, or wait for a cleaner valuation entry?
Price-to-Earnings of 23.9x: Is it justified?
On current numbers, FirstCash Holdings trades on a P/E of 23.9x, which aligns with a market that is pricing in strong profitability relative to many peers.
The P/E ratio compares the share price to earnings per share. For a lender and pawn operator like FirstCash Holdings, this metric reflects how much investors are paying for each dollar of profit from its pawn operations and retail point of sale financing activities.
Earnings have been growing at 19.3% per year over the past 5 years, with a 33% increase in the last year alone, and are forecast to grow 17.6% per year. That growth profile helps explain why investors are willing to accept a richer P/E, even though the business has a high level of debt and uses higher risk funding rather than low cost customer deposits. The SWS fair P/E of 14.5x points to a level the market could move towards if expectations cool or growth moderates.
Against the US Consumer Finance industry average P/E of 9x and a peer average of 15.4x, the 23.9x multiple for FirstCash Holdings is materially higher, which signals investors are paying a clear premium versus both the sector and closer comparables.
Explore the SWS fair ratio for FirstCash Holdings.
Result: Price-to-earnings of 23.9x (OVERVALUED)
Still, the consumer lending exposure and reliance on higher risk funding could quickly pressure FirstCash Holdings if credit conditions tighten or if regulatory scrutiny increases.
Find out about the key risks to this FirstCash Holdings narrative.
Another View on FirstCash Holdings: Cash Flows Paint a Harsher Picture
The P/E suggests investors are paying up for FirstCash Holdings. The SWS DCF model tells a very different story. On that framework, the shares at $213.70 sit well above an estimated future cash flow value of $86.38, which points to a stock that screens as heavily overvalued on cash generation.
That gap between price and DCF output raises a simple question for you as an investor. Do you trust the earnings multiple that assumes strong profitability can persist, or the cash flow model that prices in more pressure on the underlying economics of pawn and higher risk lending?
Look into how the SWS DCF model arrives at its fair value.
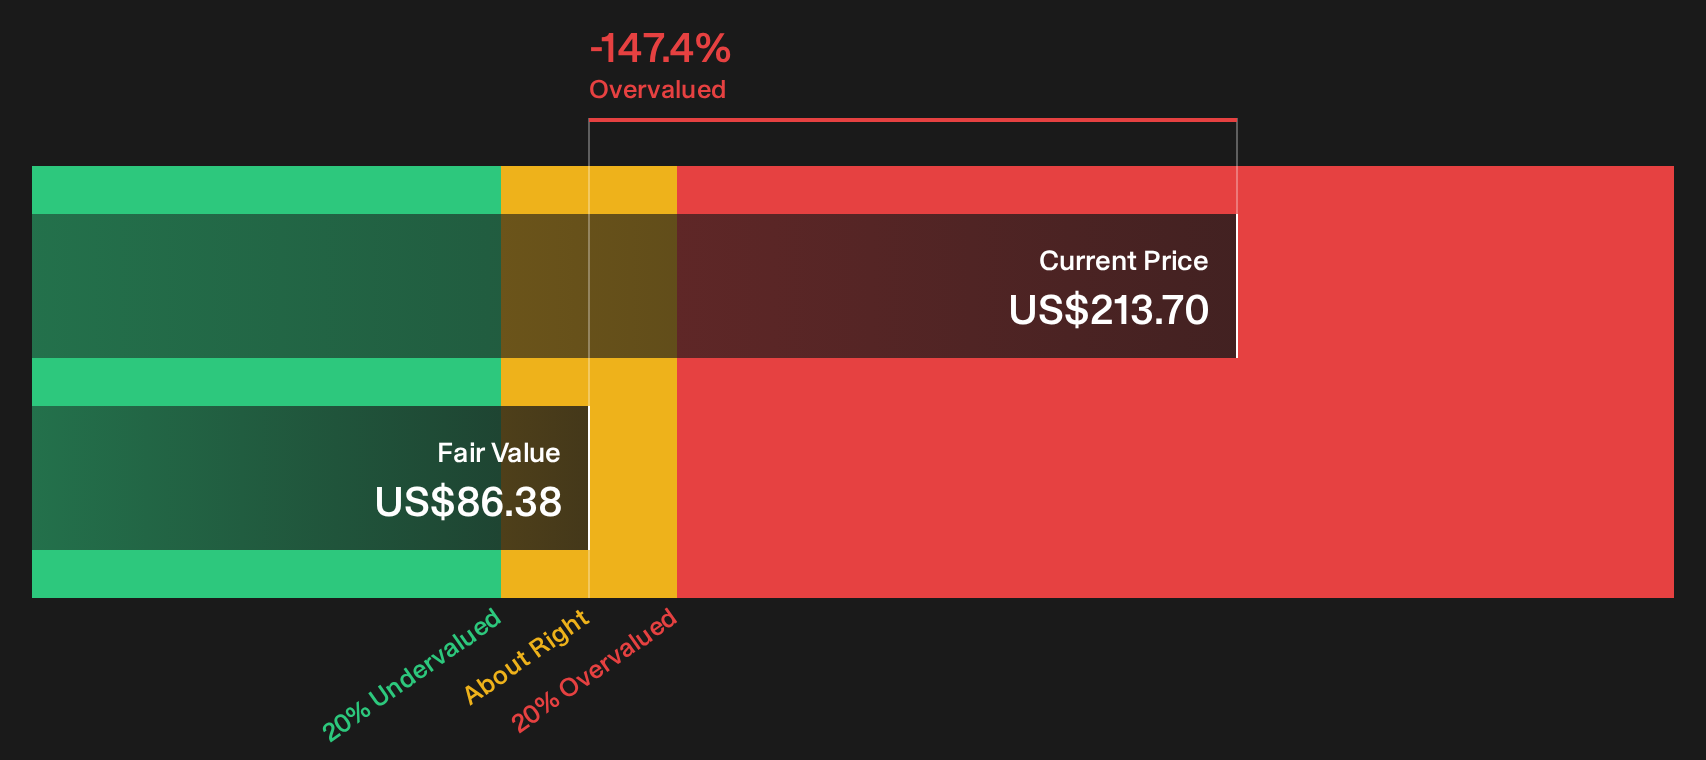
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstCash Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong views are already forming around FirstCash Holdings, yet the real signal comes from your own reading of the numbers and risk flags. If you want a quick way to weigh the tension between what could go right and what might go wrong, start with the 2 key rewards and 2 important warning signs.
Looking for more FirstCash Holdings sized ideas?
If FirstCash Holdings has sharpened your focus, do not stop here. The right watchlist gives you options when this stock no longer sets the pace.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (25 results) that focuses on companies pairing financial strength with consistent fundamentals.
- Hunt for mispriced potential and work through the 20 high quality undiscovered gems that highlight quality businesses still flying under most investors' radar.
- Build a core income list by reviewing the 8 dividend fortresses that focuses on higher yield stocks designed to support steadier portfolio cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com