
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is EPR Properties (EPR) Cheap Or Is Its Experiential REIT Shift Already Priced In?
EPR Properties (EPR) is back in focus after fresh attention on its role as a diversified experiential net lease REIT across the US and Canada, with roughly US$6.1b in assets under management.
Recent trading tells a mixed story. EPR Properties’ share price has slipped over the past month, with a 30 day share price return of down 8.26%. However, the year to date share price return of 7.84% and 1 year total shareholder return of 8.53% point to momentum that has built over a longer window.
Scan beyond EPR Properties and evaluate other real estate players with resilient cash flows using our curated list of list of solid balance sheet and fundamentals (25 results).
Bulls point to EPR Properties’ experiential focus and cash flow discipline. Bears point to the recent share price pullback. As you consider either initiating a new position or waiting on the sidelines, which case does the current valuation appear to support?
Most Popular Narrative: 15% Undervalued
EPR Properties closed at $54.74, while the most followed narrative pegs fair value at $64.68. The gap between price and story is clear.
The company is actively recycling capital out of theaters and education and into attractions, fitness and wellness, golf and other experiential assets, with theaters already reduced to roughly one third of the portfolio and an articulated goal of around 20%, which can improve mix quality and support more resilient earnings and FFO.
See why 79 investors see EPR Properties as 15% undervalued.
Result: Fair Value of $64.68 (UNDERVALUED)
Still, the EPR Properties story leans on discretionary tenants and theater exposure, so weaker experiential spending or box office trends could quickly challenge that 15% undervalued thesis.
Find out about the key risks to this EPR Properties narrative.
Another View: What EPR Properties’ P/E Is Really Saying
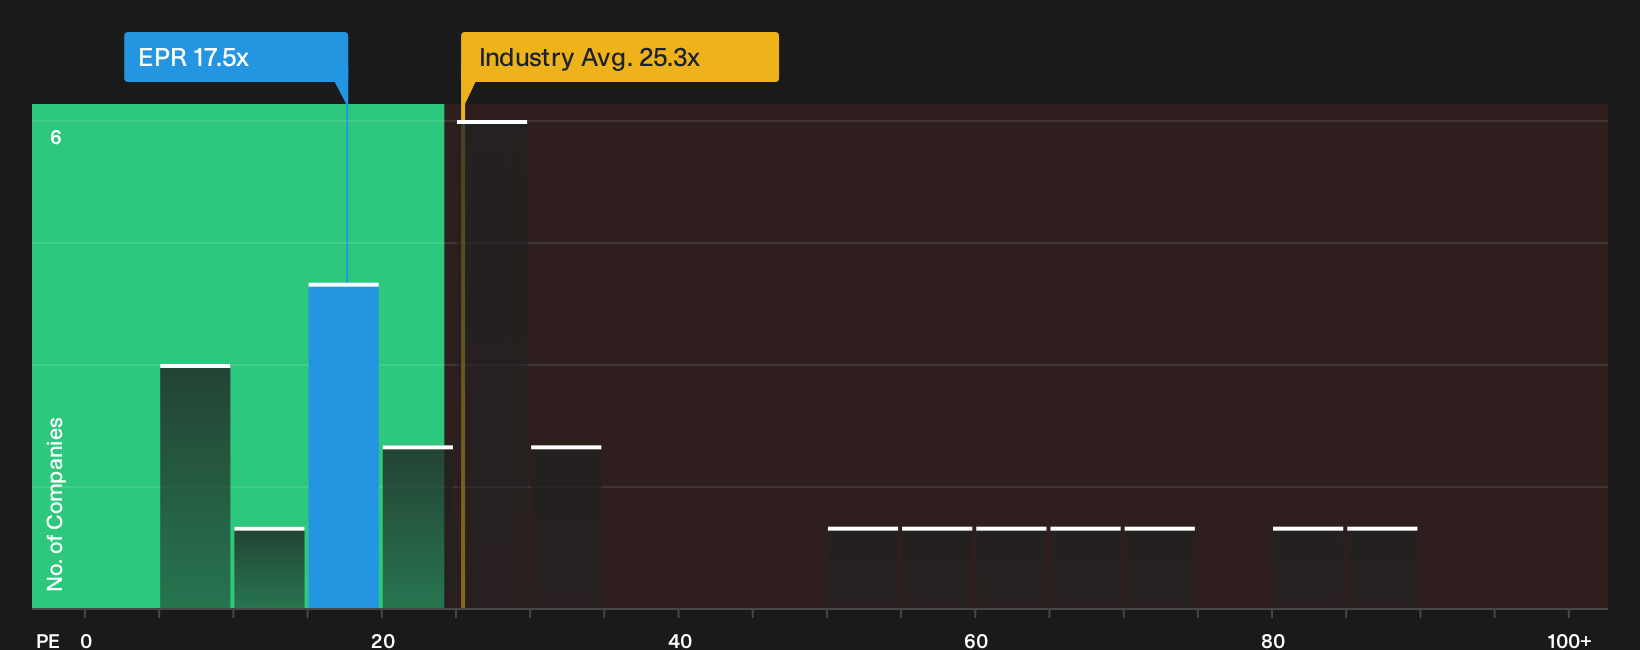
A different lens on EPR Properties comes from its P/E ratio. The shares trade at 17.5x earnings, while peers in the North American Specialized REITs group sit around 24.1x and the fair ratio is estimated at 33x. That gap hints at valuation upside, but it also raises a blunt question. Is the discount compensation for theater and balance sheet risks, or a mispricing that patient investors might see close?
To pressure test that P/E signal against the underlying cash flows and see what the numbers imply for risk and reward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on EPR Properties so far. If you want to move past the headline take, examine the full picture by weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond EPR Properties?
If EPR Properties has sharpened your thinking on valuation and risk, do not stop here. Use the Simply Wall Street Screener to uncover fresh, diversified ideas now.
- Target potential upside by focusing on quality at a discount with a curated set of 28 high quality undervalued stocks.
- Prioritise resilience and capital preservation by reviewing 31 resilient stocks with low risk scores that aim to keep portfolio volatility in check.
- Hunt for tomorrow's potential leaders before they hit the spotlight through our 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com