
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ITT (ITT), What Is Behind The Fresh Attention?
Recent strength in ITT (ITT) shares has been closely tied to a shift in analyst sentiment, with earnings expectations moving higher and a favorable ranking signaling growing confidence in the near term.
At a share price of $201.37, ITT has shown steady momentum, with a 15.59% year to date share price return and a 1-year total shareholder return of 18.75%. The 3-year total shareholder return of 110.02% and 5-year total shareholder return of 125.74% point to a stock where recent analyst optimism is landing on top of an already strong longer term record.
Scan other industrials showing similar earnings momentum and analyst enthusiasm by reviewing the hand picked 28 high quality undervalued stocks alongside ITT.
ITT now trades off a strong run and rising earnings expectations, so the real concern for new money is simple: Does the current price still leave enough upside to justify the risk you take on valuation?
Most Popular Narrative: 22% Undervalued
ITT's most followed valuation storyline pegs fair value at $258.46, comfortably above the recent $201.37 close, which puts the current optimism in sharper context.
Strong, sustained order growth and backlog, supported by a company level book to bill of 1.1 in Q2 2026, nearly doubled backlog over three years, and especially high ratios at Svanehøj and SPX FLOW, points to future revenue recognition that may not be fully reflected in ITT’s valuation.
See why 6 investors see ITT as 22% undervalued.
Result: Fair Value of $258.46 (UNDERVALUED)
Still, ITT’s story can crack if large multi year projects face timing pushouts or if acquisitions like SPX FLOW and Svanehøj underdeliver on planned cost gains.
Find out about the key risks to this ITT narrative.
Another View: ITT Through The Earnings Multiple
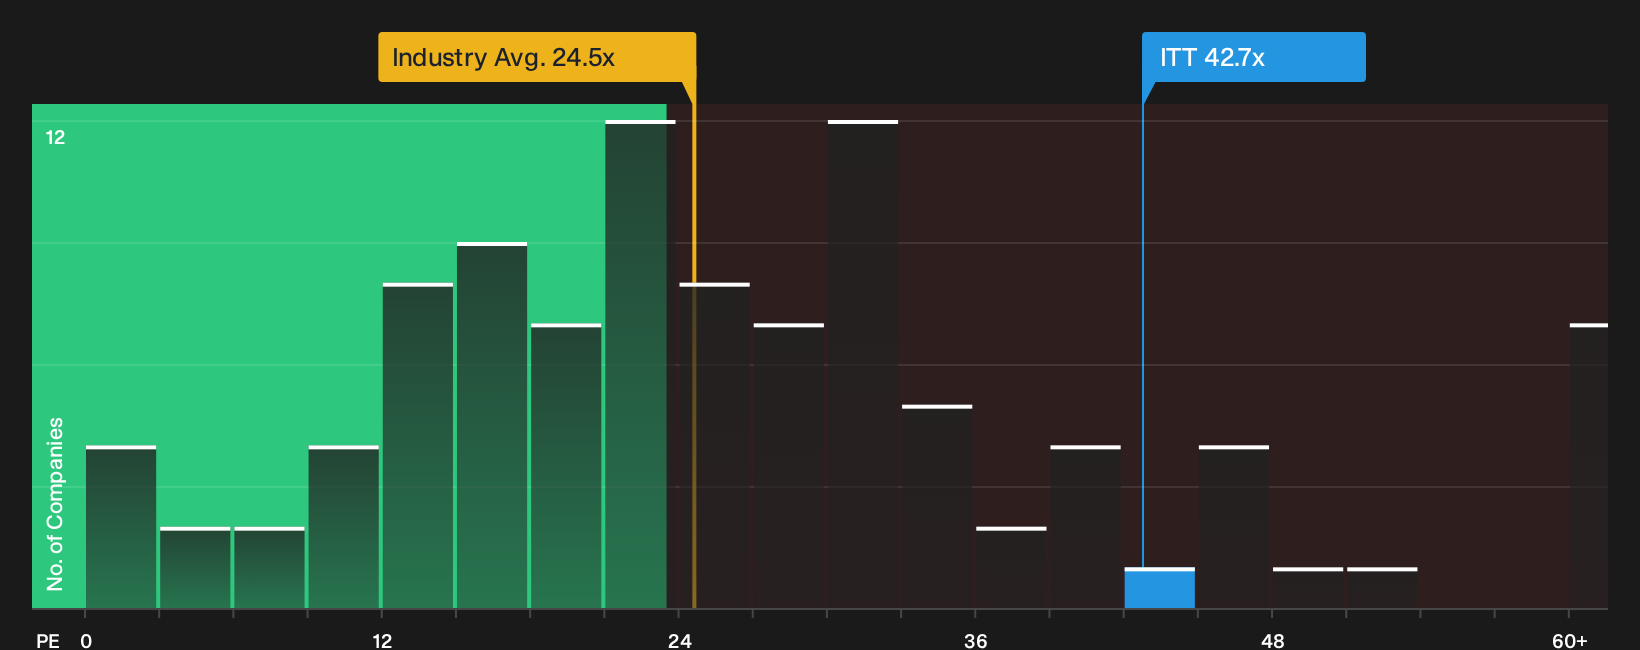
That 22% undervalued storyline for ITT leans heavily on analyst fair value and future earnings power. A plain P/E check paints a sharper picture. The shares trade at 42.7x earnings versus 24x for the US Machinery group and a fair ratio of 29.8x, which suggests a richer price tag and raises the question of how much good news is already reflected.
For a closer look at how this earnings multiple compares with peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and concern around ITT feels familiar, move quickly and scrutinize the same numbers yourself, especially the balance of upside and downside that sits behind the 3 key rewards and 2 important warning signs.
Looking for more ITT style investment ideas?
Do not stop with ITT. Spend a few minutes scanning fresh opportunities now, or you may miss risk reward setups that better fit your objectives.
- Target resilient income by checking companies in the 8 dividend fortresses that aim to pair higher yields with durable fundamentals.
- Look for potentially mispriced quality and review the 20 high quality undiscovered gems that the market may not be paying full attention to yet.
- Dial down portfolio stress and focus on the 31 resilient stocks with low risk scores designed to surface sturdier balance sheets and calmer price swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com