
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Expro (XPRO) Back In Focus Following Mixed Earnings And A Valuation Debate
Why Expro Stock Is Back In Focus After Mixed Earnings And Sector Shocks
Expro (XPRO) moved back onto investor watchlists after revenue topped analyst forecasts while overall sales declined, earnings missed estimates, and sector sentiment shifted following a Gulf tanker attack and hurricane related production outages.
At a share price of US$16.17, Expro has backed off recent highs with a 30 day share price return down 11.11%. Although year to date the share price is still up 18.55% and the 1 year total shareholder return of 34.41% contrasts with a weaker 3 year record, this points to momentum that has picked up more recently as investors reacted to the earnings surprise, contract extension, sector shocks and the planned move to the Cayman Islands.
Compare Expro's renewed attention with other energy service plays by scanning our hand picked list of 20 high quality undiscovered gems riding similar contract wins and sector shocks.
Expro has cooled off after a sharp run and fresh headlines. At the same time, the tax shift, contract extension, and mixed earnings keep the story live. Does the balance of risk and reward still lean toward buyers at US$16.17?
Most Popular Narrative: 10% Undervalued
Expro is trading at $16.17 against a widely followed fair value estimate of $18.00, which frames the stock as moderately discounted and puts execution on future contracts and cash flows in the spotlight.
Realization of synergies from recent M&A, continuous operational cost initiatives (Drive25), and a scalable integrated services portfolio are enabling sustainable EBITDA margin expansion and improved free cash flow generation, positioning Expro to outperform peers on profitability.
See why 5 investors see Expro as 10% undervalued.
Result: Fair Value of $18 (UNDERVALUED)
Still, Expro's heavy exposure to offshore projects and reliance on large global operators means that regulatory shocks or delayed contract spending could quickly challenge the thesis that the stock is 10% undervalued.
Find out about the key risks to this Expro narrative.
Another View On Expro's Valuation
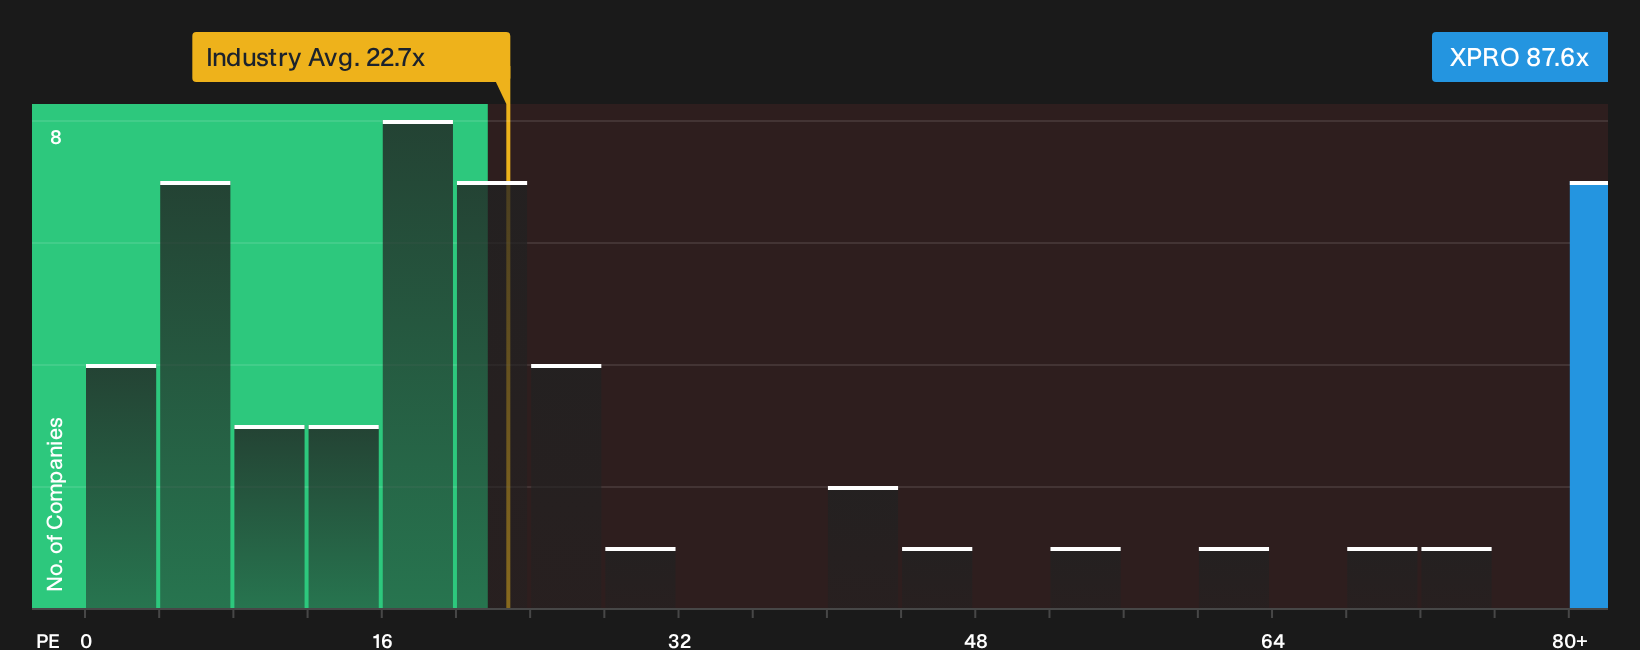
The earlier fair value work frames Expro as undervalued at $16.17. The earnings multiple tells a very different story. On a P/E of 87.6x, the stock trades at almost four times the US Energy Services sector on 22.7x and well above a fair ratio of 34.9x, which points to meaningful valuation risk if sentiment cools.
If you want to see how this rich earnings multiple compares in more detail, including versus peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Expro leaves you uncertain, treat that as your cue to move fast and check the underlying numbers yourself. The clearest way to balance the concerns on one side with the potential upside on the other is to review the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Expro?
If Expro has your attention, do not stop there. The next opportunity you rank highly may sit in a very different corner of the market.
- Target resilience first and scan a 31 resilient stocks with low risk scores that scores well on risk while still leaving room for upside potential.
- Hunt for quality at a discount by reviewing a 28 high quality undervalued stocks that couples solid fundamentals with prices that lag underlying performance.
- Focus on financial strength and shortlist a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and keep compounding through tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com