
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Prysmian Holders Bought Into
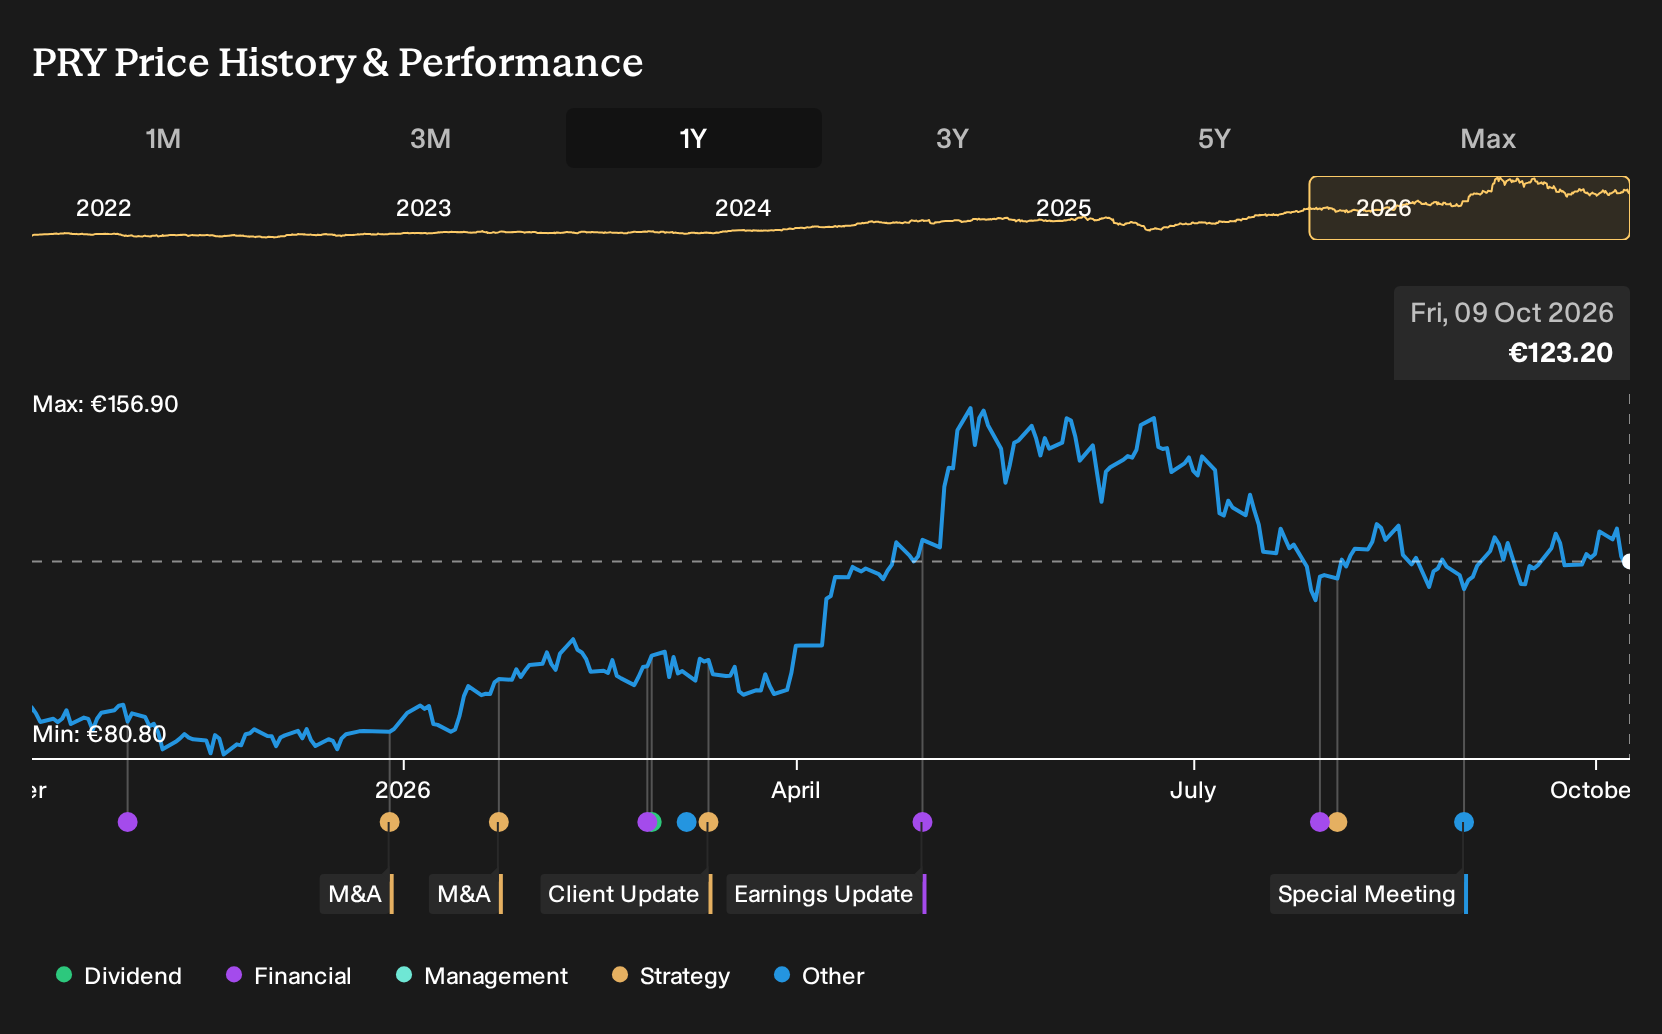
Investors who held Prysmian over the past year are up 41.2%, including dividends. That is a strong payoff for a business that, back on 9 October 2025, split opinion between a bullish €102 fair value view and a more cautious €79.13 assessment. If you were weighing those two cases at the time, how would you have judged the risks around electrification demand, data center fiber, and rising acquisition debt?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The move put Prysmian in the middle of this trade. Scan 43 power grid technology and infrastructure stocks for other companies exposed to it.
The Two Prysmian Stories Investors Had To Weigh
The shares cost €89.82 at the start, and Prysmian sat between two well argued stories about what its future might look like.
On the bullish side, a €102 Fair Value rested on cable technology and higher Transmission margins, with the thesis that data centers and grid projects could support premium profitability while recycling raised cost advantages.
The more cautious €79.13 Fair Value assumed 5.5% annual revenue growth but focused on risks around acquisition driven debt, execution on large grid projects, and pressure from intensifying price competition.
What The Prysmian Evidence Put Under The Microscope
The long term €5.5b Molex fiber contract and more than €1b of U.S. capacity investment gave clear support to the bullish Prysmian story about data center demand and premium cable technology. At the same time, Q2 2026 figures showed revenue and net income above Q2 2025, while net margin slipped from 5.5% to 5.1%. The evidence cut both ways.
The big assumption was not just growth, but quality of that growth. When you test a similar case, track whether expanding contracts and acquisitions coincide with stable or improving net margin rather than only higher sales.
What Prysmian's 41% Run Already Prices In
Prysmian now trades at €123, with this Narrative’s Fair Value sitting below that level. The current assessment frames the group as a quality infrastructure platform tied to electrification, grid constraints, and AI data demand rather than a simple cable supplier.
The selected Narrative asks what needs to keep working smoothly for that price to hold, especially around project delivery, acquisitions, and margins in complex transmission work. A buyer today would need confidence that Prysmian can keep integrating deals while avoiding costly missteps on large contracts.
"The bear case is simpler: the stock is no longer cheap. Prysmian has rerated sharply, with a market cap around €30 billion, a forward P/E in the low 20s, and expectations now embedded for continued flawless execution, clean M&A integration, and sustained margins despite commodity and project risk."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 47% below our estimate - shifts more rolled aluminum volumes into Asia as new capacity reaches breakeven.
- Company 2 - 44% below our estimate - sells oncology software that plugs into rival hardware while adding AI driven treatment planning.
- Company 3 - 34% below our estimate - converts a record project backlog into tech heavy installations for data centers and modular builds.
Those are three of them. See every one of the 173 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com