
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Patient Data Breach Might Change The Case For Investing In iRhythm Holdings (IRTC)
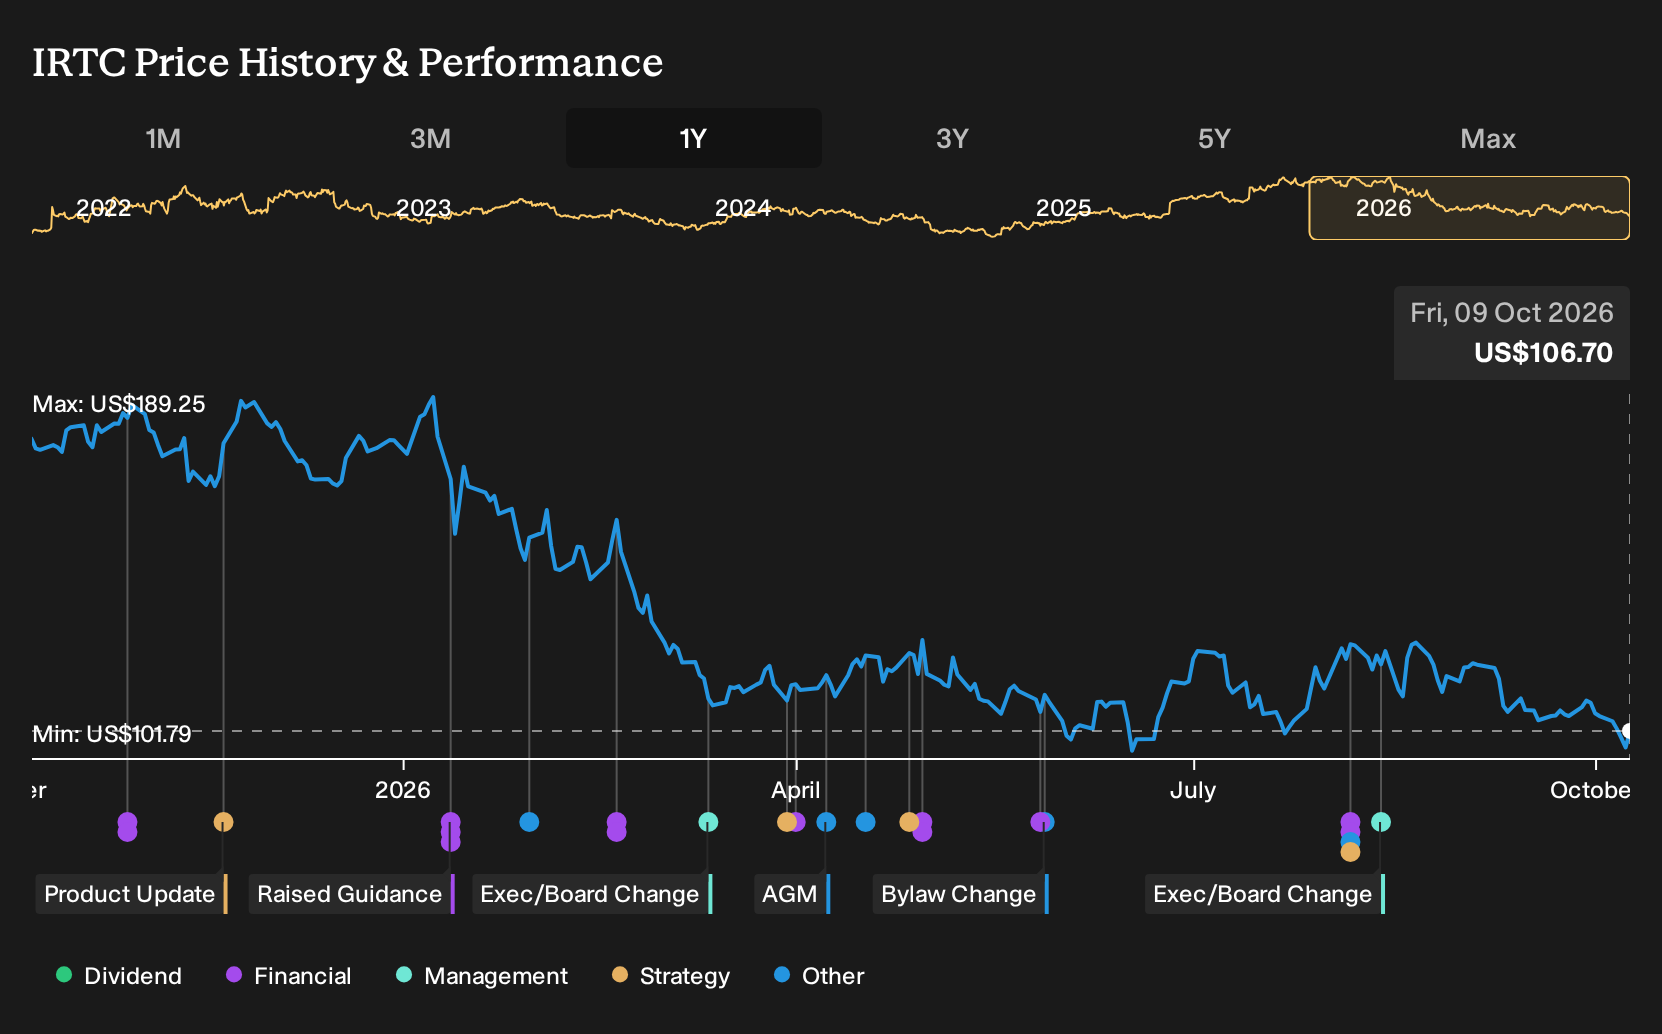
- iRhythm Holdings disclosed a past cybersecurity incident involving unauthorized access to certain patient data, is working with law enforcement and external specialists, and has filed regulatory reports while updating its operational and financial guidance to reflect the disruption.
- The breach directly links a technology and data asset issue to iRhythm Holdings' core service delivery costs and capacity planning, putting execution, compliance spend, and near term operating efficiency under closer investor scrutiny.
- We will now look at how iRhythm Holdings' investment narrative could be reshaped by the recent cybersecurity breach affecting patient data.
Scan how iRhythm Holdings' data risk story compares with other healthcare operators by reviewing our curated list of 34 healthcare AI stocks before you commit fresh capital to this theme.
iRhythm Holdings Investment Narrative Recap
For iRhythm Holdings, the big picture is that ambulatory cardiac monitoring continues to gain share in routine care, and that its Zio platform remains a preferred option for clinicians and payers. The immediate swing factor is execution on volume growth while keeping service capacity, clinician reporting and reimbursement flowing smoothly. The reported cybersecurity incident looks more like an operational distraction than a thesis breaker, unless remediation materially affects costs or processing capacity.
The bigger risk right now sits in an already fragile profitability profile, with the business still reporting losses and relying on improving margins over time. Extra spending on data security, compliance and potential third party audits could add to SG&A at the same time as iRhythm Holdings faces competition, reimbursement pressure and product development needs. The key question is whether the core monitoring service can absorb this incremental load without meaningfully slowing the path toward better cash generation.
The most relevant disclosure for this incident is management’s decision to update operational and financial guidance after reporting the cybersecurity breach. That move links the data issue directly to how the service is running and what investors should expect in the near term in terms of costs and capacity. This is an explicit signal that the event is not just legal boilerplate but has real world implications for the day to day business.
For investors, the key questions are practical. Does remediation work interfere with processing new Zio prescriptions, onboarding accounts or scaling international usage, or does it mainly show up as higher compliance expense inside an already loss making model? Because iRhythm Holdings is still working toward stronger profitability and relies on its technology stack for differentiation, the way it executes on this clean up will directly influence how credible the existing growth and margin catalysts appear over the next few reporting periods.
iRhythm Holdings' current analyst story is based on revenues reaching US$1.2b and earnings of US$97.8m by 2029, built on a 16.0% yearly revenue growth assumption and an earnings swing of about US$125.6m from a loss of US$27.8m today to that projected profit level.
Uncover how iRhythm Holdings' fair value indicates a 68% potential upside to its current price, which could narrow quickly if sentiment turns after the breach response.
Exploring Other Perspectives
Some of the most optimistic analysts were treating iRhythm Holdings’ data assets as a growth engine, not a vulnerability, leaning on forecasts of roughly US$1.4b in revenue and US$145.5m in earnings by 2029. You may now see that same data centric catalyst very differently after a cybersecurity breach, so it makes sense to compare several viewpoints before deciding your own stance.
Explore another iRhythm Holdings fair value estimate, including one that suggests as much as 96% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your iRhythm Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for iRhythm Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate iRhythm Holdings' overall financial health at a glance.
Looking for more investment ideas beyond iRhythm Holdings?
Once you have a view on iRhythm Holdings, it can help to widen the lens and compare it against other opportunities with clear financial traits. The Simply Wall St Screener lets you quickly filter for businesses that match the kind of balance sheet strength, income profile, or risk level you want to focus on next.
- If capital preservation is a priority, you may want to review companies with steadier financial profiles using a 31 resilient stocks with low risk scores that filters for resilience first.
- If quality and balance sheet strength matter most, consider scanning a list of solid balance sheet and fundamentals (25 results) to find businesses that pair financial stability with fundamentals you can study in more detail.
- If you are hunting for less followed opportunities, you can look through a 20 high quality undiscovered gems that highlights companies with strong underlying metrics but relatively limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com