
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Bic Camera (TSE:3048) Undervalued As It Weighs A Dividend Decision?
Dividend decision puts Bic Camera in focus
Bic Camera (TSE:3048) has called a board meeting for 9 October 2026 to consider a dividend of surplus tied to a 31 August record date, along with other corporate matters.
Recent trading has been steady rather than dramatic, with Bic Camera’s 1-day share price return of 1.32% and 7-day share price return of 0.49% sitting against a 30-day share price decline of 3.14%. Total shareholder return of 7.37% over one year and 82.57% over five years reflects momentum that has built over a longer horizon as investors weigh the upcoming dividend decision against the broader risk and reward profile.
Scan how Bic Camera’s dividend plans compare by checking out hand-picked income ideas in the 28 dividend fortresses list before you move on.
That mix of long term shareholder gains and a fresh dividend decision presents Bic Camera as a solid retailer. The real tension is simple: does the current share price still offer enough value for new money?
Price-to-earnings of 12.8x for Bic Camera: Is it justified?
On the latest close, Bic Camera traded at ¥1,653 with a P/E of 12.8x, which screens as inexpensive compared with both peers and its own fair ratio estimate.
The P/E ratio shows how much investors are paying today for each unit of current earnings. For a retailer like Bic Camera, that metric quickly signals whether the market is attaching a premium or a discount to its profit profile, without needing a full model in front of you.
Management has produced high quality earnings and 19.9% profit growth over the past year, while the stock is described as trading at good value versus the Specialty Retail industry average P/E of 12.8x and a peer average of 15.8x. When set against an estimated fair P/E of 14.4x and a DCF fair value of ¥2,314.8 per share, the current multiple looks compressed and suggests the market could shift closer to that higher earnings multiple level if sentiment or results move.
Explore the SWS fair ratio for Bic Camera.
Result: Price-to-earnings of 12.8x (UNDERVALUED)
Still, Bic Camera’s relatively flat year-to-date share performance and the planned dividend decision on 9 October 2026 could disappoint investors if expectations run ahead of board outcomes.
Find out about the key risks to this Bic Camera narrative.
Another view on Bic Camera’s value
The P/E suggests Bic Camera is on the cheap side, yet the SWS DCF model goes further. With the shares at ¥1,653 and a DCF fair value of ¥2,314.8, the stock screens as materially undervalued. That gap raises a simple question: Is the market being too cautious about future cash flows?
Look into how the SWS DCF model arrives at its fair value.
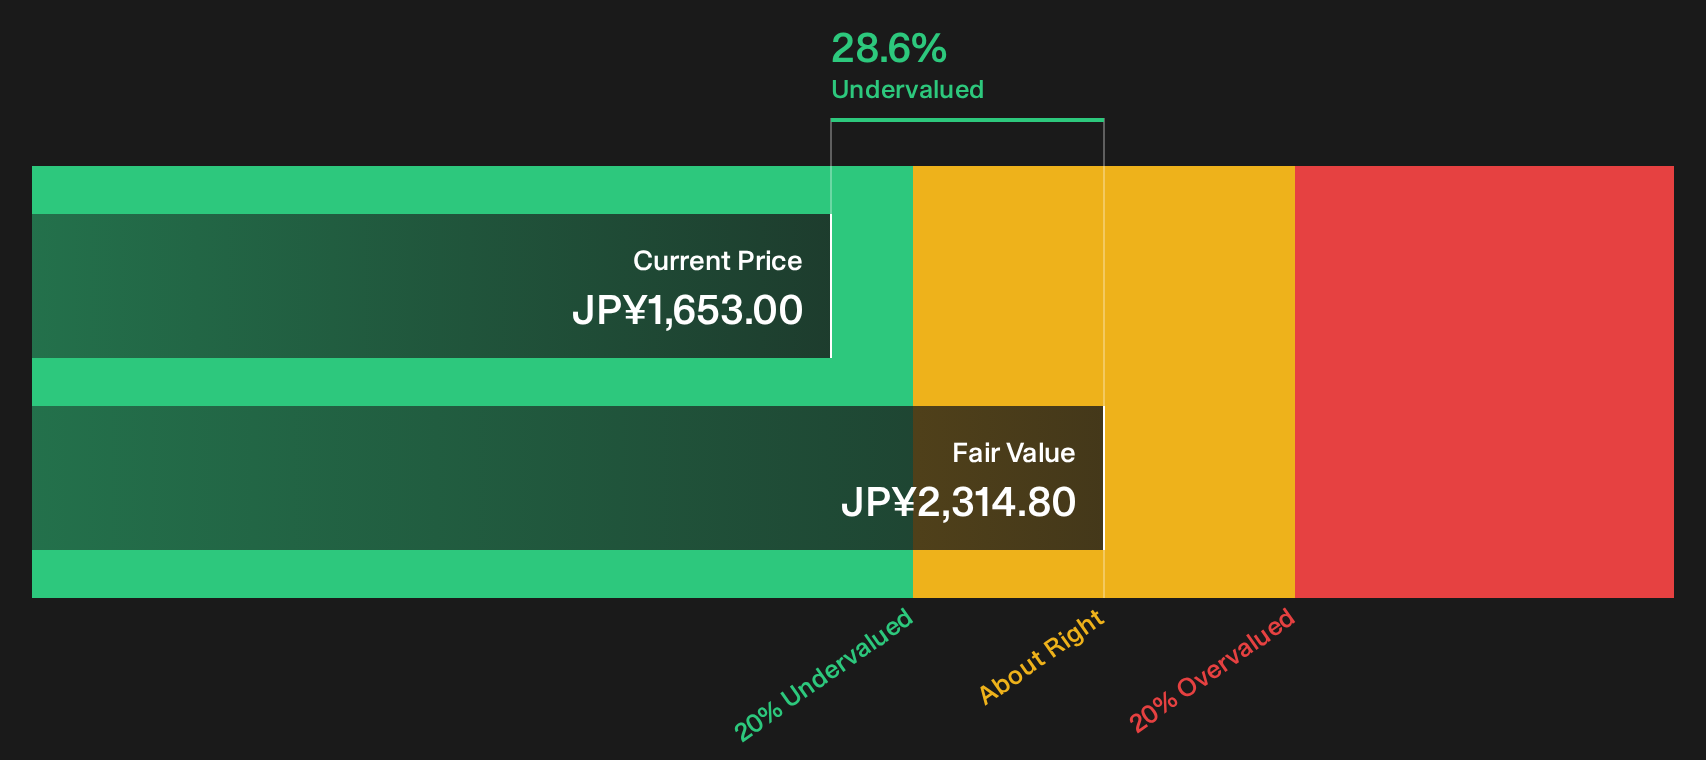
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bic Camera for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Bic Camera is mixed, with clear positives and some concerns pulling in the other direction. It makes sense to check the full picture yourself and decide quickly where you land. To see both sides laid out side by side, review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Bic Camera?
If you stop with Bic Camera, you only see one angle. Broaden your watchlist and you could spot opportunities others are overlooking before they even react.
- Target potential mispricings by running through a 12 high quality undervalued stocks that pairs strong fundamentals with prices that may not fully reflect underlying quality.
- Strengthen your defense by scanning a 23 resilient stocks with low risk scores that focuses on businesses with more resilient profiles when conditions turn against weaker balance sheets.
- Unearth underfollowed opportunities by checking a 74 high quality undiscovered gems that highlights quality companies sitting outside the usual crowded trades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com