
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is ON Semiconductor (ON) Reasonable On Cash Flow After Its All Cash Deal?
ON Semiconductor has delivered a strong multi year share-price run, yet the latest swings now put the spotlight on a simple question for investors: whether the current market value lines up with the cash the business is expected to generate. The stock is coming off a sharp recent pullback and a busy deal announcement, so the focus turns to what its cash flows really justify.
- Over the past 5 years the share price has gained 78.9%, which puts a lot of weight on whether ON Semiconductor's cash generation can support that kind of re-rating.
- The move to a US$5.7b all cash acquisition of Synaptics concentrates financial risk on ON Semiconductor's own balance sheet and future free cash flow, since it trades dilution for higher immediate funding needs.
- Prefer to judge ON Semiconductor on earnings? See why ON Semiconductor's 47.9x P/E tells a different valuation story.
The stock's next move may depend on whether those cash flows, assessed through a Discounted Cash Flow (DCF) lens, are enough to support where ON Semiconductor now trades.
If you want a sense check on ON Semiconductor's recent pullback and all cash deal, it can help to compare it with other companies in similar situations using 28 high quality undervalued stocks
Does ON Semiconductor Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) approach looks at the cash ON Semiconductor can return to shareholders over time and discounts it back to today. ON Semiconductor generated roughly $1.10b in free cash flow over the last twelve months, and the DCF framework used here assumes that this figure grows from current levels rather than shrinking, with free cash flow projections moving into the low to mid single billions over the coming decade.
Based on these cash flow assumptions, the DCF output suggests ON Semiconductor's intrinsic value is broadly in line with the current share price of $77.53. Because the revised $5.7b all-cash Synaptics deal leans on debt instead of equity, the market price already reflects both the potential benefits of higher future free cash flow and the additional financing burden those cash flows need to cover. That balance between growth expectations and funding risk helps explain why the stock now trades close to where the DCF model lands. Find out what ON Semiconductor could be worth using our Discounted Cash Flow (DCF) estimate.
The ON Semiconductor Narrative: What Would Justify Today's Price?
Narratives for ON Semiconductor pick up where the DCF leaves off and explain which combinations of growth, profitability and earnings power would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today. Each narrative ties its valuation anchor to a clear view of how ON Semiconductor's revenue trajectory, profit margins and key risks could evolve, providing a reference point you can revisit as new information becomes available.
ON Semiconductor draws a split crowd, with one side seeing untapped upside and the other thinking most of the good news is already in the price.
Bull case: 25% undervalued
"Rapid secular growth in AI data center infrastructure, coupled with ON's unique position as a US-based provider of intelligent power semiconductors, is generating strong early revenue momentum…"
Discover why this Narrative puts ON Semiconductor at 25% undervalued.
Bear case: roughly fairly valued
"The numbers indicate that ON Semiconductor’s share price already reflects a valuation that assumes meaningful success on AI data center growth, automotive content gains, Fab Right margin improvement and the planned Synaptics integration…"
Explore why this Narrative puts ON Semiconductor at roughly fairly valued.
For ON Semiconductor, the share price is only one piece of the puzzle
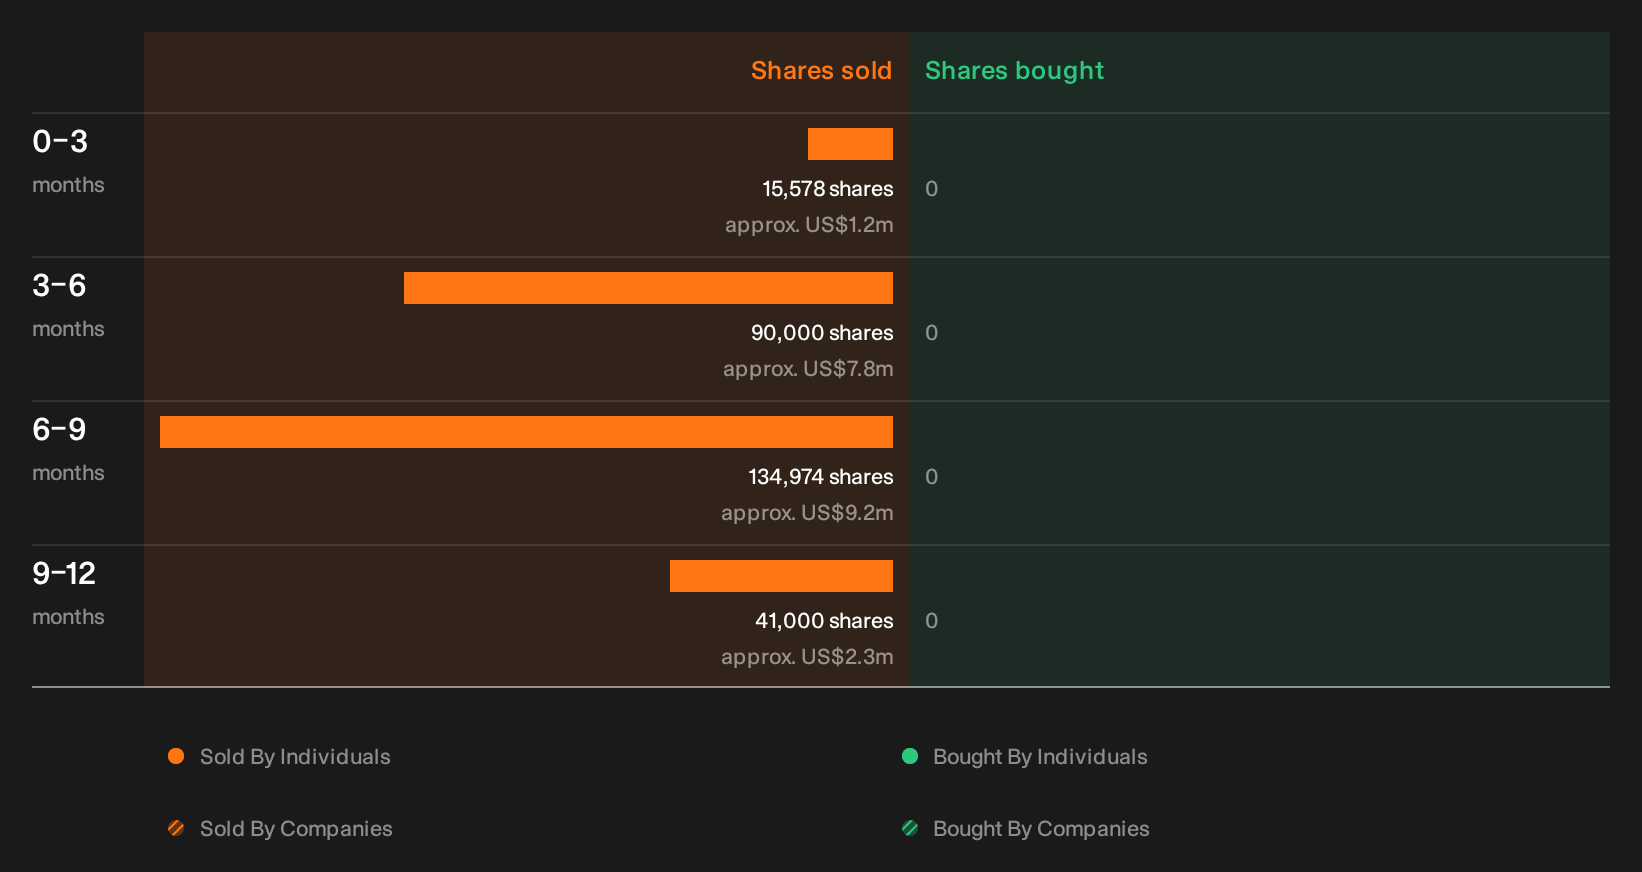
Valuation models tell part of the story, but recent trading activity by company insiders adds another layer that matters for anyone following ON Semiconductor closely. See the recent insider selling flagged for ON Semiconductor.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com