
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Wakita (TSE:8125) Stock Revenue Climbs While Profit Margin Keeps Tightening
The market has treated WakitaLTD like a problem stock for months, with the share price down over the past week and quarter. Yet the latest earnings paint a more specific headache. Q2 2027 profit shrank against a virtually flat top line, squeezing net income to ¥493 million and pulling quarterly basic EPS down to ¥9.91. That pressure lands on a business already running a 3.4% net margin over the last year and paying a 5.58% dividend yield that is described as not well covered by earnings.
Is WakitaLTD a genuine bargain at ¥1,793 or just an expensive stock hiding behind a compressed quarter and a 5.58% yield? See how its DCF gap and rich P/E line up in our valuation analysis for WakitaLTD
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥24,171 million vs. ¥21,589 million (up about 12% year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥493 million vs. ¥552 million (down about 11% year on year)
- Basic EPS (Q2 2027 vs Q2 2026): ¥9.91 vs. ¥11.16 (down about 11% year on year)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 3.4% vs. 4.2% (margin compressed over the year)
Prefer clean charts to squinting at raw earnings tables and dividend math for WakitaLTD?
See the full picture of WakitaLTD's valuation, including how its earnings and payout profile fit together, in our company report for WakitaLTD.
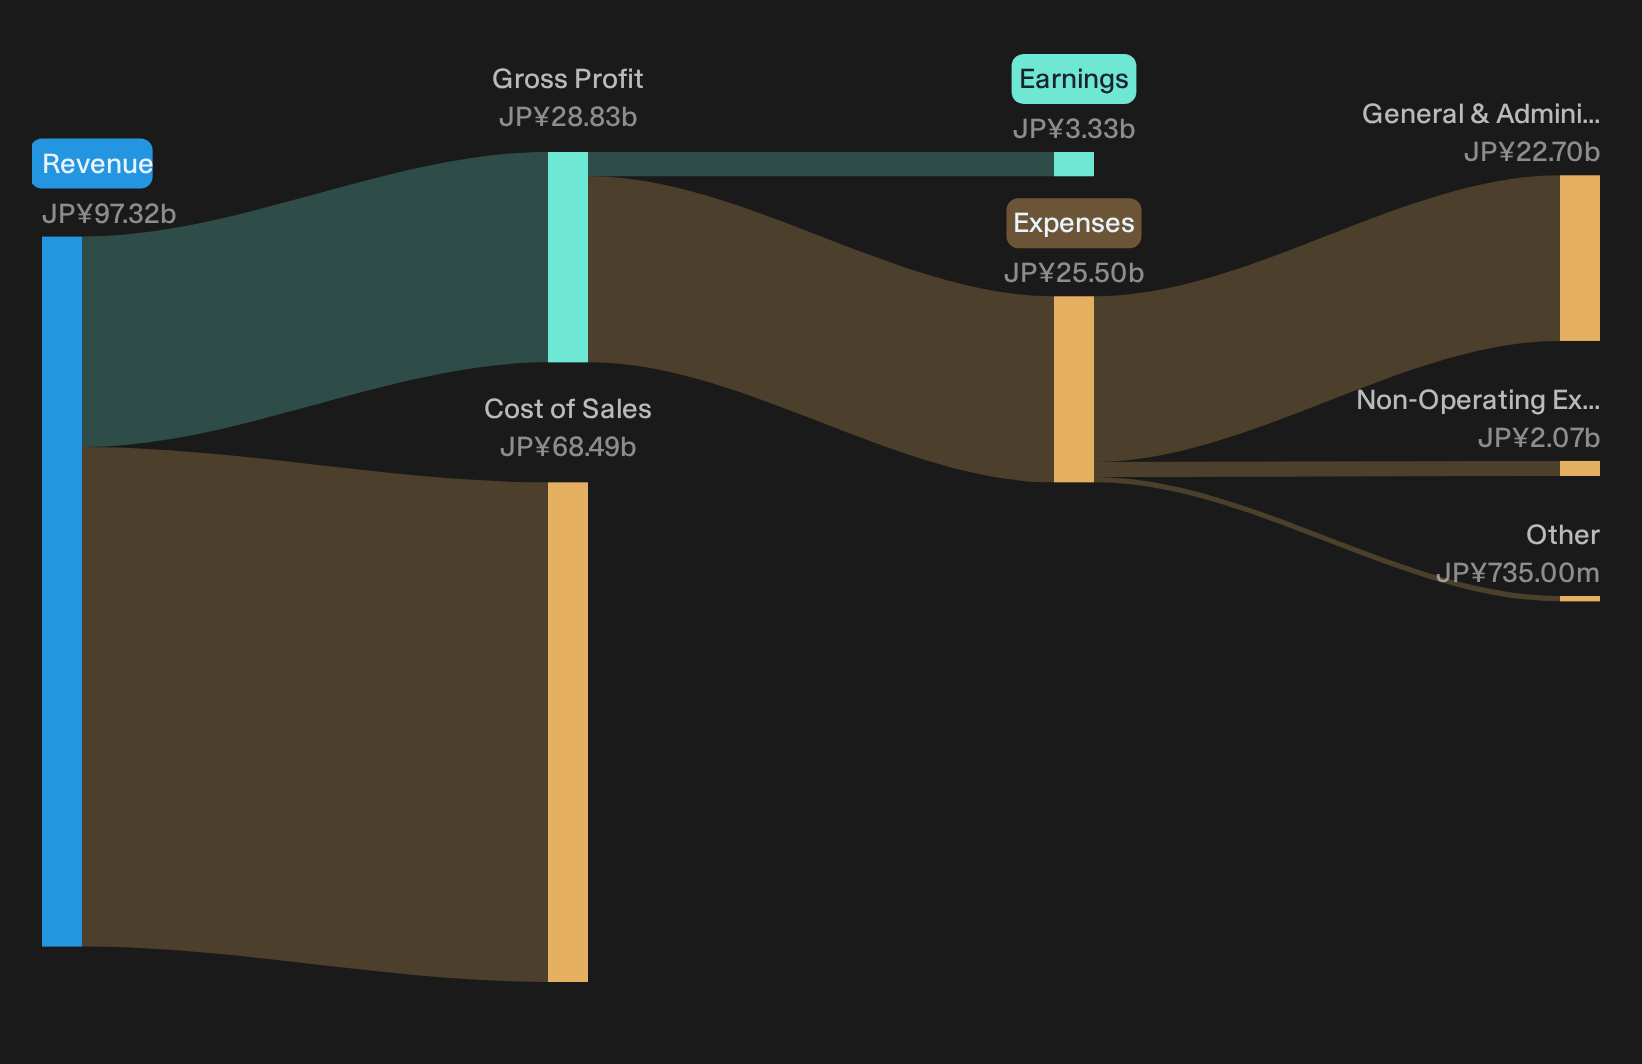
WakitaLTD: Revenue Momentum Versus Earnings Pressure
For a bullish angle on WakitaLTD, the key comfort is that the top line is still moving in the right direction. Revenue of ¥24,171 million in Q2 2027 sits above the ¥21,589 million level a year earlier, which suggests customers are still using the rental and trading platform. That helps the diversified infrastructure story. The snag is that this higher turnover did not translate into stronger earnings, so any constructive view relies on faith that the current earnings drag is temporary rather than structural.
Profit Compression Keeps WakitaLTD Bears Engaged
On the cautious side, WakitaLTD hands critics fresh material. Net income excluding extra items slipped from ¥552 million to ¥493 million and basic EPS moved from ¥11.16 to ¥9.91. The trailing 12 month net margin of 3.4% against 4.2% the prior year and commentary that a 5.58% dividend yield is not well covered both point to tighter cash generation. For investors worried about cyclical exposure in construction gear and real estate, these numbers support the argument that profitability is under pressure right now.
After a year of thinner margins and a dividend that is described as not well covered, it helps to ask if this is just surface-level strain or a sign of deeper structural issues. Review our full risk analysis for WakitaLTD which shows 1 important warning signOwn Your Next Investment Decision
Compressed margins, a rich P/E and a 5.58% yield that is described as not well covered make WakitaLTD a stock many investors prefer to monitor closely rather than rush into. Register for free with Simply Wall St and add it to your Watchlist to track price against fair value and watch how earnings and dividend coverage evolve before deciding on an entry point. After you build a position, keep your decisions grounded with the Portfolio Command Center that cuts through noise and highlights only the most important developments across all your holdings. Then round out your process by using the Community to see how other investors are thinking about stocks like WakitaLTD so you can spot potential catalysts or emerging risks early and stay ahead of the wider market.
Seeking Alternatives Beyond WakitaLTD?
Fresh opportunities move quickly as momentum builds, prices break out or quietly drop, and information loses its edge. Scan under the radar for now and get in early.
- Spot cash rich businesses that pair balance sheet strength with earnings resilience by reviewing the curated list of solid balance sheet and fundamentals stocks (23 results) before the crowd catches on.
- Hunt for income ideas that aim to keep yields flying while payouts stay supported by real cash flow through our hand picked 28 dividend fortresses while it matters.
- Target future facing infrastructure as power demand shifts by scanning carefully filtered 43 power grid technology and infrastructure stocks that could turn quiet grid upgrades into tomorrow's headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com