
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Great British Dividend Stocks To Own In October 2026
Rising government bond yields in Europe have pushed income seekers to rethink how they get paid. When cash rates feel uncertain and government debt looks riskier, predictable dividends from established UK companies start to look more appealing. That is where higher yielding, well covered and steadily growing dividend payers come in. This article highlights three British dividend stocks from our high income screen that aim to deliver steady cash payouts.
The three stocks covered below are just a small sample, and the full Dividend Powerhouses screen surfaces 59 more companies with yields above 3% and dividend profiles that aim to be just as compelling as the ones you are about to see.
If you want to identify income ideas that fit your own risk tolerance and payout preferences, head straight into the Dividend Powerhouses (3%+ Yield) screener to filter, analyze, and focus on the dividend plays that matter most to you.
Lloyds Banking Group (LSE:LLOY)
Overview: Lloyds Banking Group is a UK focused bank whose large retail arm uses current accounts, mortgages and savings to generate steady cash that funds dividends.
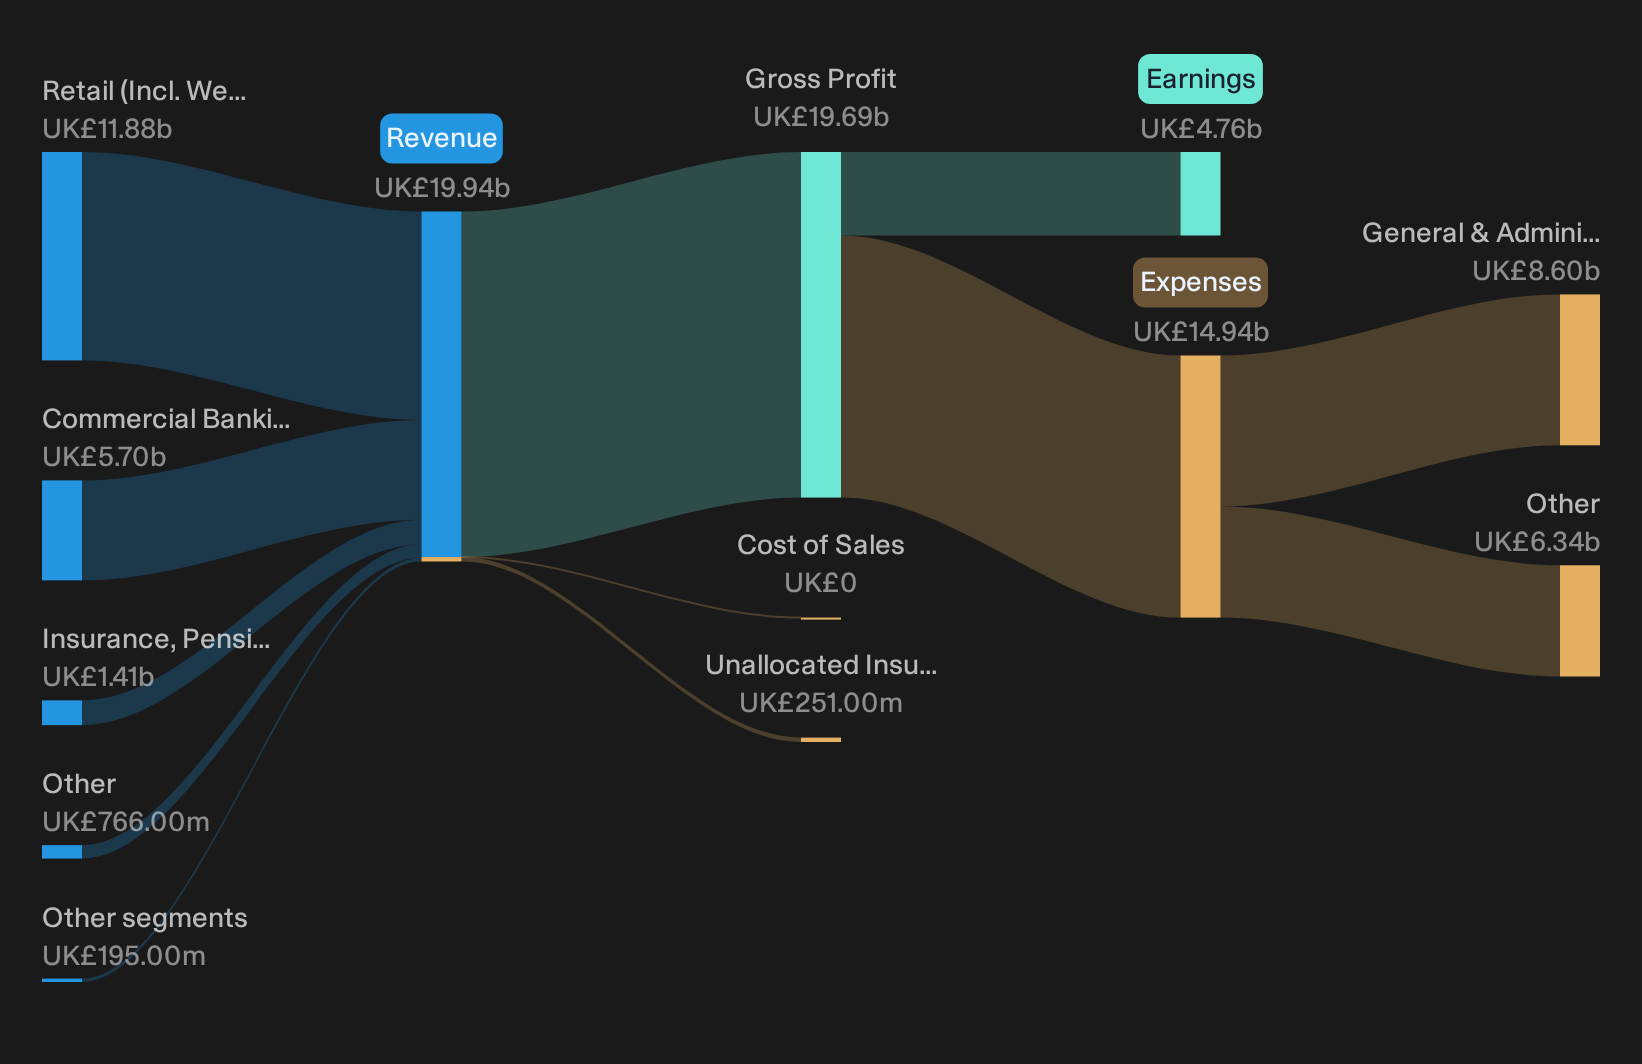
Operations: Lloyds Banking Group earns most of its income from Retail including Wealth at £11.9b, with Commercial Banking at £5.7b and Insurance, Pensions and Investments at £1.4b.
Market Cap: £58.2b
Lloyds Banking Group matters for this high yield screen because its everyday banking franchise generates the recurring cash flows that many income investors look for when assessing dividend strength.
"Lloyds Banking Group is moving into a new four year Accelerate 2030 plan that targets mid single digit net income growth, high single digit fee income growth and a cost income ratio below 45% by 2030."
What happens if a single cost saving lever does not deliver as hoped will go a long way to shaping future dividend flexibility.
If that cost flexibility is what you care about, read the full narrative for Lloyds Banking Group to see how Lloyds Banking Group’s plans could reshape dividend resilience and growth potential.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages yield focused infrastructure and private equity funds, especially renewable energy projects, that generate recurring fee income and support dividend payments.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, primarily across the United Kingdom and Australia.
Market Cap: £491 million
Foresight Group Holdings matters for this Dividend Powerhouses screen because its fee income from long term, cash generative infrastructure funds is built around serving investors who want steady, yield orientated distributions.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What happens if a single pressure on funding costs or regulation squeezes those cash flows will decide how dependable that income stream really feels.
When those pressures matter most, read the full narrative for Foresight Group Holdings to see how Foresight Group Holdings could turn fee strength into accelerating income resilience.

HSBC Holdings (LSE:HSBA)
Overview: HSBC Holdings is a global banking group whose UK and Hong Kong retail franchises supply steady interest and fee income that supports regular dividends.
Operations: HSBC generates about US$27.5b from Corporate & Institutional Banking, US$15.2b from Hong Kong, US$14.4b from International Wealth & Premier Banking, and US$12.6b from the UK.
Market Cap: £238.9b
Income focused investors often look at HSBC Holdings because its everyday retail and wealth activities in the UK and Hong Kong provide recurring cash flows that underpin the 3%+ yield goal of this Dividend Powerhouses screen, while the wider global network adds extra support behind those payouts.
"The bank is intensifying investment in Asian wealth management and private banking, leveraging a strong brand and local presence in fast-growing wealth markets like Hong Kong, mainland China, and Southeast Asia. This positions HSBC to focus on rising affluence and middle class expansion and may influence future fee income, earnings resilience, and margins."
Changes in Asia focused earnings could make a significant difference to future dividend comfort if new pressures emerge in those markets.
Those shifting earnings drivers are exactly what the full narrative for HSBC Holdings unpacks, highlighting where HSBC Holdings’ capital, fee streams, and risks could be quietly influencing shareholder income potential.

Curious About What You Might Be Missing Next
Fresh opportunities can move quickly while attention drifts to yesterday’s winners. Some ideas are still under the radar for now. Try not to be late to the move and consider acting while they remain less followed.
- Scan the list of solid balance sheet and fundamentals (9 results) curated by strict financial quality filters to find companies with cash rich balance sheets before they attract broader attention.
- Use the 91 robotics and automation stocks to review businesses involved in automation and factory upgrades that are connected to long term efficiency spending trends.
- Run the 43 power grid technology and infrastructure stocks to focus on companies tied to critical electricity infrastructure, including potential power grid upgrades and data demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com