
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Disco Shares Sales Surge Means For Shareholders
- Disco Corporation reported preliminary non consolidated sales for the quarter ended September 2026 of ¥118.5b compared with ¥85.3b a year earlier, and first half sales of ¥213.6b compared with ¥160.8b.
- The sharp step up in Disco Corporation’s quarterly and half year sales points to strong demand for its core products. A recent analyst upgrade mainly reflects this improved operating backdrop rather than driving it.
- We will now explore how Disco Corporation's stronger reported sales trajectory could influence its broader investment narrative for shareholders.
What Is Disco's Investment Narrative?
To own Disco, you need to buy into a story of precision equipment that still commands healthy demand, even as cycles swing. The fresh sales figures hint at strong orders for cutting, grinding and polishing tools, plus related services, and they come on top of earnings that grew 17.8% over the past year with net profit margins around 31.6%. That kind of profitability, paired with a high 25.1% return on equity, suggests execution and pricing power are both central to the thesis.
In the short term, the sales update and recent earnings estimate upgrades mainly tighten the focus on whether this tempo can be sustained against heavy capital needs and an already rich P/E of 45.7x, which screens as expensive both versus the industry and some fair value models. The stock has also been volatile over the last three months and has lagged the wider JP semiconductor sector over a year, reminding you that strong fundamentals do not always translate cleanly into smooth returns.
That said, the picture changes once you weigh one specific pressure point that sits awkwardly alongside Disco's strong sales print and high margins...
There's only one way to know the right time to buy, sell or hold Disco. Head to Simply Wall St's company report for the latest analysis of Disco's Fair Value.
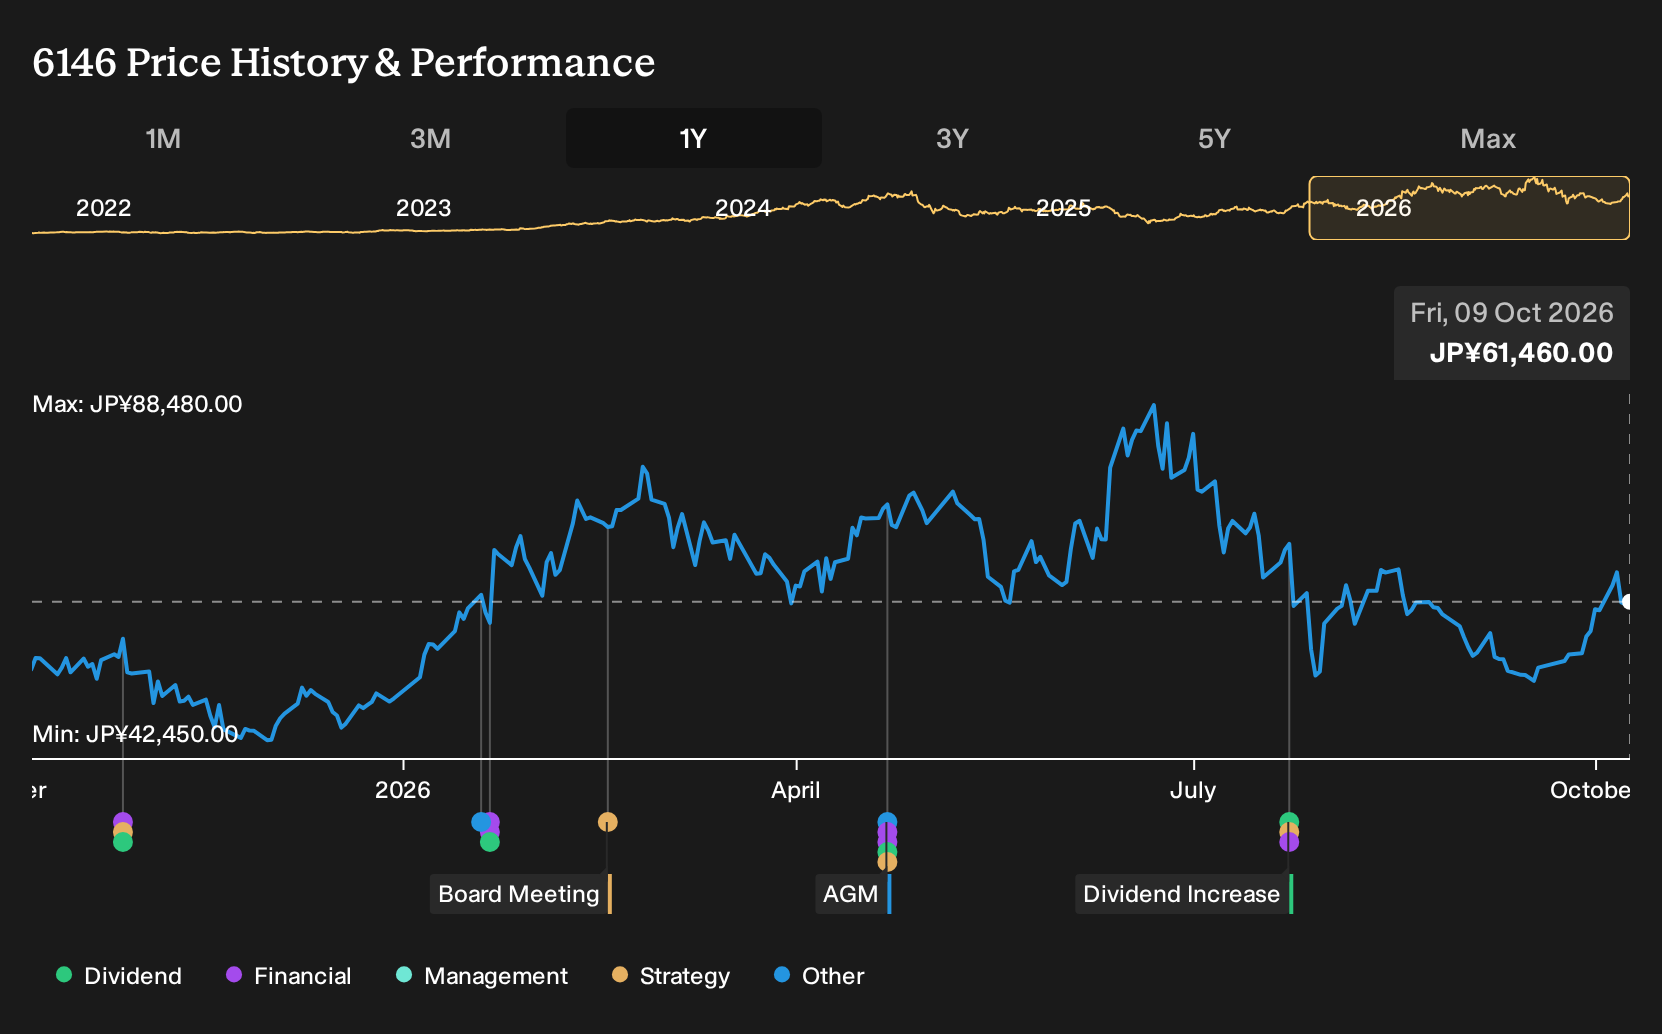
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community already sit far apart, ranging from about ¥25,159 to ¥81,575 per share. This shows how differently private investors are sizing up Disco Corporation. These figures pre date the latest sales update, so you may want to weigh fresh revenue momentum against your own expectations for future orders.
Explore another Disco fair value estimate, including one that suggests as much as 59% downside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Disco research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Disco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Disco's overall financial health at a glance.
Looking For More Ideas Beyond Disco?
If Disco has sharpened your focus on quality and pricing power, it can help to line it up against a broader watchlist. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is resilience, income, or overlooked potential.
- If you want companies that already combine strong finances with muted risk scores, start with a set of 23 resilient stocks with low risk scores and see which ones match your comfort zone.
- If value is your priority, broaden your horizon with a curated group of 12 high quality undervalued stocks that pair solid balance sheets with cash flow support.
- If you prefer businesses that are off most investors' radar, scan through a targeted pool of 74 high quality undiscovered gems that could be building their own upgrade stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com