
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Guidewire Software's Fall Catch You Out? What Investors Missed
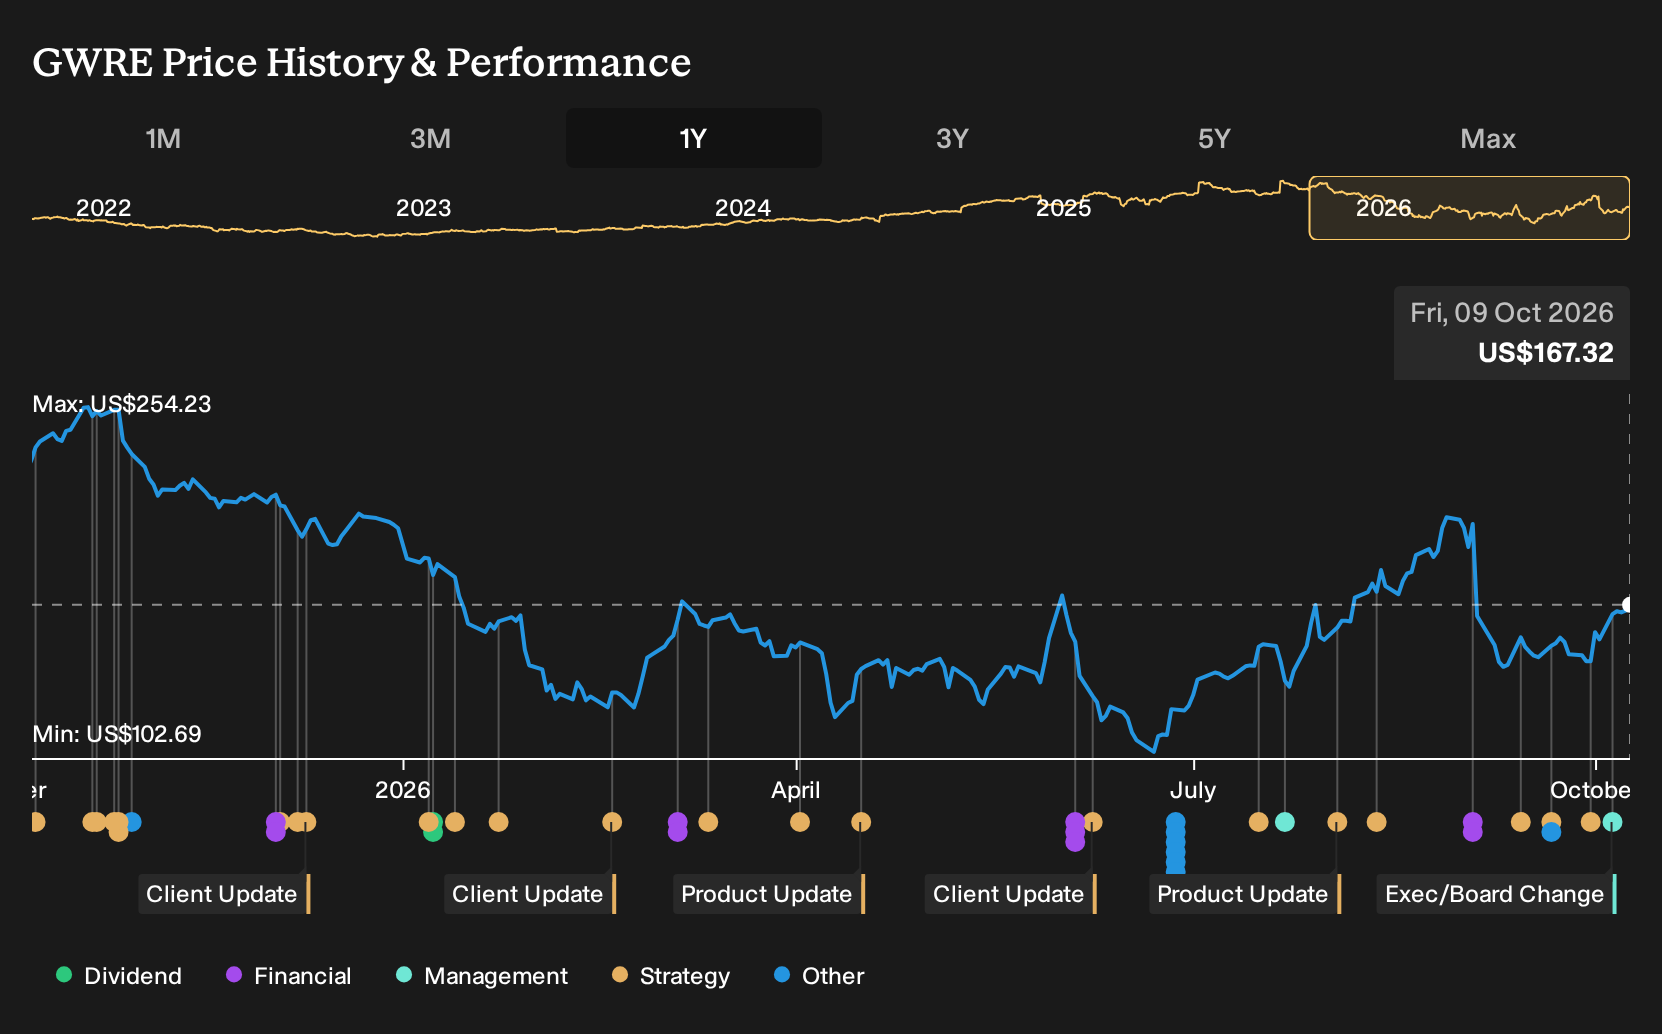
Guidewire Software’s latest headline was rough. A strong Q4 2026 revenue print of US$411.1 million and 19% ARR growth landed next to softer margins and a weaker than hoped fiscal 2027 outlook, and the stock dropped sharply on the day. Investors who held Guidewire Software over the past year are down 30.0%, including dividends. If you had bought on 9 October 2025, how much of that result came from risks that were already visible?
This theme extends beyond Guidewire Software. See which of 36 AI small caps may still merit a closer look.
The Two Futures Guidewire Investors Had To Price In
The shares cost US$237 at the start of the period, and anyone looking at Guidewire Software then had to choose which story felt more convincing.
The bullish view argued that accelerating cloud migration and AI justified a Fair Value of US$268. This was a rough guide to what that scenario implied the shares were worth if revenue grew 15.6% and profit margin reached 9.5% over three years.
The bearish view pointed to rising cyber security, GDPR and compliance costs and put Fair Value at US$155, with concern that higher spending would squeeze future margins and weaken pricing power.
What The Results Changed For Guidewire Software
Guidewire Software logged Q4 2026 revenue of US$411.1 million compared with US$356.6 million a year earlier, and management kept pointing to cloud and AI demand in Q3 and Q4. That reflected the growth side of the bullish case. Profit told a different story. Net income slipped from US$52.0 million to US$31.4 million and net margin moved from 14.6% to 7.6%, which aligned with a cautious view on pressure to sustain profitability.
The key issue here was not whether Guidewire could win cloud and AI business. It was whether higher security, compliance, and delivery costs would affect earnings. When assessing another software stock, consider that same tension by pairing ARR or subscription growth with net margin in each set of results rather than looking at revenue alone.
What You Would Be Paying For In Guidewire Software Today
Guidewire Software now changes hands at about US$167, with the one year return down 30.0% from US$237. The selected Narrative’s Fair Value sits above the current price based on its own assumptions rather than any proven reality.
That view leans on contract visibility and low ARR churn as the real draw. For the Narrative’s higher figure to work, a buyer today would need to assume insurers keep signing longer Guidewire Cloud and AI contracts that lift recurring earnings power.
"Gross ARR attrition of less than 1.5% overall and under 1% for core systems customers at over US$1b of ARR supports Guidewire Software offering additional product modules into an unusually stable base, which can lift average revenue per customer and long term subscription revenue."
One Narrative disagrees with today's price. → See where this Narrative says Guidewire Software should trade
Looking Beyond Guidewire Software
Guidewire Software shows how complex, regulated clients approach long software contracts with demanding expectations.
Those sticky relationships sit beside strict requirements for data visibility, controls and governance.
Governments, health systems, utilities and banks face similar pressures as they adopt AI.
Another provider focuses on that operational layer, embedding AI into daily workflows with security, compliance checks and audit trails.
As more critical institutions depend on those capabilities, the company’s role can evolve toward core infrastructure for how sensitive sectors manage data and AI in practice.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 73% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com