
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Outlook Might Change The Case For Investing In Williams Sonoma Stock
- Pottery Barn, part of Williams-Sonoma, previously launched an exclusive Big Daddy’s Antiques collection featuring furniture, lighting, decor, and entertaining pieces available online and in select stores.
- The partnership reflects Pottery Barn’s emphasis on curated, story-driven design that can deepen customer engagement and support Williams-Sonoma’s premium positioning across its home portfolio.
- This analysis reviews how Williams-Sonoma’s investment narrative relates to the Big Daddy’s Antiques collaboration and current earnings expectations.
Scan how Williams-Sonoma’s premium home story compares with other quality retailers by sizing up our hand-picked 28 high quality undervalued stocks that pair strong fundamentals with more modest expectations.
Williams-Sonoma Investment Narrative Recap
To own Williams-Sonoma, you need to buy into a premium home retailer that leans on design, brand strength, and disciplined execution rather than rapid expansion. The near term swing factor is how well demand for higher ticket furnishings holds up as housing activity and interest rates weigh on big purchases. The Big Daddy’s Antiques launch is directionally consistent with that focus but likely not a stand alone catalyst.
The bigger operational risk right now sits in tariffs, sourcing costs, and any prolonged softness in big home projects that could pressure revenue and margins at the same time. Store investments and inventory decisions add another layer of execution risk if traffic slows faster than planned.
The Big Daddy’s Antiques for Pottery Barn collection is the most relevant update here because it leans directly into Williams-Sonoma’s push for differentiated, exclusive assortments across its brands. That kind of curated story can help justify premium pricing and support conversion, both online and in stores, if customers keep responding to design led ranges.
For you as a shareholder, the interest is how this type of partnership feeds into existing catalysts like AI supported digital platforms, B2B channels, and supply chain work. If collaborations like this deepen loyalty without creating excess inventory or discounting risk, they can quietly support earnings quality while the larger macro and tariff questions play out.
Williams-Sonoma's current analyst narrative points to revenues of US$9.4b and earnings of US$1.3b by 2029, based on a 5.4% yearly revenue growth rate. This implies earnings today of about US$1.2b and an earnings increase of roughly US$0.1b by the 2029 forecast year.
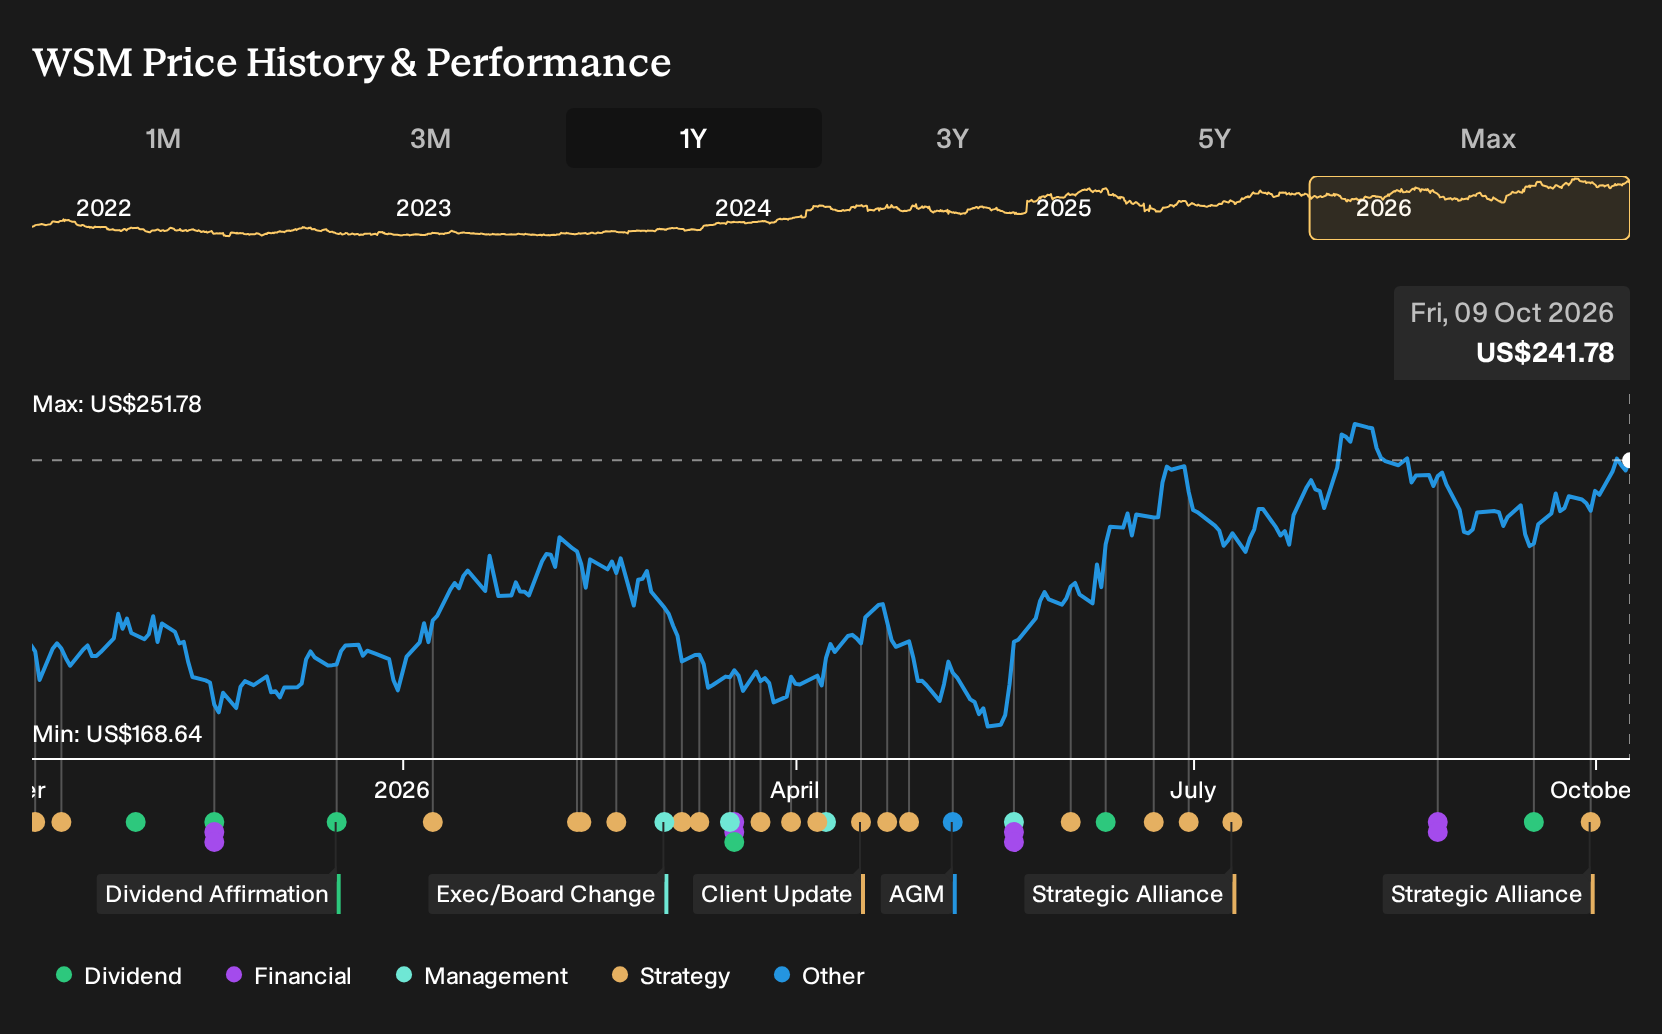
Uncover why Williams-Sonoma's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Williams-Sonoma’s B2B and emerging brand expansion rather than tariff risk, arguing these channels could support around US$9.6b of revenue and US$1.4b of earnings by 2029, versus the baseline US$9.4b and US$1.3b. Those views were set before this Big Daddy’s Antiques collaboration, so expectations may shift as reactions roll in.
Explore 2 other Williams-Sonoma fair value estimates, including one that suggests it could be worth as much as $250.99.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Williams-Sonoma research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Williams-Sonoma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Williams-Sonoma's overall financial health at a glance.
Looking for more investment ideas beyond Williams-Sonoma?
If the Williams-Sonoma story has you thinking about where else disciplined execution and solid fundamentals might show up, broaden your watchlist with a few focused stock sets built around different risk and return profiles.
- For investors who care most about robust cash generation and restrained valuations, scan a curated 28 high quality undervalued stocks that lean on strong business quality and more measured expectations.
- If income reliability matters to your plan, check out a group of 8 dividend fortresses that aim to combine higher yields with balance sheet resilience.
- When capital preservation sits near the top of your priority list, start with a hand picked 31 resilient stocks with low risk scores that score well on financial strength and downside risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com