
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hut 8 (HUT) Could Be 46% Undervalued As $1.07b Credit Facility Expands Flexibility
Hut 8 (HUT) just closed a four year, US$1.07b senior secured revolving credit facility, a financing move that reshapes its liquidity profile and gives the business more room to fund large infrastructure projects.
Hut 8’s latest credit facility lands after a choppy spell for the stock, with the share price falling 12.15% over the past 30 days and 17.56% over 90 days, yet still recording a 64.37% year to date share price return and a 93.41% total shareholder return over the past year. This pattern points to strong longer term momentum despite recent pullbacks and shifting views on its risk profile as it ramps up large AI data center projects.
Spot emerging peers building similar AI and power infrastructure by scanning our curated list of 92 AI infrastructure stocks.Fresh liquidity, a sharp pullback and a stock still up strongly over 12 months put Hut 8 in an awkward spot. Does that add up to a reasonable entry today, or a setup to wait for cheaper terms?
Most Popular Narrative: 46% Undervalued
Hut 8 closed at $84.27, while the most followed narrative pegs fair value at $157.09. This comparison frames the fresh credit line and AI buildout against a much higher long term potential in the model.
The Power First strategy, featuring sizable pipeline origination (10.8 GW under diligence, 3.1 GW under exclusivity) and dual-purpose sites for both Bitcoin mining and AI compute, provides scalability and flexibility to benefit from rising institutional adoption of digital assets and accelerating demand for clean energy-powered blockchain infrastructure, bolstering future revenue and earnings growth.
See why 82 investors see Hut 8 as 46% undervalued.
Result: Fair Value of $157.09 (UNDERVALUED)
Still, Hut 8’s reliance on Bitcoin pricing and capital heavy AI and data center builds means regulatory shifts or project setbacks could quickly challenge that undervalued narrative.
Find out about the key risks to this Hut 8 narrative.
Another View: Hut 8 Looks Expensive On Sales
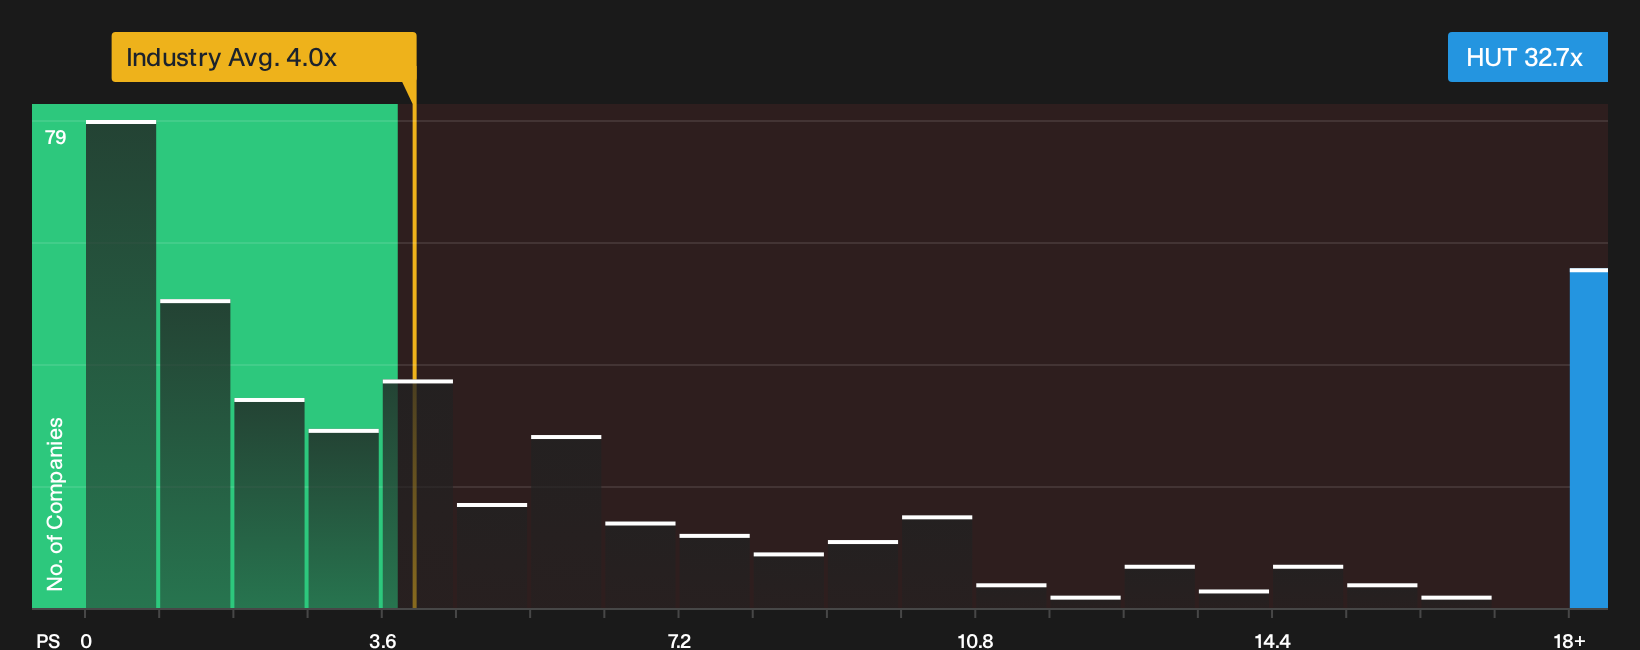
The narrative model points to Hut 8 as undervalued, yet the market price tells a very different story when set against revenue. On a P/S of 32.7x, the stock trades at a very large premium to both peers at 1.5x and the US Software group at 4x. It also sits far above the fair ratio of 13.3x. That gap suggests investors are already paying up heavily for future AI and power projects, so the key question is whether your own expectations justify such a rich entry point.
To see how this lofty sales multiple stacks up against the underlying numbers and alternatives, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If you are conflicted about whether Hut 8’s mix of fresh credit and rich multiples points to opportunity or risk, and are keen to move before the story shifts again, you should pressure test the current setup against independent data on both sides of the ledger through 1 key reward and 3 important warning signs.
Looking for more ideas beyond Hut 8?
If Hut 8 has your attention but you want a wider hunting ground, line up a few fresh targets using the Simply Wall Street Screener before the next move hits.
- Target resilient compounding potential by filtering for companies with strong fundamentals and low volatility through the 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning the 28 high quality undervalued stocks that combine solid financials with prices below estimated fair value.
- Build a sturdier core in your portfolio by reviewing the list of solid balance sheet and fundamentals (25 results) that can better handle shocks and funding needs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com