
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To BBVA Shares After Earnings Estimate Upgrade And Interim Dividend
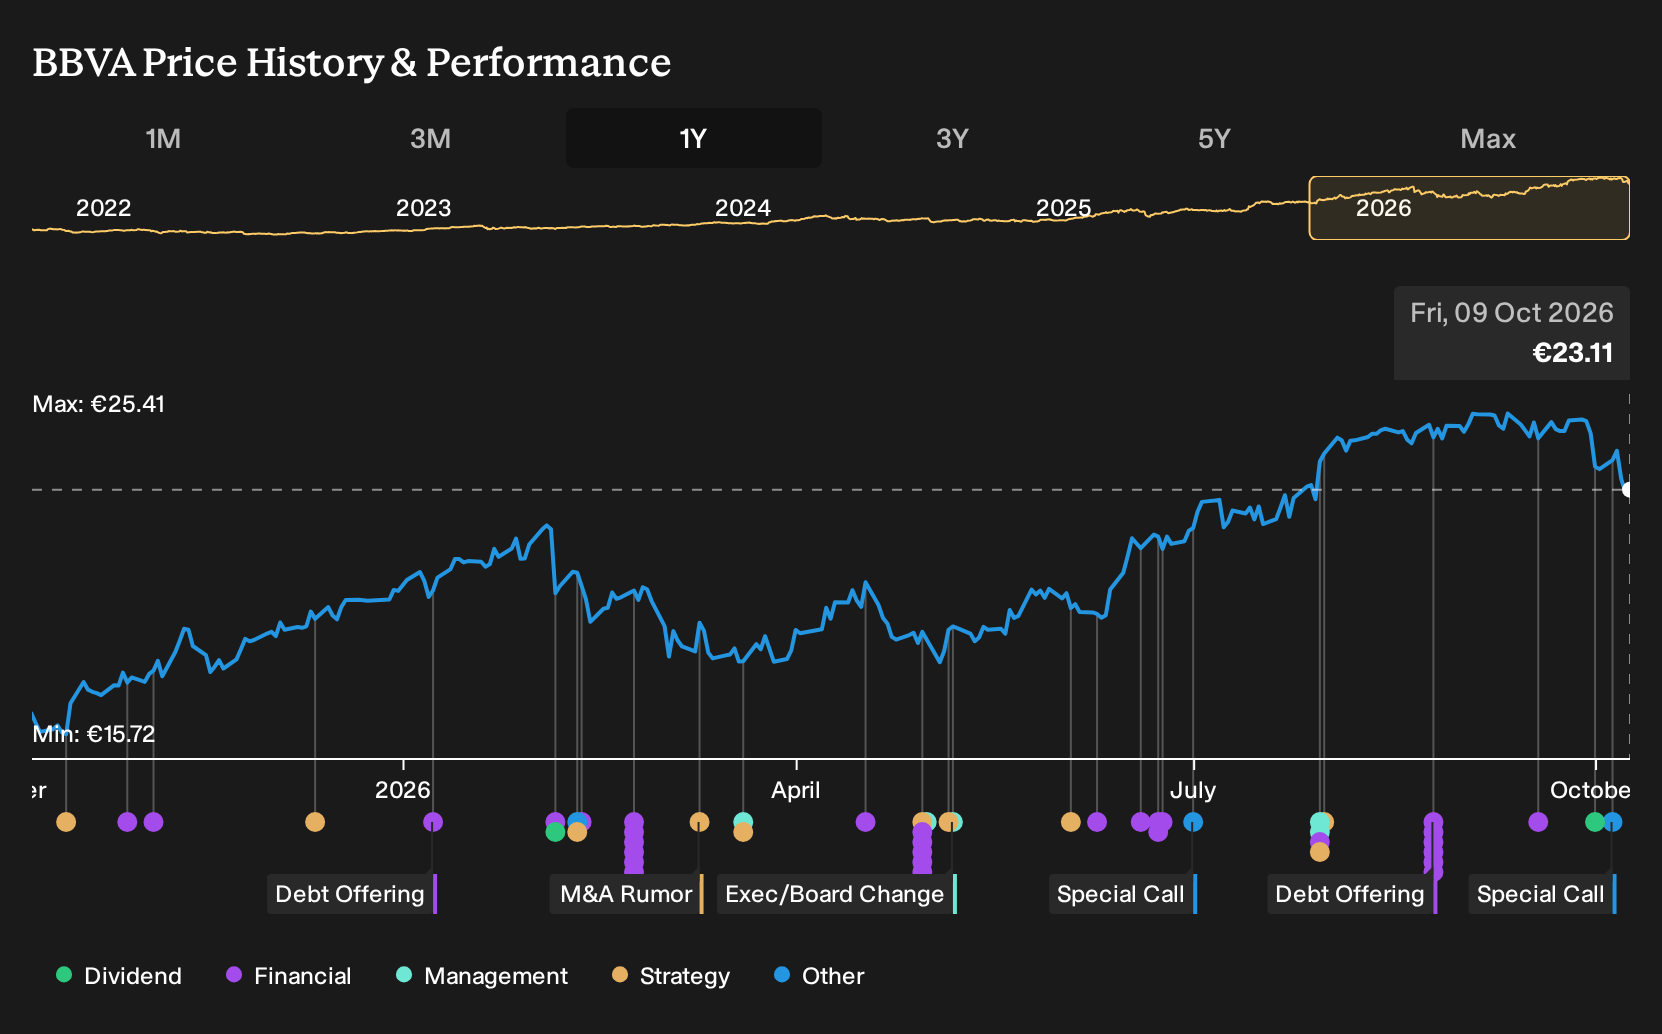
- BBVA has already paid an interim cash dividend of €0.37 gross per share in October 2026 and hosted a special call on its AI transformation and IT strategy in Spain, highlighting a mix of capital returns and technology focus.
- The combination of a defined dividend payout schedule and management attention on AI driven efficiency reflects how BBVA is trying to balance income appeal with long term cost discipline.
- The following section considers how BBVA's investment narrative could be influenced by the recent interim dividend decision and its AI focused strategy update.
Banco Bilbao Vizcaya Argentaria Investment Narrative Recap
To own Banco Bilbao Vizcaya Argentaria, you need to be comfortable with a bank that leans heavily on emerging markets while trying to keep costs tight through digital and AI tools. The short term swing factor is still basic banking earnings, especially net interest income in Spain and Mexico, not the tech messaging.
The biggest near term risk sits in those same emerging markets. Political shifts, inflation or weaker currencies in Mexico, Turkey or South America could pressure credit quality and margins. Execution on AI and digital projects could also disappoint, although the recent communication alone does not materially change those risks.
The interim dividend of €0.37 per share is the clearest tangible signal from BBVA right now. It reinforces the story that the bank wants to pair AI driven efficiency efforts with ongoing cash returns, even with a historically less stable dividend pattern and a relatively high level of bad loans at 2.8%.
For you as a shareholder, that payout can be seen alongside BBVA’s push on technology as a test of management discipline. Sustaining distributions while investing in AI and IT could support the existing earnings profile if execution stays on track, but any deterioration in asset quality or regulatory pressure on capital would quickly move to the foreground.
What The BBVA Consensus Numbers Are Really Saying
Banco Bilbao Vizcaya Argentaria's current analyst framework leans heavily on a specific set of assumptions about how the bank grows and what it earns over the next few years. The picture is built around revenue expanding at 12.3% a year, a step down in profit margins from 31.4% today to 25.6% by 2029, and earnings that move from €10.7b now to a consensus of €12.4b. Some forecasters go further and pencil in up to €16.3b of profit, but the central case is more restrained and feeds into the valuation debate.
That shift from €10.7b to €12.4b implies an earnings rise of about €1.7b by 2029, so the forecast earnings line is not flat but it is also not explosive. Analysts tie those numbers to a target P/E of 14.2x on the 2029 earnings figure, compared with a current multiple of 12.7x and a US banks sector level of 14.0x. For you as an investor, the key question is whether it feels reasonable that BBVA could support that slightly higher multiple while operating with lower margins and higher absolute profit.
The revenue side of the model is also explicit. To meet the consensus view, BBVA would be generating €48.4b of revenue and €12.4b of earnings by 2029. That outcome rests on the 12.3% yearly top line growth assumption and on the idea that the bank can carry higher credit costs, a slimmer margin percentage and still convert more of a larger revenue base into profit. The gradual growth in share count of 0.38% per year over the next 3 years is small in the context of those moves, but it still matters for per share outcomes.
Banco Bilbao Vizcaya Argentaria's valuation link to those forecasts is clear in the current price versus target range. With the stock at €24.81 and the consensus target at €23.5, the average analyst view is only 5.6% lower than where the shares trade today. Some expect a much higher outcome at €28.3, while others sit closer to €11.7, which shows how wide opinion is beneath the surface. For a retail holder, the practical takeaway is that the market is already pricing in a fair chunk of the published growth and AI efficiency story, so any change in earnings expectations or perceived risk can shift that balance quickly.
Banco Bilbao Vizcaya Argentaria is also being valued with a discount rate assumption of around 8.5% in the consensus model, which shapes what those future cash flows look like in today's terms. A higher required return would make the same 2029 earnings and revenue worth less now. A lower one would do the opposite. That is why you should treat the discount rate as one of the moving parts rather than a fixed truth and stress test how comfortable you are with that 8.5% hurdle in the context of BBVA's exposure to Mexico, Turkey and South America.
Banco Bilbao Vizcaya Argentaria's narrative projects €48.4b revenue and €12.4b earnings by 2029. This rests on 12.3% yearly revenue growth and an earnings increase of about €1.7b from €10.7b today.
Uncover why Banco Bilbao Vizcaya Argentaria's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate view puts fintech disruption front and center for BBVA. The most bearish analysts were penciling in about €47.8b of revenue and €11.4b of earnings by 2029, with a much lower 10.7x P/E. You can read that as a far more cautious story that the new dividend and AI update could yet reshape.
Explore 3 other Banco Bilbao Vizcaya Argentaria fair value estimates, including one that suggests as much as 29% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Banco Bilbao Vizcaya Argentaria research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Bilbao Vizcaya Argentaria. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Banco Bilbao Vizcaya Argentaria's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banco Bilbao Vizcaya Argentaria?
If the Banco Bilbao Vizcaya Argentaria narrative has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other opportunities that align with your income, quality or risk preferences.
- For investors who want sturdier balance sheets to sit alongside higher risk positions, consider screening for companies using our list of solid balance sheet and fundamentals (204 results) as a starting universe for further research.
- If your priority is steady income potential, you can focus on businesses with stronger yields and payment track records by filtering through our 223 dividend fortresses and then drilling into the fundamentals that matter most to you.
- Those who care most about valuation and quality together can narrow the field to companies that combine cash flow strength with more conservative pricing by starting with our 174 high quality undervalued stocks and layering on your own criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com