
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Infrastructure Stocks Retail Investors Are Watching As Chip Demand Surges
AI infrastructure is pulling in huge amounts of capital right now, with US semiconductor imports at US$90.5b for the first eight months of 2026 and AI focused hardware helping push capital goods imports tied to chips, computers and accessories up 66% year over year. That kind of demand shock can reshape winners and laggards. This article walks through three stocks exposed to that news and how investors might think about them.
The three stocks covered below are just a sample, and the full screen surfaced 61 more AI infrastructure and semiconductor suppliers with equally compelling stories that are not covered here. If you want to quickly identify and analyze the highest conviction plays tied to this theme, head straight into the AI Infrastructure and Semiconductor Suppliers screener.
ASM International (ENXTAM:ASM)
ASM International sits right on the fault line where AI data center demand turns into real world chipmaking capacity. Its tools are used at the advanced nodes hyperscalers need for cutting edge GPUs and accelerators, which is why its role in this theme matters.
"The ramp up of advanced logic nodes such as 2nm and 1.4nm for AI and high performance computing workloads continues to raise ALD and epitaxy layer counts. ASM International links this to a larger served market, which supports the prospect of revenue growth that the market may not yet fully reflect in the current valuation."
What happens to ASM International’s earnings power if a single key assumption about how quickly that extra layer demand feeds through to pricing breaks?
ASM International develops wafer processing tools and related services that chip manufacturers use to build advanced semiconductors. It generated €3.36b from semiconductor equipment and services, with a market value of about €43.28b, which puts it firmly in the large cap end of this AI infrastructure theme.
If that assumption looks fragile to you, read the full narrative for ASM International to see how ASM International’s pricing power, capacity cycles and AI exposure could be decoupling.

Comet Holding (SWX:COTN)
Comet Holding plugs directly into the AI infrastructure buildout with RF power gear that helps run plasma tools for chipmaking and X-ray technology that checks those advanced wafers and components before they ever reach an AI data center.
Comet Holding focuses on RF power and X-ray technologies tied to semiconductor manufacturing, with its Plasma Control Technologies arm generating about CHF266 million, X-Ray Systems around CHF111 million, and Industrial X-Ray Modules roughly CHF104 million, supporting a business valued near CHF2.8b by market cap.
"Expanding end-markets, innovation leadership, and strategic growth in Asia position Comet for long-term revenue stability, premium margins, and greater exposure to recurring high-value opportunities."
What happens to that margin story if one pressure point inside the semiconductor equipment cycle tightens more than management expects?
If that squeeze risk sits at the back of your mind, read the full narrative for Comet Holding to see whether cyclical noise is masking a stronger long term opportunity.
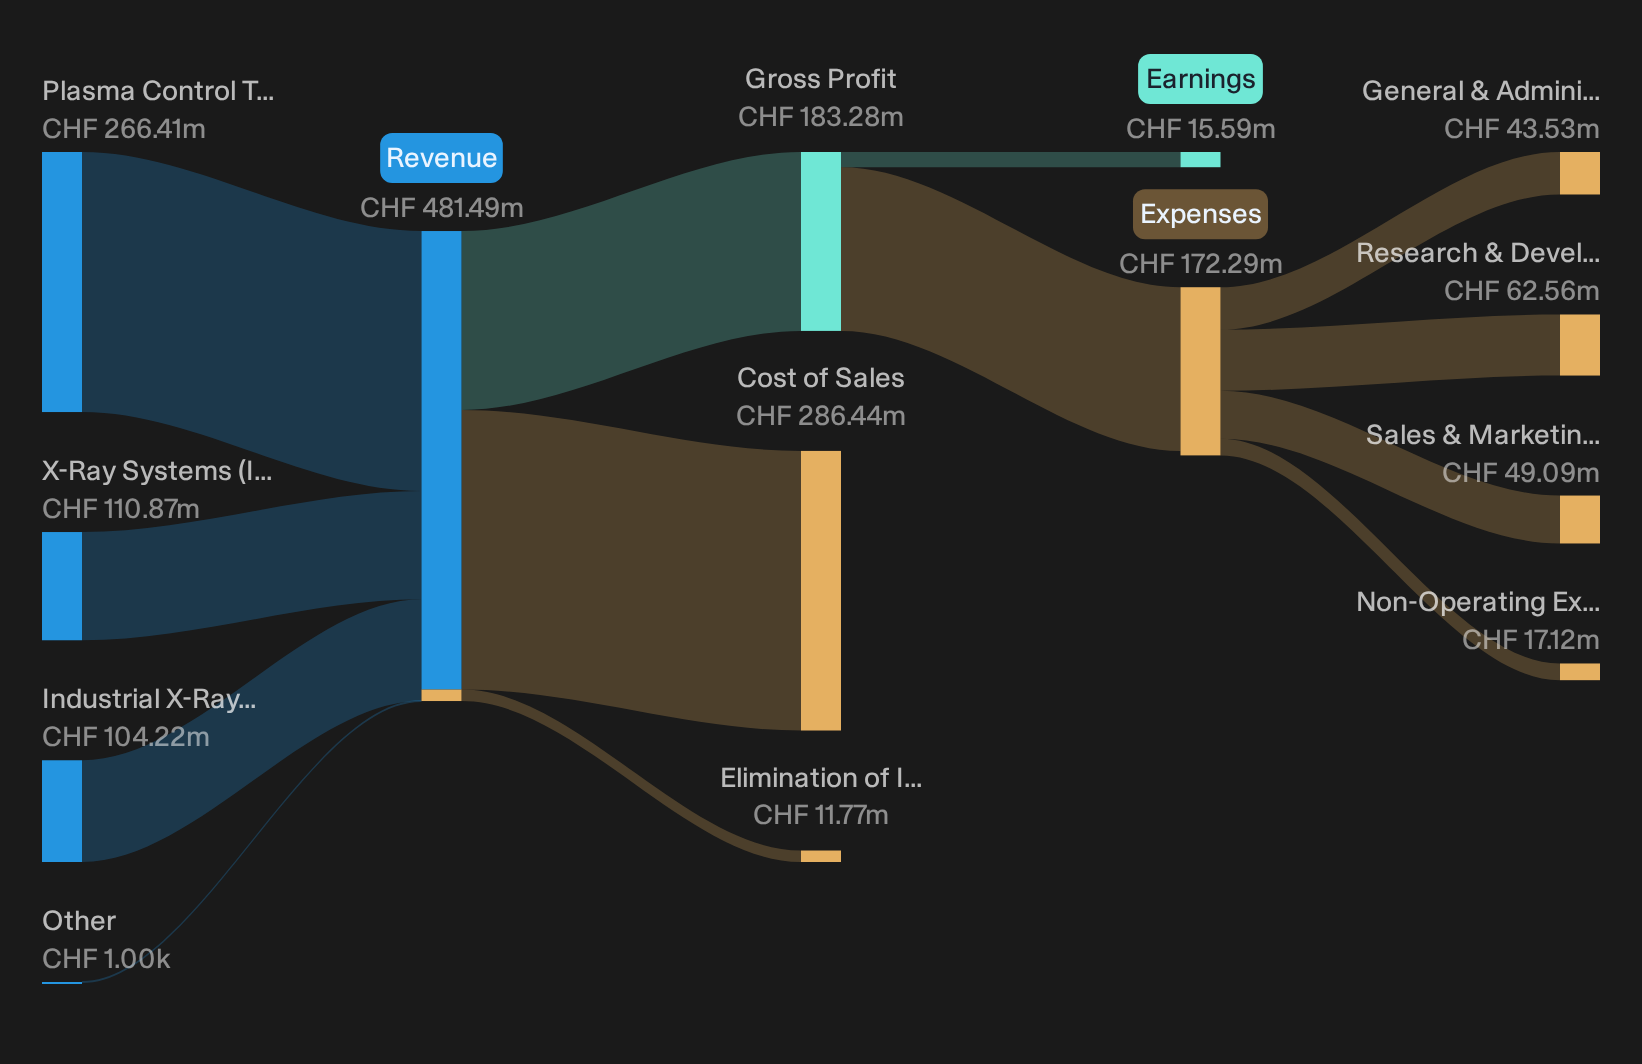
Advanced Energy Industries (AEIS)
Advanced Energy Industries sits right in the power circuitry of the AI infrastructure story, supplying the precision conversion gear that keeps wafer tools and power hungry data centers running smoothly. This is exactly where rising semiconductor and AI capex is being directed.
"Data Center Computing outlook: At least 50% growth, raised from mid-30%. One number in the quarter can trip the breaker if you're not careful: GAAP earnings absorbed roughly $0.75 per diluted share from an inducement expense tied to converting the company's 2028 notes."
Whether that headline growth turns into durable value depends on how one unseen pressure on profitability and cash generation ultimately resolves.
That pressure point is exactly where full narrative for Advanced Energy Industries shows how Advanced Energy Industries could turn inducement costs into accelerating AI power leverage that markets may still be underpricing.

Seeking Fresh Alternatives Before They Fly
New themes break out while old favorites stall, and the best entries often appear quietly then vanish fast. Scan these curated ideas before the crowd catches up and get in early.
- Hunt for smaller companies with sharper balance sheets using the curated list of solid balance sheet and fundamentals (204 results) that keeps financial strength front and center while prices still look reasonable.
- Track income opportunities that might hold up when sentiment swings by zeroing in on a hand picked group of 223 dividend fortresses built for staying power.
- Ride the momentum of real-world infrastructure as capital shifts toward electrification and grid upgrades with a focused set of 43 power grid technology and infrastructure stocks before they get fully priced in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com