
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Western Digital (WDC) Faces Rising Earnings Expectations, Is The AI Storage Story Fully Valued?
Rising expectations around Western Digital (WDC) ahead of its October 22 earnings release have turned the stock into a focal point for investors watching data center and enterprise storage demand.
Western Digital’s recent share price has cooled off, with the stock down 17.62% over the past 30 days and 31.81% over 90 days, even after a strong year to date share price return of 111.66%. The 1 year total shareholder return of 244.85% and very large 3 and 5 year total shareholder returns hint at momentum built over a longer arc as investors reassess both growth potential and earnings risk ahead of the October 22 update.
Spot 92 AI infrastructure stocks that echo Western Digital’s data center and AI storage story so you are not relying on a single hardware supplier ahead of earnings.Bulls point to Western Digital’s AI storage role and rich free cash flow story. Bears focus on the sharp pullback and cyclic hardware risk. Which case does the current valuation actually lean toward?
Most Popular Narrative: 20.5% Overvalued
Western Digital closed at $397.28, while the most followed narrative anchors fair value closer to $329.76, which frames today’s AI story as generous on price and rich on expectations.
So what could pull the water line down? Three things, and they all rhyme with cycles past. First, capacity. The whole thesis rests on the duopoly holding the line. The moment either player, or a cash-rich new entrant, decides to chase this demand with new plants, the shortage becomes a glut, as it always has in memory and storage. Second, the AI capex cycle itself. Sold-out order books are wonderful right up until the buildout matures and the hyperscalers digest what they already bought. Third, and further out, China. Chinese memory makers such as YMTC are expanding NAND capacity, and while that is flash rather than hard drives, it pressures the entire storage complex and sharpens the eternal question of when solid state becomes cheap enough to eat into the capacity tier.
See why 37 investors see Western Digital as 20% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital’s story can change quickly if data center customers pause AI spending or if new HDD or flash capacity begins to erode pricing power.
Find out about the key risks to this Western Digital narrative.
Another View: Western Digital Through The P/E Lens
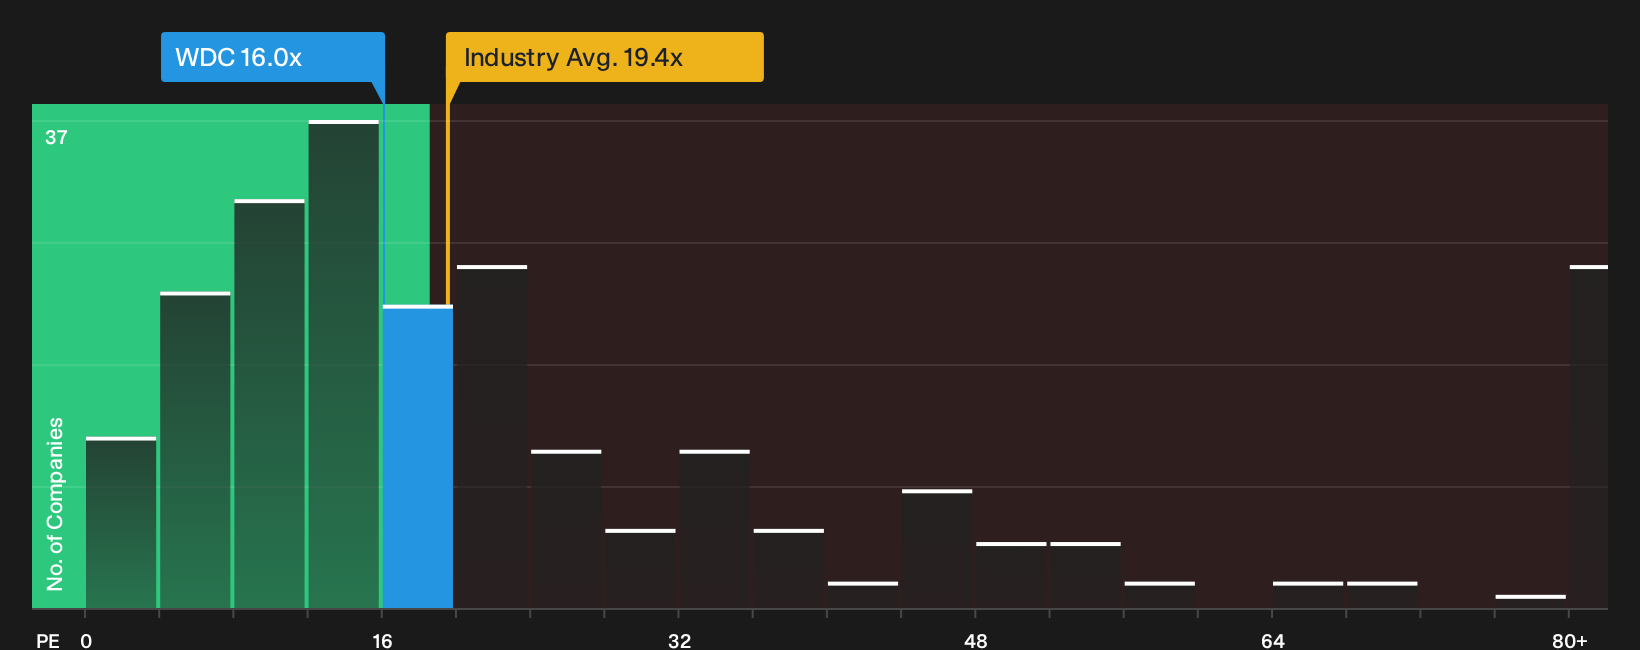
DCF purists call Western Digital significantly undervalued, yet the simple P/E story is far more measured. WDC trades on 16x earnings, compared with 19.4x for the global tech sector and 36.3x for close peers, while the fair ratio points to 46.4x. Is the discount a cushion, or a warning that the earnings base is unusually elevated?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through the crosscurrents around Western Digital and still unsure which side you land on? Move quickly, review the data for yourself, and weigh 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Western Digital?
If Western Digital has your attention, do not stop there. Broaden your watchlist now so you are not late to the next setup.
- Target resilient upside by scanning a 31 resilient stocks with low risk scores that filters for companies with steadier risk scores when markets start to feel choppy.
- Hunt for quality on sale by reviewing a 28 high quality undervalued stocks that blends solid balance sheets with compelling valuations.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems that highlights under-the-radar businesses before attention fully lands on them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com