
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Founder Led Stocks With Earnings Growth Up To 20%
Governments in rich countries are now wrestling with rising debt costs, and the IMF is shifting its focus toward these pressures. When money is expensive and public finances look stretched, investors often pay closer attention to businesses where the founder is still in charge and deeply invested in the outcome. This article highlights three founder-led United Kingdom stocks that fit that bill and explains why they may deserve a place on your watchlist.
The three founder-led stocks covered below are only a small sample, and the full screen surfaced 60 more businesses with similarly rich stories that do not appear in this article. To see the wider field and start to identify founders whose incentives line up closely with yours, head straight into the Founder-Led Companies screener
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks is a founder-led premium mixer and adult soft drinks business, with co-founder Tim Warrillow still running the group and closely tied to long term outcomes for shareholders. The branded portfolio underpins a £966.3 million market value.
"Although Fevertree Drinks is broadening its range beyond tonic and reports that the wider portfolio now represents nearly half of group sales, a further shift in consumer taste away from mixers could leave the company with high exposure to flavours that fail to scale."
What happens to earnings depends heavily on how one quiet cost pressure interacts with that changing product mix over the next few years.
That cost tension is exactly what the full narrative for Fevertree Drinks unpacks, describing how Fevertree Drinks could turn mix shifts into fresh momentum beyond mixers.

Computacenter (LSE:CCC)
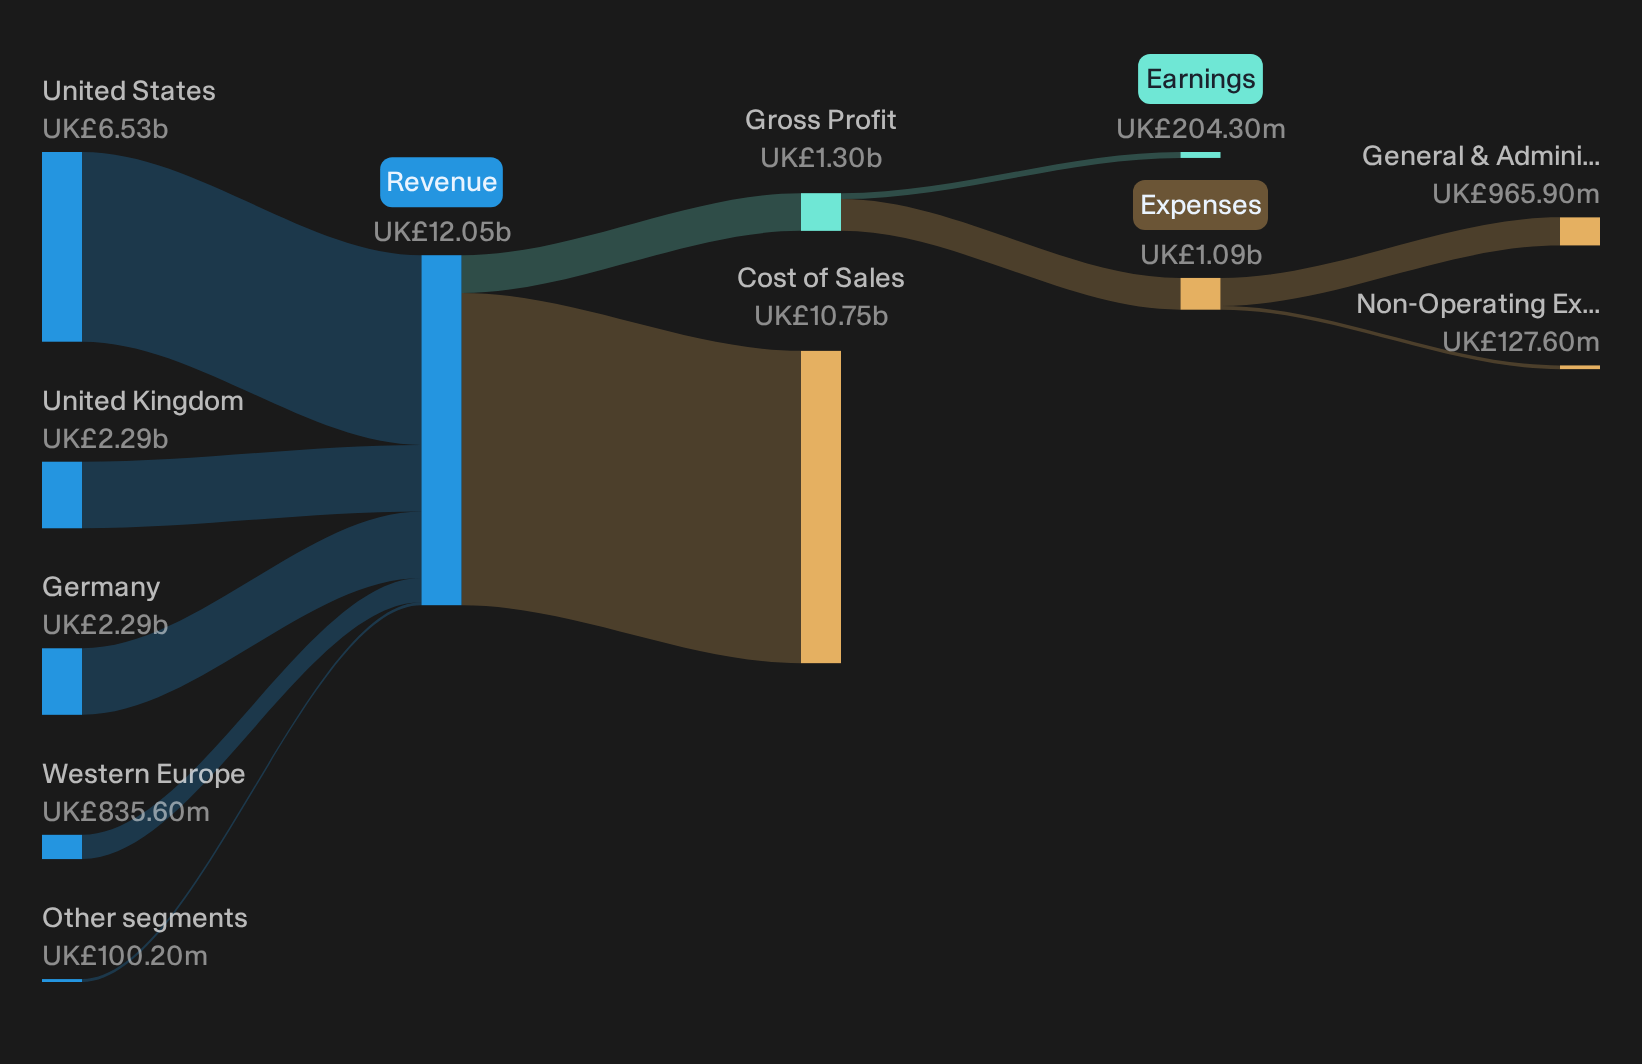
Computacenter is a founder-origin IT services group where long-tenured leadership still shapes how it runs procurement, workplace support, cloud and managed secure networking for large organisations. The business generates about £12.1b from Computer Services and carries a market value of roughly £5.8b.
Computacenter links the founder-led theme directly to the front line of client relationships. Management, with an average 11.8 year tenure, is steering recurring IT services while earnings and dividends both move higher. The question for investors is what happens if one quiet cost pressure keeps nibbling at already thin margins.
If that margin squeeze is on your mind, scan the analysis report for Computacenter to see how Computacenter’s scale, contracts and capital needs all line up.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is a £491 million infrastructure and private equity manager that earns about £114.8 million from Real Assets and £50.1 million from Private Equity, where its hands-on backing of early-stage and founder-led businesses is the clearest link to this founder-focused theme.
Foresight Group leans into the Founder-Led Companies idea by not only funding entrepreneurs but also working alongside them, and investors are watching how that partnership-first model feeds through into long term outcomes for earnings and shareholder returns.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
One question is what happens if one unresolved cost pressure starts to bite just as that founder-led flywheel is trying to spin faster.
If that cost pressure worries you, the full narrative for Foresight Group Holdings outlines how Foresight Group Holdings could keep compounding while earnings, buybacks and dividends begin to decouple.

Seeking Alternatives Before The Crowd Moves
New ideas tend to appear first, prices adjust next, and slower capital can end up chasing momentum. Scan these fresh stock pools while they are still relatively under the radar and consider them before they become widely followed.
- Spot income plays that do more than tread water by reviewing the 1 dividend fortresses before yields change or attention shifts elsewhere.
- Track future-facing miners early by scanning the 33 best rare earth metal stocks while demand stories develop and sentiment has not fully reflected them yet.
- Look for resilient balance sheets and steady cash generators through the list of solid balance sheet and fundamentals (9 results) before broader market interest potentially increases.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com