
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Kasumigaseki CapitalLtd (TSE:3498) Justify Its Valuation Following New Guidance And Dividend Lift?
Kasumigaseki CapitalLtd (TSE:3498) has put fresh numbers on the table, pairing new earnings guidance for the year to August 2027 with a higher expected dividend following its recent 2-for-1 share split.
Investors have reacted quickly to the fresh guidance and dividend outlook, with Kasumigaseki CapitalLtd’s 1-day share price return of 4.46% and 90-day share price return of 15.53% pointing to building momentum, even as the 1-year total shareholder return is down 14.01%. This compares with a much stronger 5-year total shareholder return of about 4.4x.
Scan Kasumigaseki CapitalLtd’s latest guidance against a curated 12 high quality undervalued stocks that also pairs earnings visibility with shareholder returns.
Bulls view Kasumigaseki CapitalLtd’s new guidance and enhanced dividend plan as confirmation of strength, while bears highlight the weaker 1-year return. Which side does the current valuation appear to support next?
Price-to-Earnings of 11.7x: Is it justified?
Kasumigaseki CapitalLtd trades on a P/E of 11.7x, which puts the current ¥7,960 share price at a modest premium to the broader JP market but still below the peer group average.
The P/E ratio compares what investors are paying today for each unit of earnings. For a real estate consulting and asset focused group like Kasumigaseki CapitalLtd, it gives a quick sense of how the market weighs its current profit stream against other listed businesses.
There is a split message here. On one side, the stock looks expensive relative to the JP real estate industry average P/E of 9.6x, which hints that investors are willing to pay more for each yen of profit than they pay for the typical sector peer. On the other side, the same 11.7x multiple sits below the peer average of 13.8x and below an estimated fair P/E of 19.3x, which suggests the valuation could move closer to those higher levels if earnings delivery and guidance hold up.
Explore the SWS fair ratio for Kasumigaseki CapitalLtd.
Result: Price-to-Earnings of 11.7x (ABOUT RIGHT)
Still, the weaker 1-year return and the intrinsic premium flagged by some valuation models could quickly challenge the upbeat Kasumigaseki CapitalLtd narrative if sentiment cools.
Find out about the key risks to this Kasumigaseki CapitalLtd narrative.
Another View Using The SWS DCF Model
The P/E picture for Kasumigaseki CapitalLtd looks roughly in line with the broader market, but the SWS DCF model paints a very different story. On this cash flow view, an estimated value of about ¥955 per share sits far below the current ¥7,960 level. This points to a stock that screens as heavily overvalued and raises the question of how much optimism is already embedded in the price.
Look into how the SWS DCF model arrives at its fair value.
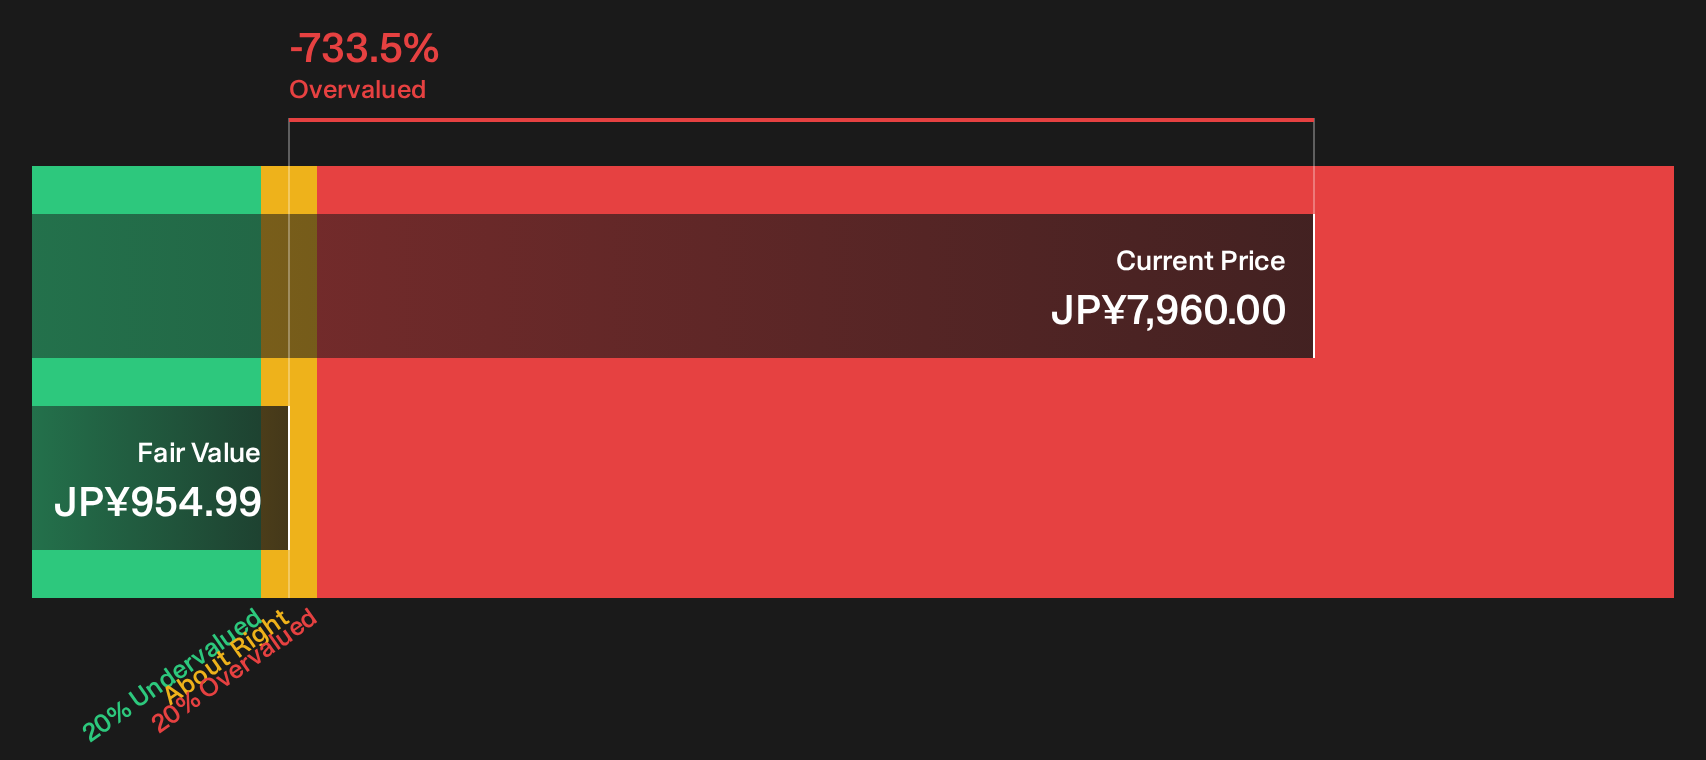
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kasumigaseki CapitalLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mood feels mixed after weighing Kasumigaseki CapitalLtd’s guidance, dividend plan and valuation, so respond quickly, review the full risk and reward profile, then ground your own thesis in the 4 key rewards and 4 important warning signs
Looking for more investment ideas beyond Kasumigaseki CapitalLtd?
If Kasumigaseki CapitalLtd has caught your attention, do not stop here. Use the Simply Wall Street Screener to uncover other opportunities that could fit your approach.
- Spot potential mispricing early by scanning a focused 12 high quality undervalued stocks that pairs quality fundamentals with attractive valuations.
- Secure more predictable cashflows in your portfolio by zeroing in on a curated 28 dividend fortresses backed by robust payout profiles.
- Sleep easier through market swings by filtering for a 23 resilient stocks with low risk scores that screens for resilient balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com