
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Replimune Group (REPL) Could Be 44% Below Fair Value As TUDRIQEV Launch Begins
Why TUDRIQEV’s US Launch Matters For Replimune Group Stock
Replimune Group (REPL) has moved from preparation to execution. The company has begun the US commercial rollout of TUDRIQEV for adults with unresectable advanced cutaneous melanoma after prior PD-1 therapy, marking a key product milestone.
Investors have already reacted to the TUDRIQEV news flow, with Replimune Group’s share price up 50.79% year to date and the 1-year total shareholder return at 196.25%. However, the 30-day share price return is down 7.13%, which suggests strong longer-term momentum alongside a recent pause as the market reassesses execution risk around the launch.
Capitalize on the renewed focus around Replimune Group by scanning hand-picked oncology and high-potential biopharma peers in our 20 high quality undiscovered gems.Replimune Group has already delivered a powerful rebound, yet the business is still pre-commercial with fresh launch risk now front and center. Does that setup still skew the risk reward toward buyers at today’s price once valuation is laid out?
Most Popular Narrative: 44% Undervalued
Replimune Group’s most followed narrative pins fair value at $24 per share, well above the last close of $13.42. This puts the current quote in clear discount territory if those assumptions hold.
The TUDRIQEV label allows injection of superficial, deep and visceral lesions with flexible dosing and retreatment beyond the initial eight doses for patients who keep responding. This can support higher utilization per eligible advanced melanoma patient and therefore greater potential revenue per account over time.
See why 1 investors see Replimune Group as 44% undervalued.
Result: Fair Value of $24 (UNDERVALUED)
Still, the bullish Replimune Group narrative depends heavily on TUDRIQEV’s confirmatory trial succeeding, and on legal overhangs not turning into larger, margin draining outcomes.
Find out about the key risks to this Replimune Group narrative.
Another View: What Multiples Say About Replimune Group
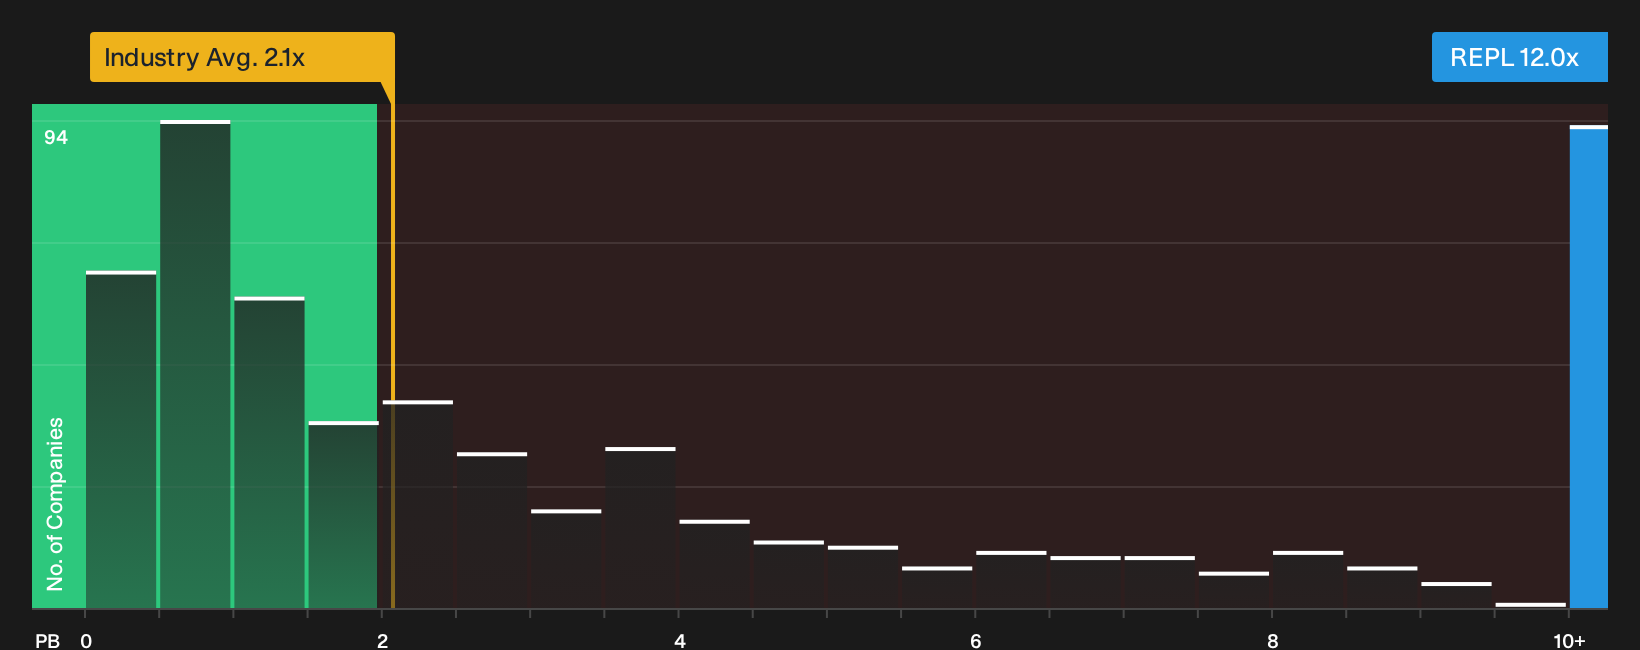
There is a very different picture when you look at Replimune Group through simple market ratios instead of narrative fair value. The stock trades on a P/B of 12x, while the US Biotechs industry sits around 2.1x and close peers average 5.5x. That kind of premium can mean investors are paying up heavily for future success that is still unproven and could magnify any disappointment. Investors may wish to consider whether that rich multiple feels justified for a business that remains loss making and pre revenue today.
For a closer look at how this valuation compares with peers based on this ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Replimune Group story so far. Move quickly from headline impressions to your own judgment by weighing its 2 key rewards and 5 important warning signs.
Looking For More Investment Ideas Beyond Replimune Group?
You have fresh context on Replimune Group. Now put that perspective to work by lining it up against other potential opportunities before the next move passes by.
- Target potential mispricings by scanning a curated set of quality businesses trading below intrinsic estimates using the 28 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that combine higher yields with balance sheet resilience through the 8 dividend fortresses.
- Dial down portfolio risk by focusing on resilient businesses with sturdier financial profiles using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com