
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does New CTO Hire Change The Bull Case For Hilton Worldwide Holdings (HLT)?
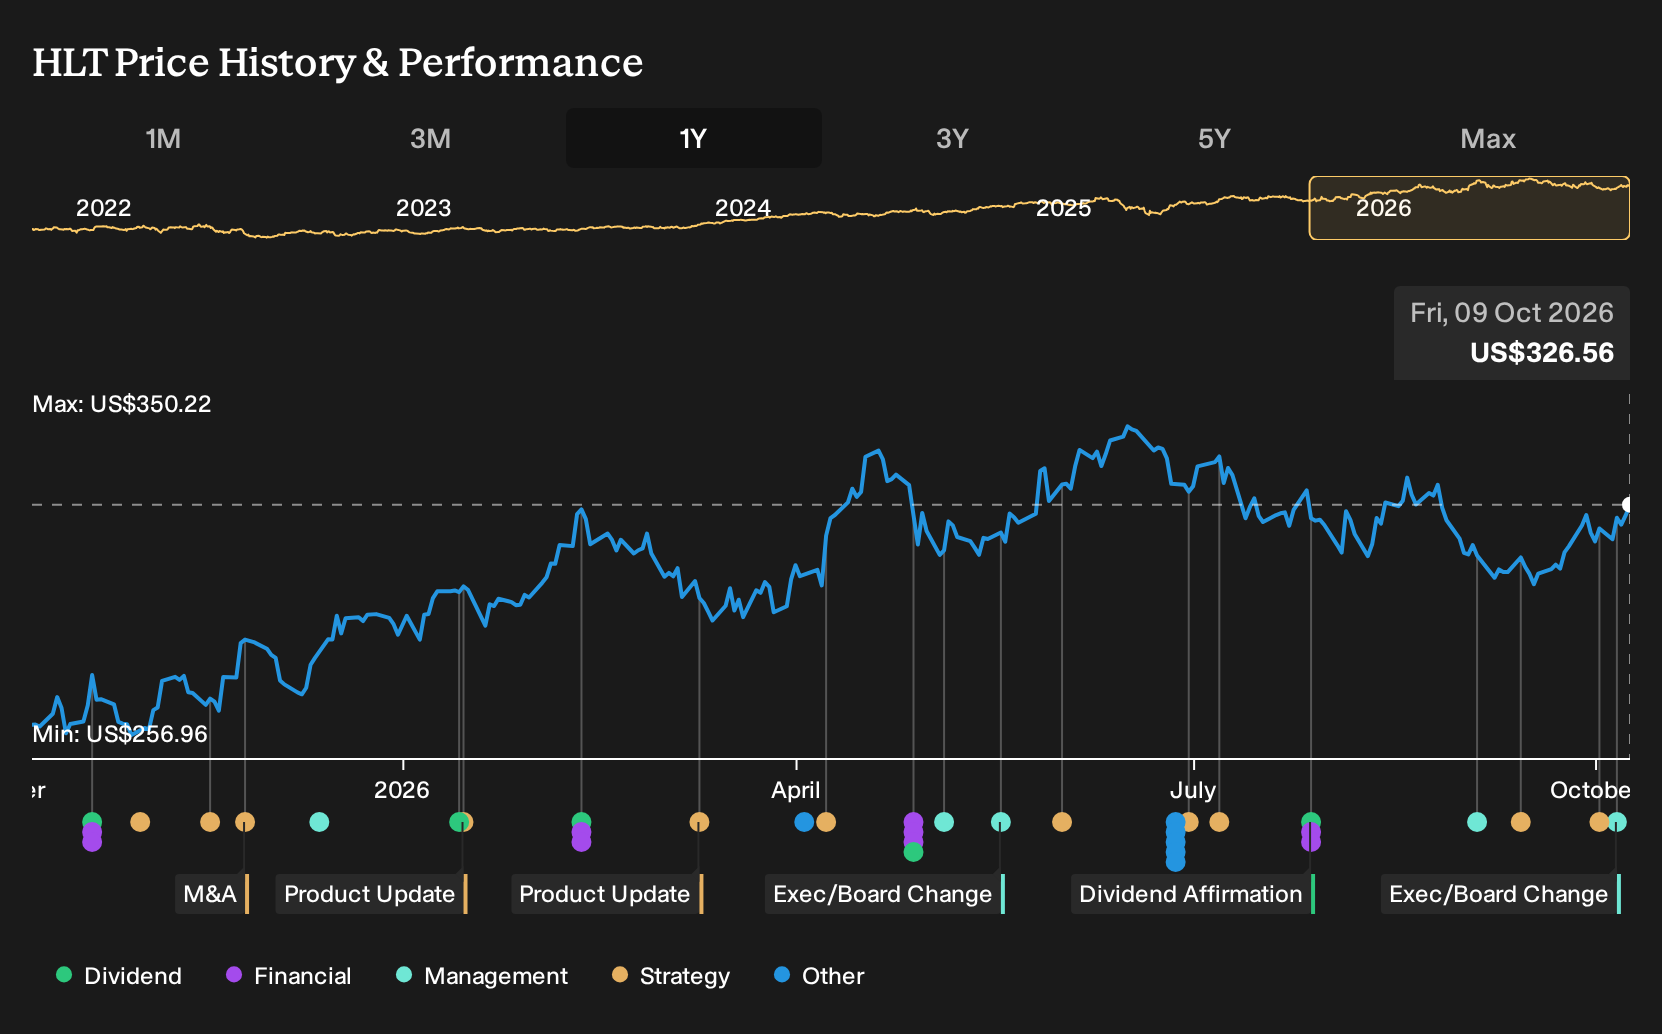
- Hilton Worldwide Holdings recently opened Hale Hokuala Kaua?i, Curio Collection by Hilton, a 210 room lifestyle resort in Hawai?i, and appointed Jeff Moore as Executive Vice President and Chief Technology Officer, ahead of its Q3 2026 earnings report expected on 27 October.
- The combination of expanding Curio Collection presence in a high demand resort market and hiring a seasoned technology leader from Uber and Amazon signals management focus on differentiated guest experiences and more efficient digital infrastructure across Hilton Worldwide Holdings.
- We will now see how Hilton Worldwide Holdings' investment narrative could be shaped by the Jeff Moore technology appointment and Hawai?i expansion.
Hilton Worldwide Holdings Investment Narrative Recap
To stay comfortable owning Hilton Worldwide Holdings, you need to believe its capital light, fee driven model can keep converting a large global pipeline into profitable openings, even with mixed regional demand. The most important near term catalyst remains execution on net unit growth and system wide fee trends when Q3 results land on 27 October.
The biggest current risk sits in softer RevPAR regions and renovation drag at key owned assets, which could weigh on margins if recovery is slower than planned. The Jeff Moore hire and Hawai?i opening appear incremental in the near term and more relevant for multi year positioning than for the upcoming quarter.
The Jeff Moore appointment appears most relevant to Hilton Worldwide Holdings’ push into an AI ready tech stack and direct digital partnerships such as the Navan connection. A seasoned CTO with Uber and Amazon experience provides management with more in house capability to support those large, already announced technology programs.
For you as an investor, the key execution question is whether a stronger engineering organization can lower distribution costs for owners and shift more demand into Hilton controlled channels without disrupting operations. If tech investments roll out slowly or fail to gain adoption, the expected efficiency and margin benefits could be limited.
Hilton Worldwide Holdings' current analyst narrative points to US$16.0b in revenue and US$2.7b in earnings by 2029, based on forecast revenue growth of 46.3% per year and an earnings increase of about US$1.1b from US$1.6b today.
Uncover why Hilton Worldwide Holdings' fair value indicates an 8% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$255 to US$353 per share, which already shows how far opinions on Hilton Worldwide Holdings can stretch. Those views were set before the Hawai?i resort opening and Jeff Moore hire, so fresh earnings, RevPAR trends and tech execution could shift expectations further. If you want a fuller picture, compare several of these community viewpoints before deciding where you sit in that spread.
Explore another Hilton Worldwide Holdings fair value estimate, including one that suggests up to 8% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hilton Worldwide Holdings research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hilton Worldwide Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilton Worldwide Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Hilton Worldwide Holdings?
Once you have a view on Hilton Worldwide Holdings, it can help to cross check that thesis against other businesses with different risk and return profiles using the Simply Wall St Screener.
- If you want potential upside with tighter balance sheet risk, start with a focused 28 high quality undervalued stocks that already pair quality fundamentals with pricing that screens below their estimated worth.
- For steadier cash returns, consider a shortlist of income focused companies and work through a curated 8 dividend fortresses built around higher yield payouts.
- If resilience matters most, begin with a 31 resilient stocks with low risk scores that filters for stronger financial footing and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com