
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Leadership Change Might Change The Case For Investing In Autodesk (ADSK)
- Autodesk has appointed longtime leader Diana Colella as executive vice president of its architecture, engineering and construction business, succeeding retiring AEC head Amy Bunszel and keeping her in place through early November 2026 to support the handover.
- The move puts Autodesk’s AI and cloud push directly under an executive who previously led AI-focused transformation in its Media & Entertainment unit, concentrating responsibility for Forma, Revit, Civil 3D and Autodesk Flow under one leadership umbrella.
- We will look at how Autodesk’s investment narrative is affected by this AI focused AEC leadership change and cloud workflow push.
Scan Autodesk’s AI push against a wider field by lining it up next to 92 AI infrastructure stocks, which is already leaning into cloud workflows and data intelligence for large-scale projects.
Autodesk Investment Narrative Recap
To own Autodesk, you need to believe that AEC customers keep shifting serious work into its cloud and AI stack, not into cheaper or open tools. The short term swing factor is how smoothly Autodesk fuses Forma with Revit, Civil 3D and Autodesk Flow, and whether this happens without creating disruption that slows subscription uptake or irritates existing project teams.
The Colella appointment looks operationally helpful rather than transformative. It concentrates accountability for that AI and cloud roadmap in one veteran leader, which can support execution on current catalysts. The bigger near term risk still sits with AI driven seat pressure and competition from lower cost or AI native rivals, rather than this leadership change.
The Arcadis collaboration is the clearest operational proof point around this leadership shift. It shows Autodesk AI and the Design and Make platform being used inside real client workflows, with Arcadis feeding its own standards and knowledge into Autodesk Assistant and related tools to try to make AI outputs more usable on complex projects.
For you, the interest is that Arcadis is stress testing Forma aligned ideas such as connected data, AI assisted decisions and sustainability use cases like See Through Walls. If those joint projects scale cleanly, they can support the same catalyst investors already watch, stronger AEC cloud adoption, while also exposing Autodesk to data, privacy and execution risks if deployments stumble.
Autodesk AEC Leadership Shift Through The Numbers
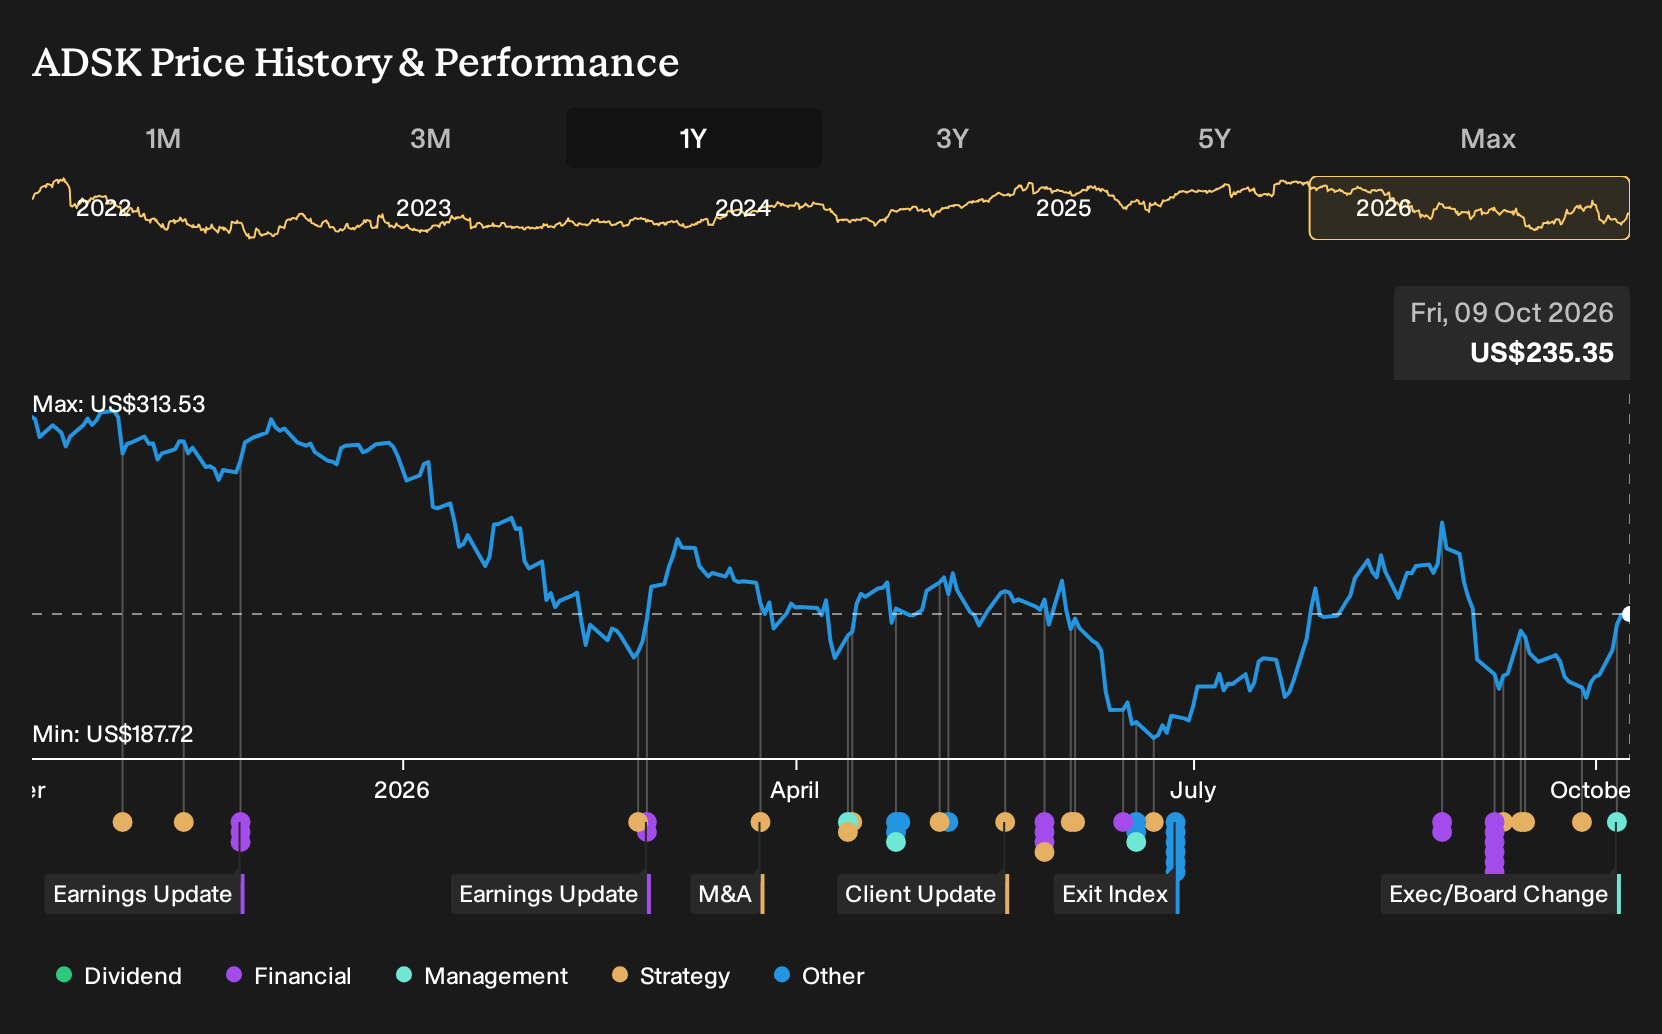
Autodesk's narrative projects US$10.7b revenue and US$2.6b earnings by 2029. This implies 11.2% yearly revenue growth and an earnings increase of about US$1b from US$1.6b today.
Uncover why Autodesk's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on Autodesk’s AI monetization risk rather than just competition. Some of the most optimistic analysts were already assuming revenue of about US$11.2b and earnings near US$2.8b by 2029, with a P/E of 34.6x. Those views came before Colella’s appointment, so your own take may shift as this leadership story unfolds.
Explore 6 other Autodesk fair value estimates, including one that suggests potential upside of up to 57% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Autodesk research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Autodesk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Autodesk's overall financial health at a glance.
Looking For More Investment Ideas Beyond Autodesk?
Once you have formed a view on Autodesk, it can help to compare it with other opportunities that match your preferred mix of quality, risk and income using the Simply Wall St Screener.
- If you want potential value with quality filters, line Autodesk up against a wider field using a 28 high quality undervalued stocks that combines strong fundamentals with attractive pricing.
- For investors who care most about resilience, weigh Autodesk alongside a 31 resilient stocks with low risk scores that highlights companies with more conservative risk profiles.
- If balance sheet strength is your anchor, compare Autodesk with a list of solid balance sheet and fundamentals (25 results) that focuses on businesses backed by sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com