
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dillard's (DDS) Looks Fully Valued As Shares Trade Near DCF Fair Value
Dillard's (DDS) shares recently closed at $654.11, capping a period in which the retailer recorded a 25.44% total return over the past 3 months and 112.22% over the past year.
Recent trading has been choppy for Dillard's, with the share price down 4.08% over the past week and slightly lower over 30 days, yet still posting a 25.44% 3 month share price return and a 322.48% 5 year total shareholder return. This points to longer term momentum that remains intact even as short term sentiment cools.
Scan beyond Dillard's and review other retailers showing strong multi year share price momentum with our curated list of 20 high quality undiscovered gems
Dillard's now trades well above analyst targets after a sharp multi year climb. The key tension is simple: Is most of the re rating already captured, or does the current valuation still leave meaningful upside on the table?
Price-to-Earnings of 15x: Is It Justified For Dillard's?
Dillard's now carries a P/E of 15x, which sits above its own estimated fair level yet below broader retail and market benchmarks at the current $654.11 share price.
The P/E ratio compares what investors are paying today for each dollar of current earnings. For a department store operator like Dillard's, it reflects how the market weighs its profitability profile against relatively modest revenue growth and changing earnings expectations.
On one side, Dillard's trades at a higher P/E than its peer average of 12.4x and above the estimated fair P/E of 9.9x. This points to investors assigning a richer tag than both direct rivals and the statistical fair ratio level the market could move toward. On the other side, the stock still sits on a lower multiple than the US market at 17.9x and the global multiline retail industry at 18x, while the business generates a high 32.1% return on equity and pays a 4.77% dividend yield, so the premium to peers is tied to strong profitability rather than rapid top line expansion.
Explore the SWS fair ratio for Dillard's.
Result: Price-to-Earnings of 15x (OVERVALUED)
Still, Dillard's faces real pressure if annual net income continues to decline or if the share price remains far above analyst targets for an extended period.
Find out about the key risks to this Dillard's narrative.
Another View: Dillard's Through A Cash Flow Lens
The earlier P/E workup flags Dillard's as expensive next to its own fair ratio, even though it trades under the global multiline retail average. A different lens tells a similar story. The SWS DCF model estimates future cash flow value at $638.73 per share, slightly below the current $654.11 level, which points to mild overvaluation rather than a clear bargain. That gap is not huge, but it does raise a simple question for investors: How much are you willing to pay today for cash flows that the model already prices in so tightly?
Look into how the SWS DCF model arrives at its fair value.
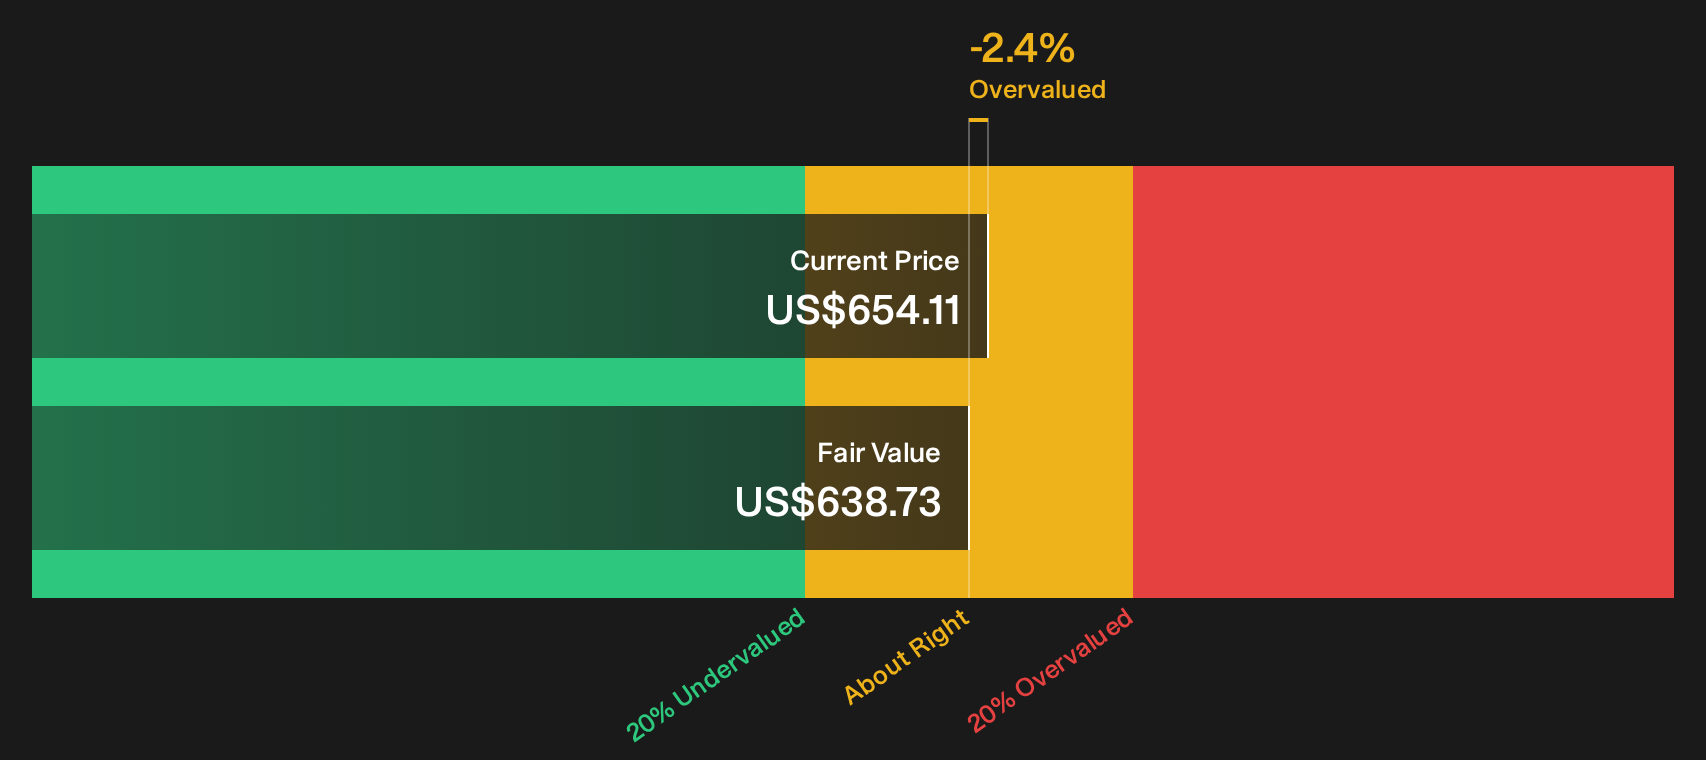
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dillard's for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Dillard's so far. If you want to move quickly and base your stance on more than one angle, weigh up the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Dillard's?
Do not stop your research with Dillard's alone. Broaden your watchlist with a few focused stock ideas sourced directly from Simply Wall Street's screeners.
- Target higher quality value by scanning companies that combine strong fundamentals with attractive pricing using the 28 high quality undervalued stocks.
- Prioritise resilience and cut down on unwelcome surprises by filtering for businesses with stronger financial positions through the list of solid balance sheet and fundamentals (25 results).
- Reduce portfolio stress and stick with steadier performers by zeroing in on 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com