
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hyatt Hotels (H) Tests Its Valuation On Essentials Expansion And New Creative Role
Hyatt Hotels (H) is back in focus after a fresh expansion push in its Essentials Portfolio across the United States, paired with a new Chief Creative Officer role that tightens its brand playbook.
Recent trading tells a mixed story. Hyatt Hotels has a 30 day share price return of 2.34% but a 90 day share price decline of 15.28%. At the same time, the 1 year total shareholder return of 13.93% and 5 year total shareholder return of 91.11% point to stronger longer term momentum that recent expansion news appears to be reconnecting with.
Scan how Hyatt Hotels compares with other hospitality and travel stocks showing strong balance sheets and fundamentals using our hand-picked list of solid balance sheet and fundamentals (25 results) as a starting universe.
So, after a sharp 90-day pullback and a long period of stronger multi-year returns, does Hyatt Hotels still offer a risk-reward profile that justifies new exposure, or has the recent expansion already priced in most of the potential upside, setting a high bar for the next phase of its valuation?
Most Popular Narrative: 17.7% Undervalued
Hyatt Hotels closed at $161.94, while the most followed narrative anchors fair value nearer to $196.83. This frames the recent pullback as a gap between price and the fee based story investors are debating.
The record development pipeline of about 154,000 rooms, with roughly two thirds in international and full service hotels and weighted toward higher fee luxury, lifestyle, inclusive and Essentials brands, points to future rooms and fee growth as properties open and begin contributing to revenue.
The shift toward an asset-light, fee driven model, supported by 9% to 11% expected gross fee growth in 2026 and at least 50% conversion of adjusted EBITDA to free cash flow, indicates a mix shift toward higher margin fee streams that can improve cash generation and earnings quality.
See why 6 investors see Hyatt Hotels as 18% undervalued.
Result: Fair Value of $196.83 (UNDERVALUED)
Still, softer all inclusive RevPAR and weaker Middle East and Mexican resort fee income are already pressuring the Hyatt Hotels story and leave less room for execution missteps.
Find out about the key risks to this Hyatt Hotels narrative.
Another View: Hyatt Hotels Looking Expensive On Sales
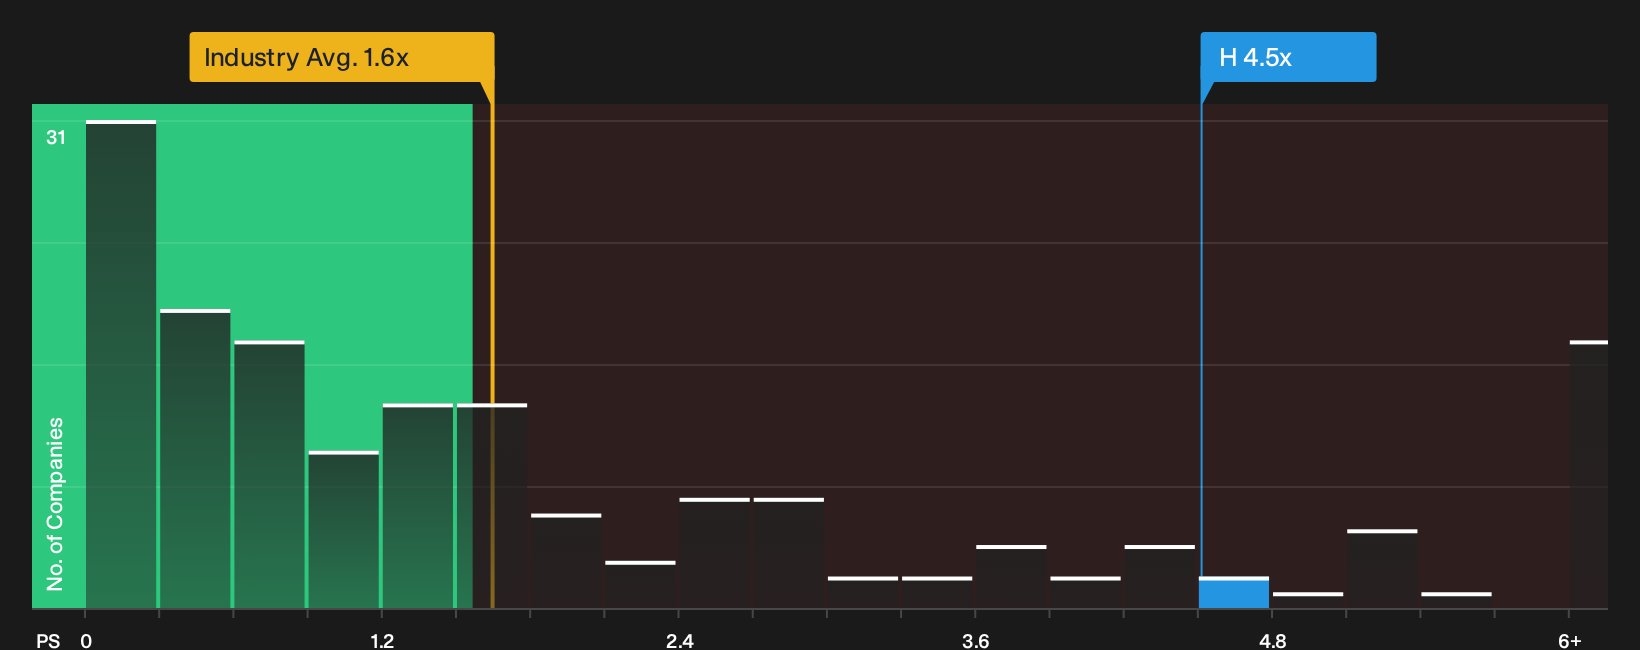
Hyatt Hotels might look appealing against the $196.83 fair value from the consensus narrative, but its P/S ratio of 4.5x is rich. The broader US Hospitality group sits at 1.7x and the fair ratio for Hyatt is 3.4x, which points to a valuation that already bakes in a lot of optimism. This may limit the potential upside if sentiment cools from here.
For a closer look at how this sales based view lines up against Hyatt Hotels' broader valuation story, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Hyatt Hotels so far. If you want to move fast and decide where you stand, start with its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Hyatt Hotels?
If Hyatt Hotels has your attention, broaden your watchlist with a few focused stock ideas that line up more closely with the type of portfolio you want to build.
- Target long term compounding potential by scanning a curated set of attractively priced quality stocks through the 28 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on companies with robust yields and staying power using the 8 dividend fortresses.
- Dial back risk and focus on resilience by filtering for financially sturdy businesses through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com