
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Raised Earnings Guidance Change The Bull Case For Crown Holdings (CCK)?
- Crown Holdings recently raised its full year 2026 earnings guidance after stronger than expected second quarter results, and analysts now forecast third quarter earnings of $2.26 per share.
- The upgraded outlook highlights how current packaging demand and cost execution are feeding into Crown Holdings' profit expectations, while analyst coverage mainly reflects this fundamental shift.
- We will look at how Crown Holdings' investment narrative is shaped by the higher full year earnings guidance after solid recent results.
Scan how Crown Holdings' earnings upgrade fits into a wider packaging and industrial recovery story by comparing it with a curated list of list of solid balance sheet and fundamentals (25 results).
Crown Holdings Investment Narrative Recap
Crown Holdings appeals to shareholders who buy into a steady metal packaging story, where tight capacity, sustainability tailwinds and disciplined capital spending all matter more than rapid top line expansion. The upgraded 2026 earnings guidance and expected Q3 earnings of US$2.26 per share point to an operating setup that currently supports that thesis.
The key short term swing factor is how effectively Crown Holdings converts can demand and Transit Packaging activity into cash while offsetting higher freight, energy and industrial gas costs. The biggest risk remains cost pressure and Brazil softness capping Americas Beverage income, so the recent guidance lift does not remove that concern.
The most relevant update for this news is management raising full year 2026 earnings guidance after better than expected Q2 results. That move connects directly to the near term catalyst investors are watching, which is the Q3 earnings delivery against the US$2.26 per share forecast.
This upgrade sits on top of ongoing capacity projects in Brazil, Greece, Spain and India and continued focus on operational efficiency. For you, the question is whether Crown Holdings can keep offsetting input inflation and higher freight while keeping free cash flow strong enough to support capex, debt service and ongoing capital returns.
Crown Holdings Earnings Framework Through 2029
Crown Holdings now sits on an earnings story that stretches well beyond the near term guidance lift. Analysts are building their models around a gradual revenue increase, firmer margins and a tighter share count, which together frame how the upgraded near term outlook feeds into the September 2029 earnings consensus.
The analyst set assumes Crown Holdings can grow revenue by 2.9% each year over the next three years while nudging profit margins from 5.9% today to 6.5% by around 2029. In that framework, current earnings of US$784.0 million are expected to reach US$937.0 million and consensus earnings per share reach US$8.99 by the 2029 estimate year.
That earnings path implies an increase of about US$153.0 million from today's earnings to the 2029 forecast, supported by expectations that the number of shares on issue declines by roughly 5.71% per year over the next three years. Analyst models also use a discount rate of 7.5% and assume the shares would trade on a P/E of 16.3x those 2029 earnings, compared with 14.9x today and below the 17.8x currently applied to the wider US packaging group.
Crown Holdings' future valuation narrative ties directly to those operating assumptions. The analyst consensus points to revenues of US$14.4b and earnings of US$937.0 million by 2029, both discounted back using a 7.5% rate and paired with a 16.3x P/E multiple to reach a fair value view.
Crown Holdings' narrative projects US$14.4b revenue and US$937.0 million earnings by 2029. This setup assumes 2.9% yearly revenue growth and about a US$153.0 million earnings increase from current earnings of US$784.0 million.
Uncover why Crown Holdings' fair value indicates a 26% potential upside to its current price. This discount could narrow quickly if sentiment shifts.
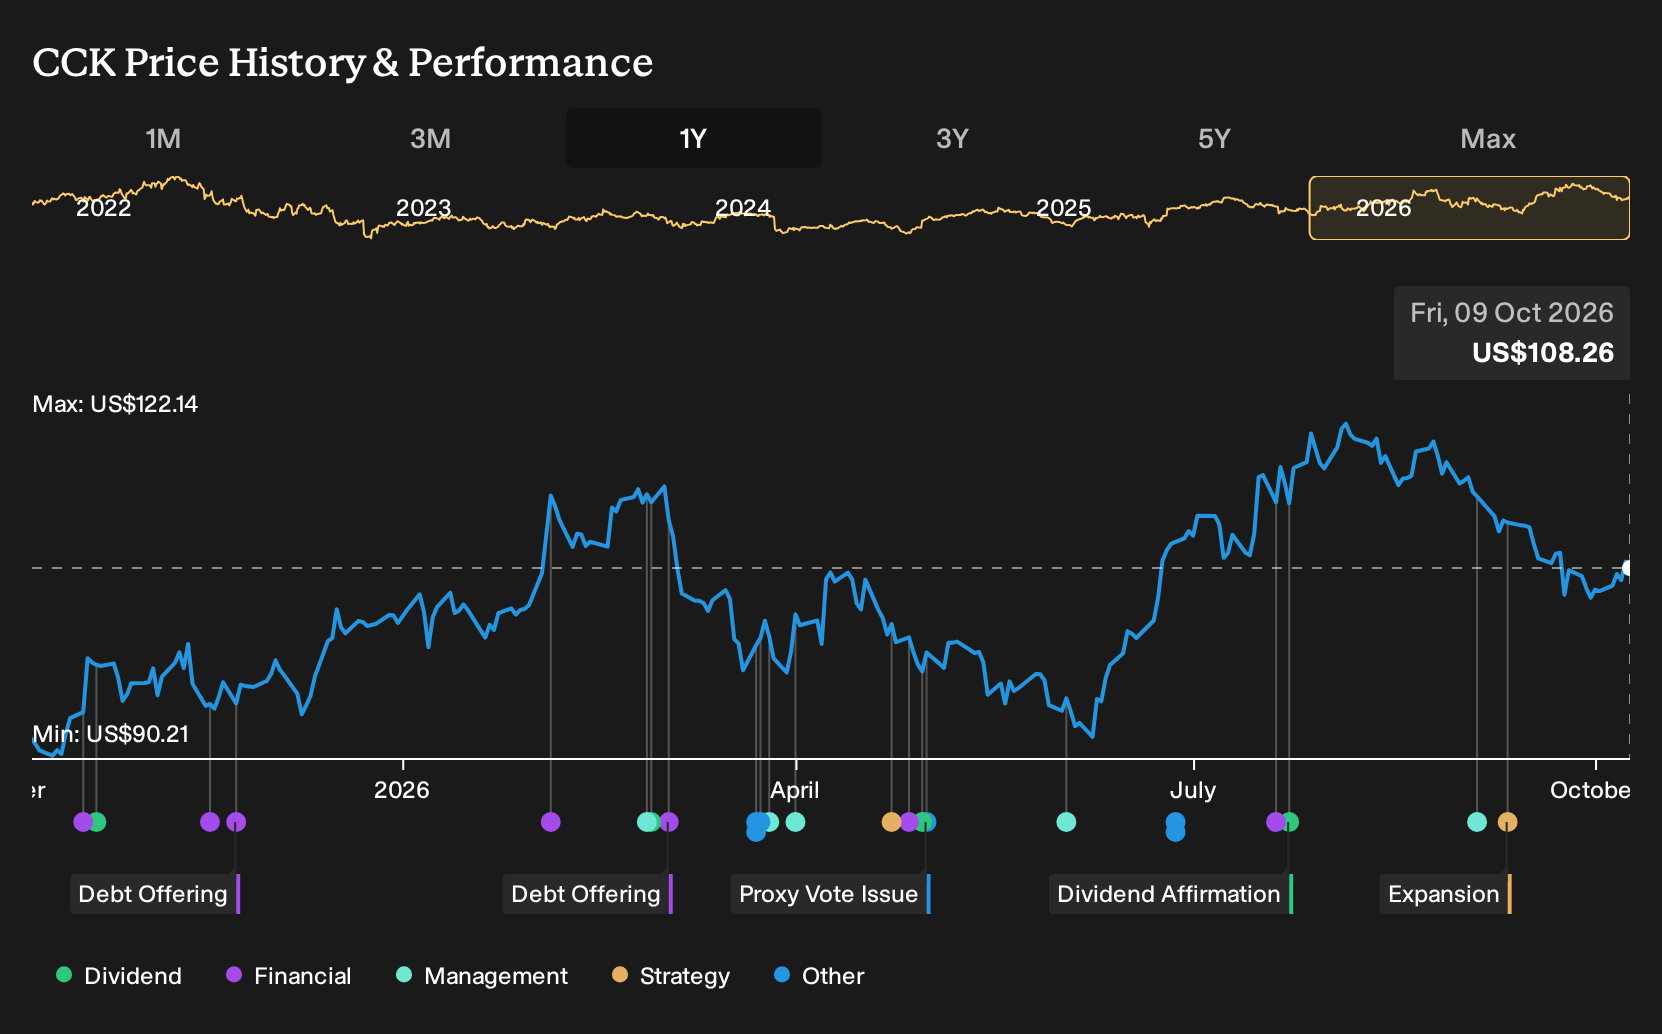
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span from just US$76 to more than US$386.3b, so opinions on Crown Holdings are clearly scattered. Treat that spread as a prompt to test your own thesis against risks like cost inflation, as well as catalysts such as capacity expansion and sustainability driven can demand.
Explore 3 other Crown Holdings fair value estimates, including one that suggests as much as 356833955956% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own. Crown Holdings deserves that level of attention if you are weighing it against other packaging and industrial options.
- A great starting point for your Crown Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Crown Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crown Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Crown Holdings?
If Crown Holdings has sharpened your view on what you want from an earnings profile, you can use that same checklist across the wider market. A focused screener helps you line up other candidates that fit your risk tolerance, balance sheet preferences and income needs instead of relying on headlines or hunches.
- If resilience matters most to you, start with a curated universe of companies that already score well on debt and liquidity through a list of solid balance sheet and fundamentals (25 results).
- If you prefer opportunities where quality and valuation intersect, compare Crown Holdings with a hand picked group of potentially mispriced businesses using a 28 high quality undervalued stocks.
- If reliable cash distributions are a priority, focus your research on income opportunities by scanning a targeted 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com