
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
YONEX (TSE:7906) Could Be 43% Below Fair Value As Valuation Signals Split
YONEX (TSE:7906) drew fresh attention after its recent share price move, with the stock up 1% on the day and modestly higher over the past week despite a weaker year-to-date showing.
For YONEX, the 1-day share price return of 0.97% and 7-day gain of 2.85% come after a tougher spell, with the 30-day share price return down 6.25% and the year to date share price return lower by 29.15%.
That recent uptick hints at improving sentiment after a weak stretch. However, the 1-year total shareholder return is still down 37.45%, while the 5-year total shareholder return of 231.56% shows how long term holders have seen a very different outcome.
Compare YONEX's recent pullback and rebound with a hand picked group of quality stocks on the move by scanning the 12 high quality undervalued stocks.
Bulls view YONEX as a quality sports brand available at a discount after a sharp pullback, while bears point to the recent slump in returns. The key question is which side the current valuation clues appear to support next.
Price-to-Earnings of 15.2x: Is it justified?
YONEX last closed at ¥2,384, and on a P/E of 15.2x it screens as only slightly cheaper than what the fair value model suggests and a little below where similar leisure stocks are priced.
The P/E ratio compares the current share price with earnings per share, so for a consumer durables brand like YONEX it gives a quick read on how much investors are paying for each unit of profit. For a business with established products rather than an early stage concept, this kind of earnings based gauge is especially relevant.
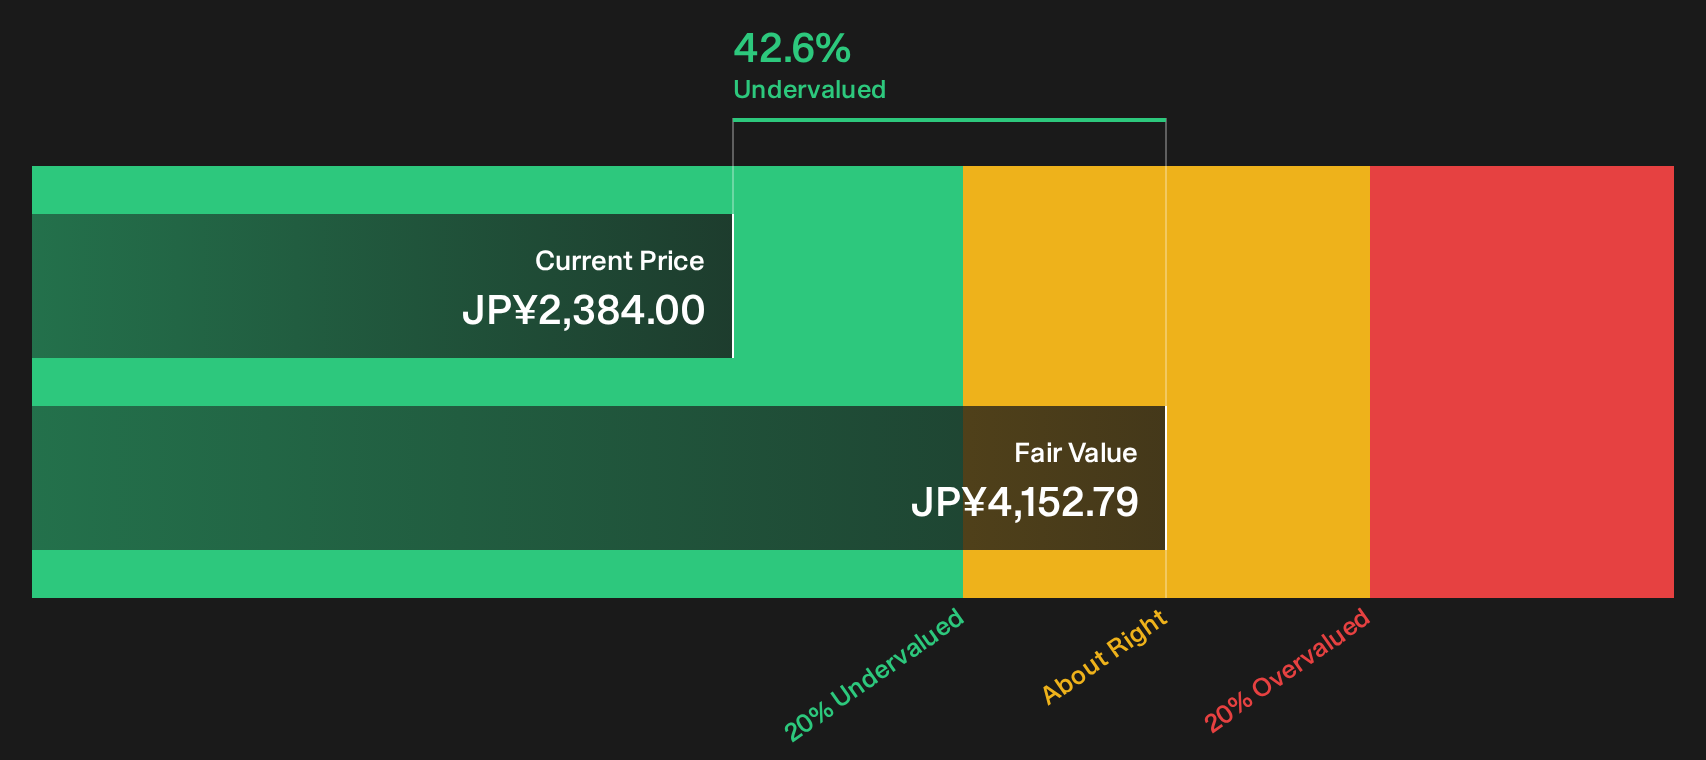
On one side, the stock is described as trading at a 42.6% discount to an internal fair value estimate and it is also below the JP Leisure industry average P/E of 15.7x and the peer group average of 17.5x. On the other side, that 15.2x multiple is slightly above the modelled fair P/E of 15.1x, which suggests the market is already close to the level that regression based analysis points to over time.
Relative to the sector, the pricing gap is clear. YONEX carries a lower P/E than both the wider leisure group and its selected peers, which indicates investors are paying less for each yen of earnings than they are for comparable stocks.
Explore the SWS fair ratio for YONEX.
Result: Preferred multiple of 15.2x price-to-earnings (ABOUT RIGHT)
Still, the weak 1 year shareholder return and 29.15% year to date decline leave sentiment fragile, so any setback to YONEX earnings or demand trends could quickly cap this rebound.
Find out about the key risks to this YONEX narrative.
Another view on YONEX value
There is a different message coming from the SWS DCF model. At ¥2,384, YONEX is described as trading below an estimated future cash flow value of ¥4,152.79, which points to a large implied discount rather than a fairly priced stock.
That kind of gap suggests the market may be putting more weight on recent share price weakness and softer returns than on long term cash generation. The question for you is which signal carries more weight: the earnings multiple or the cash flow math.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out YONEX for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this YONEX update is mixed, with valuation signals pulling in different directions. It may be useful to review the numbers directly and decide quickly how that stacks up for you. If you want a concise summary of what the brighter angles look like, start with the 3 key rewards
Looking for more YONEX sized investment ideas?
If you stop with YONEX, you only see one angle. Cast a wider net now and give yourself more chances to find the next standout opportunity.
- Pinpoint potential bargain opportunities early by scanning a curated list of quality ideas through the 74 high quality undiscovered gems.
- Strengthen your defensive side by reviewing the 23 resilient stocks with low risk scores that aim to keep portfolio swings more controlled.
- Target resilient balance sheets by using the list of solid balance sheet and fundamentals (23 results) to focus on businesses with sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com