
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Caledonia Mining (CMCL) Cuts Blanket Guidance, Is The Stock Undervalued Or Overvalued?
Caledonia Mining (NYSEAM:CMCL) is back in focus after cutting its 2026 production guidance for the Blanket mine and reporting lower third quarter gold output, which may reshape how investors frame risk at this producer.
Those guidance cuts and softer third quarter output have come alongside a share price that fell 8.6% over the past month but rose 33.7% over 90 days, while total shareholder return is down 29.8% over one year yet still more than doubles over three and five years. This suggests that momentum has cooled recently after a strong multi year run as investors reassess production risk at Caledonia Mining.
Position your portfolio for potential production surprises by comparing Caledonia Mining with 36 elite gold producer stocks, which has been filtered for quality and resilience in the gold sector.After that sharp swing, investors in Caledonia Mining face a simple fork in the road. They can either lean into the current reset or wait for the valuation to better reflect the revised Blanket outlook.
Most Popular Narrative: 52% Undervalued
On the most followed valuation view, Caledonia Mining is seen as worth $49.43 a share, which sits well above the last close at $23.75 and frames the current price as heavily discounted.
Caledonia Mining Corporation (NYSE: CMCL) currently trades near $24.00 with a market capitalization of roughly $480 million, presenting a stark divergence between its cash generation and its politically discounted equity valuation. With FY 2025 revenue of $267.7 million, EBITDA of $125.3 million, and a net cash position of $23.8 million, the baseline is described as mispriced relative to global peers.
See why 3 investors see Caledonia Mining as 52% undervalued.
Result: Fair Value of $49.43 (UNDERVALUED)
Still, the entire Caledonia Mining story leans heavily on Zimbabwe country risk and successful execution at Bilboes; any setback there could quickly challenge this valuation case.
Find out about the key risks to this Caledonia Mining narrative.
Another View: SWS DCF Flags Overvaluation
A different lens on Caledonia Mining tells a very different story. The SWS DCF model estimates future cash flows at $7.18 per share, which sits well below the recent $23.75 price and frames the stock as overvalued on this approach.
This gap suggests valuation risk if cash generation or project execution underwhelm against optimistic scenarios, especially with all key assets in a single high risk jurisdiction. It raises a simple question for investors: Which lens should carry more weight in your own process, the asset based narrative or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
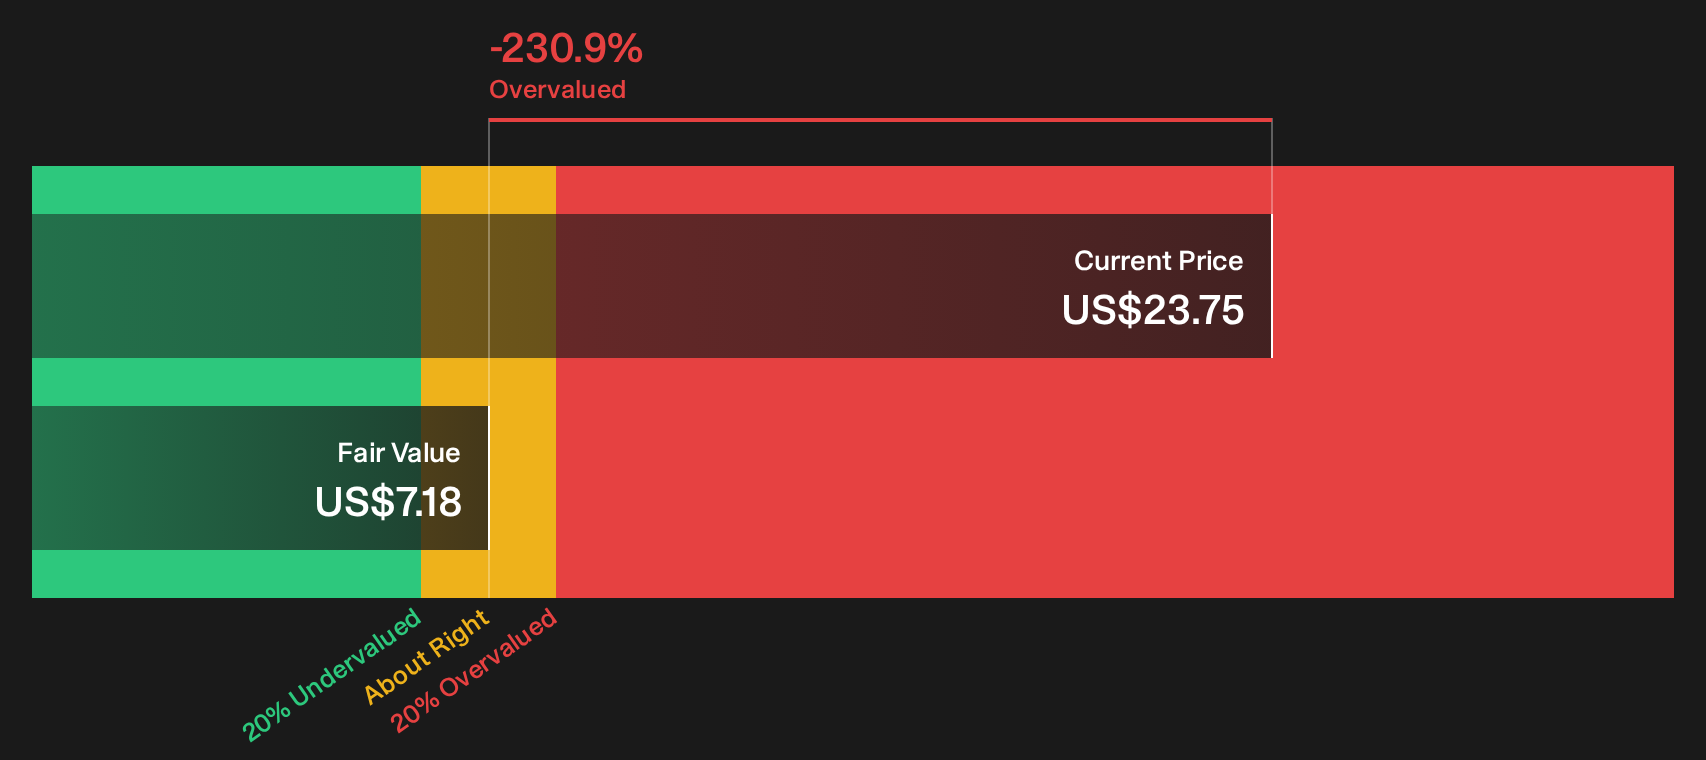
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Caledonia Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Caledonia Mining can make any view feel provisional. Move quickly, test the numbers yourself and challenge the headlines using the 6 key rewards.
Looking for more investment ideas beyond Caledonia Mining?
If Caledonia Mining sharpened your focus on risk and reward, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities across different styles and balance sheet profiles.
- Target potential mispricing by scanning across markets for companies that line up with your quality checklist using the 28 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with robust finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Explore under followed quality stories with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com