
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Coherent (COHR) Could Be 25% Undervalued Following AI Demand And Earnings Strength
Coherent (COHR) is back in focus after sharp swings tied to AI infrastructure expectations, strong recent earnings and revenue growth, and fresh worries about rising Treasury yields affecting high-multiple tech stocks.
Against this choppy backdrop, Coherent’s share price has swung between profit taking and renewed enthusiasm around AI spending. It still carries a year to date share price return of 60.87% and a 1 year total shareholder return of 181.39%, signalling momentum that has cooled in recent weeks rather than fully reversed.
Capitalize on the AI optics story driving Coherent by scanning a hand picked set of 92 AI infrastructure stocks aligned with surging data center investment.Coherent has already delivered huge gains on the AI optics story, yet the recent pullback and rich expectations leave a simple puzzle. Is the real upside still in front of investors, or mostly in the rearview mirror as valuation stretches?
Most Popular Narrative: 25% Undervalued
On the most followed view of Coherent, a fair value of $415.36 sits well above the last close at $312.62, and that gap only makes sense if the AI datacenter story and margin uplift play out as modeled.
The ongoing expansion of AI datacenter infrastructure and high-performance computing is propelling structural growth in demand for advanced optical transceivers (800G, 1.6T, and beyond), optical circuit switches, and related photonics components, which is fueling robust sequential order growth and sustained revenue momentum in Coherent's datacom and communications business.
See why 117 investors see Coherent as 25% undervalued.
Result: Fair Value of $415.36 (UNDERVALUED)
Still, Coherent’s reliance on a handful of large customers, along with the heavy capital needed for new fabs, could quickly pressure the story if demand expectations reset.
Find out about the key risks to this Coherent narrative.
Another View: What Coherent’s P/E Is Telling You
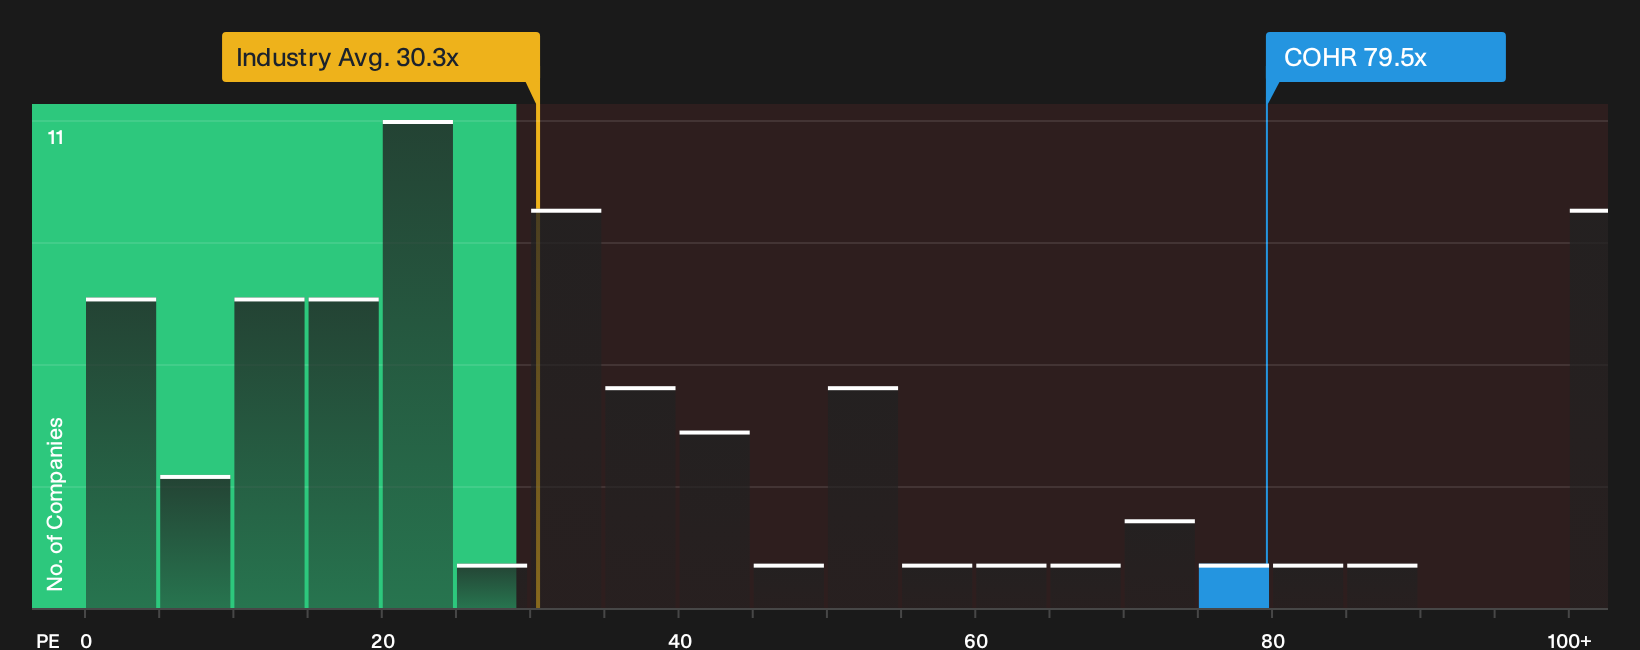
Those fair value models paint Coherent as about 25% undervalued, yet the simple P/E picture is tougher. The stock trades on roughly 79.5x earnings versus a fair ratio of 71.9x, the US Electronic industry at 30.3x, and peers at 43.5x. That gap points to real valuation risk if sentiment cools. Where do you think the multiple moves next?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these do not settle the debate on Coherent for you. Consider acting while the story is still evolving by weighing its 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Coherent?
You have seen how complex Coherent can be. Now widen your field of view and give yourself more options before the next big move passes you by.
- Target potential mispricing by scanning a curated 28 high quality undervalued stocks that combine robust fundamentals with prices that may not fully reflect their underlying strength.
- Prioritize income and resilience by reviewing a focused set of 8 dividend fortresses that aim to balance yield with balance sheet quality.
- Dial down portfolio stress by filtering for 31 resilient stocks with low risk scores that show steadier financial profiles and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com