
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fastly (FSLY) Lands Comcast Tie Up As Bullish Valuation Case Faces A Reality Check
Fastly (FSLY) is back in focus after Comcast and NBCUniversal highlighted a new way of running Fastly’s content delivery software directly inside Comcast’s nationwide network for Peacock’s biggest live streaming events.
Fastly’s recent tie-up with Comcast lands during a strong run in the stock, with a 1-day share price return of 15.86% pushing the latest share price to US$29.30. This has contributed to a 187.54% year to date share price return and 256.01% 1-year total shareholder return as enthusiasm around larger deals, security products and AI traffic gathers pace.
Spot similar momentum in edge and AI traffic by scanning our hand picked 92 AI infrastructure stocks that are also positioned for heavy streaming and compute demand.Fastly has already delivered a huge rebound, and the stock now trades roughly in line with analyst targets. The next step is to ask whether that surge has overshot the business or still leaves room on the table.
Most Popular Narrative: 19% Undervalued
Fastly's most followed narrative pegs fair value at about $36.31, comfortably above the last close at $29.30. This puts the recent Comcast momentum into a sharper context for anyone weighing how much optimism is already in the price.
Fastly is uniquely positioned to capitalize as global internet usage, real-time applications, IoT, and connected device adoption accelerate, which will structurally support increasing CDN and edge compute volume per customer and drive long-term, multi-year compounding revenue growth well above industry averages.
The platform's programmable, developer-centric architecture is fostering deeper integration into customers' cloud-native tech stacks, resulting in increased retention, higher switching costs, and growing usage intensity, all of which will boost lifetime value, support rising revenue per user, and enhance earnings visibility as usage-based models scale.
See why 5 investors see Fastly as 19% undervalued.
Result: Fair Value of $36.31 (UNDERVALUED)
Still, Fastly’s reliance on a concentrated customer base and ongoing operating losses means that any slowdown in large accounts could challenge the bullish narrative.
Find out about the key risks to this Fastly narrative.
Another View: Fastly Through A Cash Flow Lens
The upbeat fair value of $36.31 leans heavily on future earnings assumptions. A different lens tells a cooler story. The Simply Wall St DCF model puts Fastly’s future cash flows closer to $14.75 per share, which would leave the stock looking expensive rather than undervalued. Which model do you trust more when real cash is on the line?
Look into how the SWS DCF model arrives at its fair value.
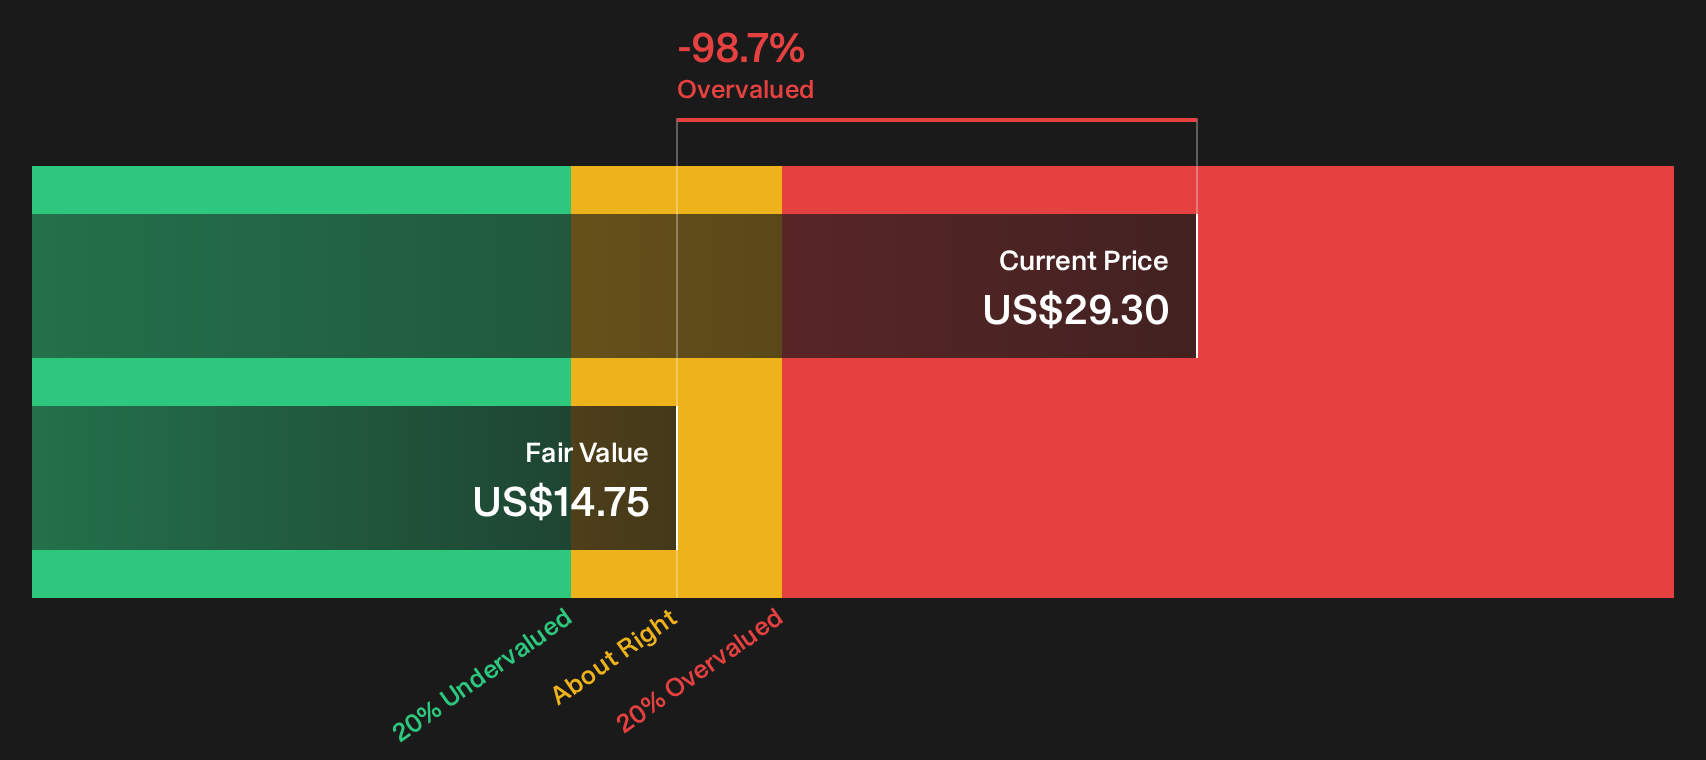
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fastly for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Fastly clearly divides opinion, with strong enthusiasm on one side and real concerns on the other. Move quickly and weigh the trade off for yourself using the 1 key reward and 3 important warning signs.
Looking for more Fastly-sized opportunities?
If Fastly has sharpened your focus, do not stop there. Use the Simply Wall St Screener to spot fresh ideas before they move without you.
- Target quality at a discount by scanning companies that pass the 28 high quality undervalued stocks and see which ones fit your approach.
- Prioritize sleep-at-night resilience by filtering for companies in the 31 resilient stocks with low risk scores that score well on business stability.
- Hunt for early-stage potential by reviewing the 20 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com